You're Always At Home With Refind Realty.
Serving Your DFW Real Estate Needs Since 2005.
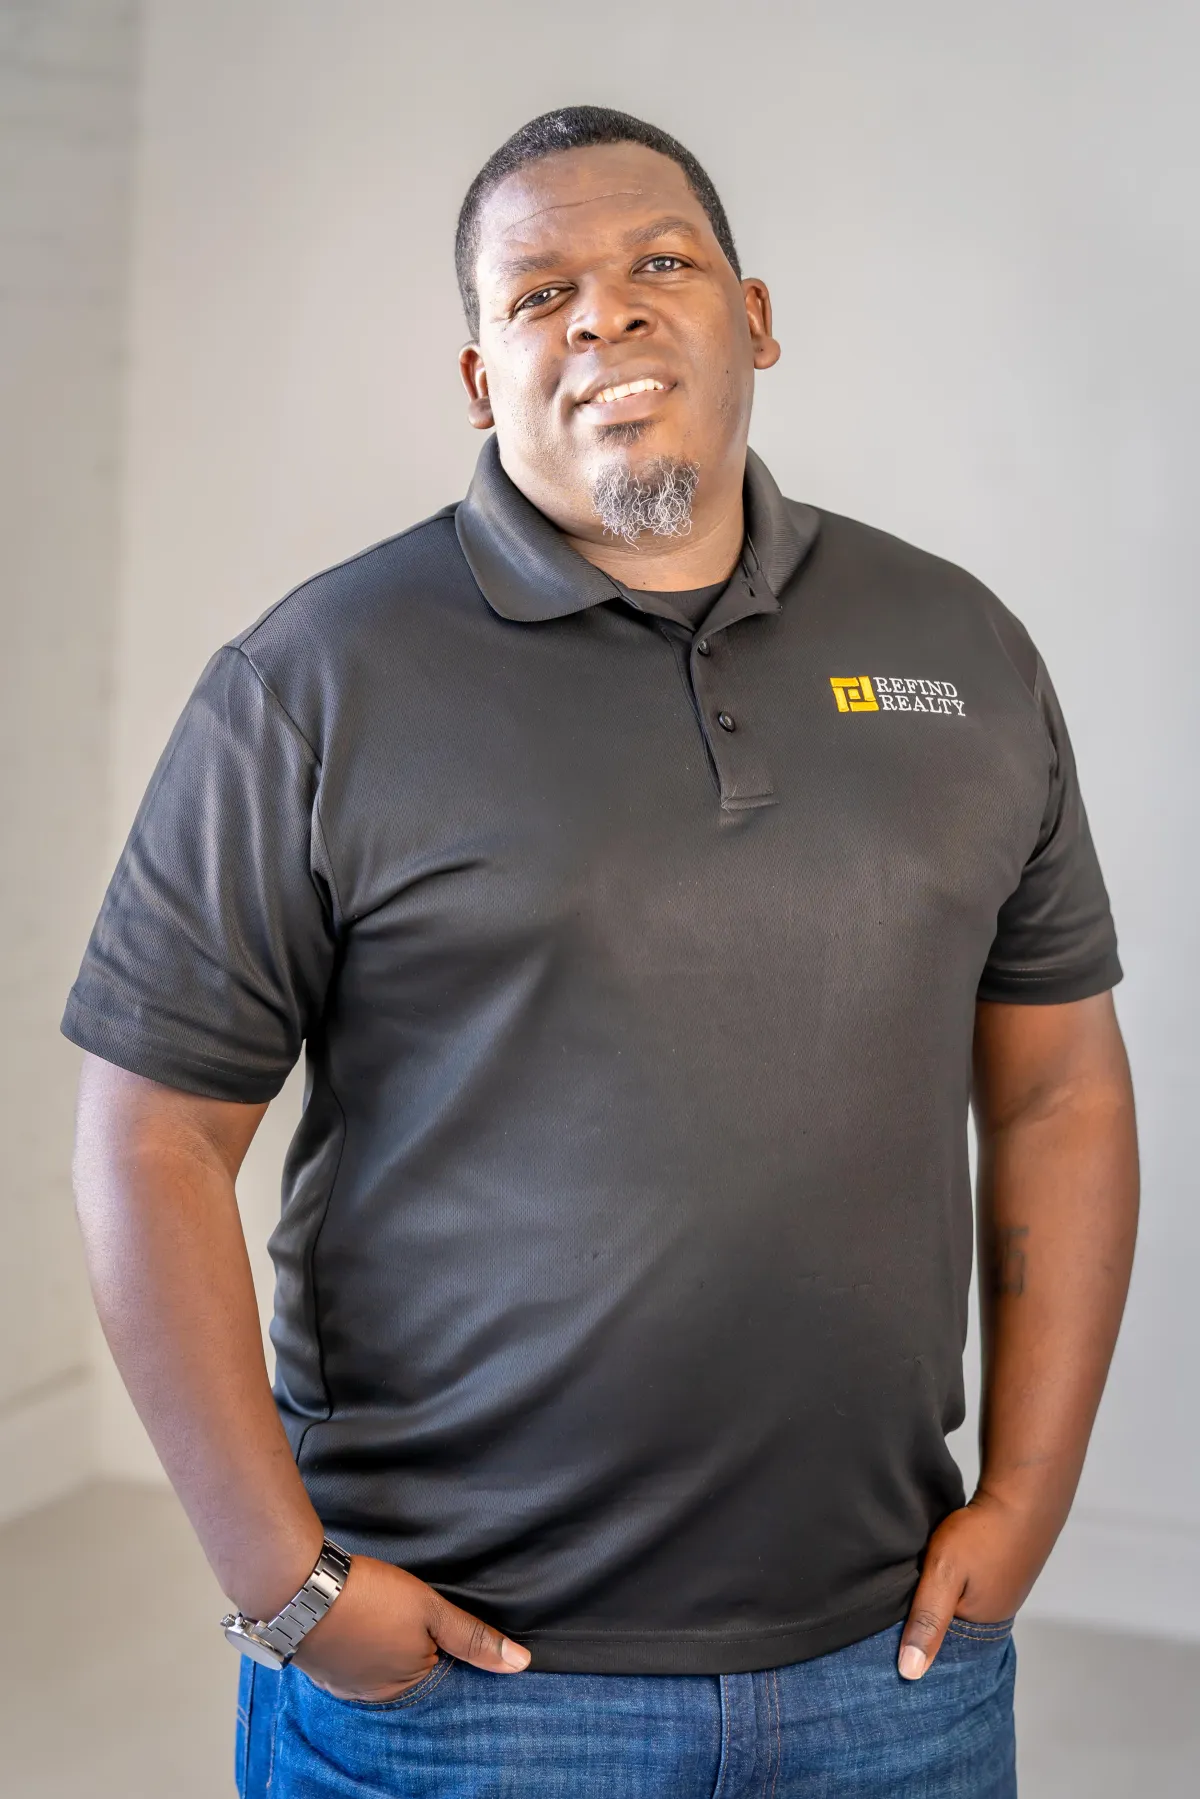
Refind Realty Inc is a Black-owned independent brokerage in DeSoto, in business since 2005. Steven J. Thomas is an owner and associate broker of Refind Realty Inc and leads its Refind Realty DFW division.
We Help You Buy and Sell in The Greater Dallas-Fort Worth Area.
Check Out Our Social Media Channels!
Buying in DFW
Buying your first or next home should be a rewarding and exciting time in your life, and one that you look back on with fond memories.
Thinking Of selling?
The market has changed a lot and I'd love to show you the exact strategy I use to get sellers in DFW top dollar for their property.
Get Pre-Approved
Let me walk you through the entire pre-approval process so you know exactly how much home you can afford.
Sign Up For my
Email List
My emails are a great way to stay up-to-date with local news and real estate market trends, even if you're not currently in the market. So, come on and join me to stay in the loop!
affordability Calculator
Get pre-approved to know exactly how much house you can afford. Use this calculator to get a quick estimate. Contact me for assistance!
DFW New Construction
Discover the latest new home constructions in DFW and take advantage of the builder incentives that are available now.
Let's Make Your real estate Dreams Come True.
Newest Listings
Call Me Today At (972) 846-9170
Refind Realty Blog:

How Much Under Asking Do DeSoto, TX Homes Sell For?
Last updated October 27, 2026
DeSoto homes closed at 93.8% of list price in September 2026, per the NTREIS monthly report. On the $360,000 median sale, that is about $23,800 under the original asking price. The number is a market-wide average. A home priced right in week one closes closer to list. A home priced at last year's number sits.
Most agents will tell you to "price high and leave room to negotiate." In DeSoto, the room is already in the data, and it costs you days. Pricing takes a walk-through, not an online estimate. Here is the math.
Do DeSoto sellers have to cut their price right now?
Many do, because supply is up. DeSoto had 4.9 months of supply in September 2026, up from 3.9 a year ago, with 180 active listings versus 165 (NTREIS, September 2026). New listings fell 14% to 54, so fewer sellers are coming on, but the ones already listed are staying put. Median days on market was 68, down from 78.
What does 93.8% mean for my list price?
It means the typical DeSoto sale closed about 6.2% under list. Apply that ratio to your list price and you see the gap in dollars. Each 1% of list price on a $400,000 home is $4,000.
| List price | Close at 93.8% | Gap to list |
|---|---|---|
| $350,000 | $328,300 | $21,700 |
| $400,000 | $375,200 | $24,800 |
| $450,000 | $422,100 | $27,900 |
Illustration only. It applies DeSoto's September 2026 average sold-to-list ratio (NTREIS) to three list prices. Your home will not close at exactly this ratio, and results depend on condition, price and timing.
Why do some DeSoto homes close closer to list?
Condition and price. DeSoto's median sold price held at $360,000 from September 2025 to September 2026, while the median price per square foot slipped 5.3% to $147.55 from $155.86 (NTREIS). Flat median, falling price per foot: the updated homes are the ones closing at the median. Dallas agent Douglas Newby told D Magazine in its September 21, 2026 market report that homes not updated in 15 to 30 years are harder to sell. Texas sellers' median price cut was $13,000, or 3.6% of the initial list price, in July 2026 (Texas Real Estate Research Center, Texas Housing Insight, September 2026).
Is the Zestimate a safe starting point for my DeSoto list price?
No. An online estimate does not see your kitchen, your roof or your street. Zillow publishes its own error rate for homes that are not on the market. Read the breakdown in is the Zestimate accurate for a DeSoto home, then compare it with a walk-through number.
What should a DeSoto seller do before listing?
- Pull the sold comps from the last 90 days within a mile, not the active listings.
- Compare your home with the 180 active DeSoto listings, because those are the homes your buyer will tour the same weekend.
- Walk the house with a pricing eye: roof, HVAC, paint, floors, kitchen.
- Decide on net proceeds first, then work back to a list price. If you also need to buy or build, read what a cash offer versus a listed sale nets in DeSoto.
Midlothian sellers face the same gap at a different level. The numbers are in why Midlothian homes sell below asking.
The fastest way to get a real number is a walk-through. Get your free Home Selling Score and you will see where your home sits against the current DeSoto market. For the wider picture, start at DeSoto real estate or check what your DeSoto home is worth today.
Frequently asked questions
How long does it take to sell a house in DeSoto right now?
The median was 68 days on market in September 2026, down from 78 a year earlier (NTREIS Monthly MLS Summary Report, September 2026). That is a median across all prices. Your timeline depends on price and condition.
Should I list high to leave room to negotiate?
The data points the other way. DeSoto buyers' agents see the same comps you do. A list price above the comps adds days on market, and a home that sits draws lower offers. Based on current conditions, pricing at market in week one is the stronger position.
Should I wait until spring to list?
Nobody can promise spring prices. What you can see today is that new DeSoto listings fell 14% year over year, so you compete with fewer new sellers now (NTREIS, September 2026). Run your net proceeds at today's numbers and decide from there.
Does 93.8% apply to every price range in DeSoto?
No. It is a citywide single-family average on 44 closed sales in September. A small sample moves with the mix of homes that closed, so use the direction, not the decimal.
Steven J. Thomas, Broker, Refind Realty DFW · Loan Officer, Envision Home Lenders, NMLS #689220. Steven holds a Baylor financial planning degree and has 20+ years in financial services, 14+ in Texas real estate. Market figures are based on current conditions and are not a guarantee of price, timeline or outcome. Texas Real Estate Commission Information About Brokerage Services and Consumer Protection Notice are available at trec.texas.gov.
Stay Informed With My Downloadable
Buyer and Seller guides

6 Smart Ways to Build Home Equity

7 Insider Secrets To Selling Your Home w/o a Lot of Time or Money

DFW Home Seller Negotiation Secrets

Home Appraisals Guide

Avoiding Pitfalls That Can Derail Your Home's Sale

Ultimate Guide To Buying a Home

A First Time Homebuyers Guide In DFW

Are You Ready To Buy?

25 Insider Secrets To Buying A Home

How to Improve Your Credit
Download All My Guides For Free
Steven J. Thomas
Steven J. Thomas has been in the financial services industry for the past 19 years and started my career as a Financial Planner for American Express Financial Advisors. I entered into banking with JP Morgan Chase as personal banker in 2003 and was promoted several times up to Small Business Specialist. I earned multiple Million Dollar Club awards and was ranked in the top 5 Small Business Specialist before I branched out in 2005 to start my own Financial Management Company. I ran a successful company before family circumstances lead me to Wachovia Bank in 2008 where I worked as a Senior Financial Specialist. As a Sr. Financial Specialist; I was responsible for the P & L and revenue growth of my banking center. The elimination of my role thru a bank merger lead me to BBVA Compass. I have held various leadership roles at BBVA Compass including Personal Relationship Manager, Branch Retail Executive, Workplace Solutions VP, and his current role as a Retail Manager. As the Regional Workplace Solutions VP, I was responsible for the strategic, tactical, and execution of Partnership Banking relationships, promotion and activity with corporate and non-profit companies in my footprint. I was responsible for the acquisition production for three districts, which includes 51 banking centers and over 300 employees. In May of 2014, I joined the team at Refind Realty and became one of the managing partners in mid-2015.
Wondering What Your DFW Home Could Be Worth in2026?
Get a Professional Home Valuation From A Local Market Expert
Unlock insights into potential selling prices.
Get a personalized analysis sent directly to your inbox.
Stay ahead with updates on property value fluctuations.
Benchmark your property against neighborhood listings.
Get a FREE Home Valuation And Potential Net Sheet:
I used this realtor and it was a great experience. He was patient and very helpful with our journey. He also helped us find a great lender with little hassle on the process, also got us approved for well above the market of our original home so we were able to get more house with a lower mortgage rate. So to anyone who is interested in buying a home take my advice give Steven a call. It’s worth it 😁
Bryant Loring

Steve was absolutely amazing! Everything was easy! Very professional in all aspects. Punctual, responsive, and diligent. He goes above and beyond to ensure you get to see as many homes as you’d like no matter the location. Not only was he knowledgeable about home buying, he also has a resourceful network for new home owner needs. I recommend Refind Realty to everyone!
Nicholas Bishop
I definitely recommend Steven to assist with your home buying needs. As a first time home buyer the process can be overwhelming, but as my realtor he was knowledgeable & patient while addressing my concerns and assisting me with my new home purchase. Thanks again Steven!! :-)
Gayle Mason
Ask Us Anything
Frequently Asked Questions
Why do you need a Realtor?
When buying or selling a home, there are so many options…which can also present a lot of obstacles. Laws change, forms change, and practices change all the time in the real estate industry. Because it’s our job to stay on top of those things, hiring a realtor reduces risk, and can also save you a lot of money in the long run.
When you work with me as your Realtor, you’re getting an expert who knows the area; knows how to skillfully guide your experience as a seller or buyer; can easily spot the difference between a good deal and a great deal. My job is to translate your dream into a real estate reality, and I work hard to earn and keep my business. This also means earning your trust: When you work with me, you’ll be working with a realtor who looks out for your best interests and is invested in your goals.
Which loan should you choose?
There are two different types of loans conventional loans and government-backed loans. The main difference is who insures these loans:
1 - Government-backed loans (FHA, VA and USDA):
(a) - Are, unsurprisingly, backed by the government.
(b) - Include FHA loans, VA loans, and USDA loans.
(c) - Make up less than 40 percent of the home loans generated in the U.S. each year.
2 - Conventional loans
(a) - Are not backed by the government.
(b) - Include conforming and non-conforming loans (such as jumbo loans).
(c) - Make up more than 60 percent of the loans generated in the U.S. each year.
What is the difference between FHA, VA and USDA loans?
1 - FHA LOANS:
FHA loans, which are insured by the Federal Housing Administration, are typically designed to meet the needs of first-time homebuyers with low or moderate incomes. FHA loans can be approved with a down payment of as little as 3.5 percent and a credit score as low as 580.
FHA loans are often called “helper loans,” because they give a leg up to potential borrowers who may not be able to secure one otherwise. For this reason, FHA loans have maximum lending limits, which are determined based on housing values for the county where the for-sale home is located.
Because the agency is taking on more risk by insuring FHA loans, the borrower is expected to pay mortgage insurance both at the time of closing and on a monthly basis, and the property must be owner-occupied.
2 - VA LOANS:
VA loans are backed by the Department of Veterans Affairs and they are guaranteed to qualified veterans and active-duty personnel and their spouses. VA loans can be approved with 100 percent financing, meaning VA borrowers are not required to make a down payment.
Unlike FHA loans, borrowers do not have to pay mortgage insurance on VA loans.
3 - USDA LOANS:
You may also hear about USDA loans, which are backed by the United States Department of Agriculture mortgage program. USDA loans are intended to support homeowners who purchase homes in rural and some suburban areas. USDA loans do not require a down payment and may offer lower interest rates; borrowers may have to pay a small mortgage insurance premium in order to offset the lender’s risk.
What’s a conventional loan? Understanding what it means to be conforming and non-conforming
Buyers who have a more established credit history and a larger down payment may prefer to apply for a conventional loan. These loans may offer a lower interest rate and only require the home buyer to purchase monthly mortgage insurance while the loan-to-value ratio is above a certain percentage, so a conventional loan borrower can typically save money in the long run.
Conventional loans are divided into two types: Conforming loans and non-conforming loans.
1 - CONFORMING LOANS:
Conforming loans are those that meet (or conform to) predetermined standards set by Fannie Mae and Freddie Mac — two government-sponsored institutions that buy and sell mortgages on the secondary market. By selling the loans to "Fannie and Freddie," lenders can free up their capital and return to issue more mortgages than if they had to personally back every loan that they approve.
The main standard for conforming loans is that the amount borrowed must be under a certain amount; in Alaska, a single-family home loan must be under $647,200 in order to be considered conforming.
Properties with more than one unit have higher limits.
2 - NON-CONFORMING (JUMBO) LOANS:
But what happens if a borrower wants to borrow more than the Freddie- and Fannie-approved loan amount? In this case, they would have to apply for a “jumbo loan,” which is the most common type of non-conforming loan.
Because the lender cannot resell the jumbo loan (or any non-conforming loan) to Freddie Mac or Fannie Mae, jumbo loans are considered to be riskier than a conforming loan. To protect against this risk, the bank will typically require a higher down payment; the interest rate on a jumbo loan may also be higher than if the same borrower applied for a conforming loan.
What kind of rate should you choose?
Rate types: Fixed-rate vs. adjustable-rate mortgages.
In addition to the loan type you choose, you’ll also have to determine if you want a fixed-rate mortgage or an adjustable-rate mortgage (ARM). A fixed-rate mortgage has an interest rate that does not change for the life of the loan, so it provides predictable monthly payments of principal and interest.
An adjustable-rate mortgage typically offers an initial introductory period with a low-interest rate. Once this period is over, the interest rate adjusts periodically, based on the market index. The initial interest rate on an ARM can sometimes be locked in for different periods, such as one, three, five, seven, or 10 years. Once the introductory period is over, the interest rate typically readjusts annually.
Locate Us
Site: stevenjthomas.com
Call :(972) 846-9170
Email: [email protected]
Office 128 S Cockrell Hill Rd, DeSoto, TX 75115
Refind Realty Inc · Broker of record: Natasha Martini Martinez
© Copyright 2026 | All Rights Reserved
Steven J. Thomas, Owner and Associate Broker · TREC #0657467 · NMLS #689220 · Equal Housing Opportunity
Privacy Policy | Terms of Service | Fair Housing Statement
Refind Realty Inc · 128 S Cockrell Hill Rd, DeSoto, TX 75115 · (972) 846-9170
Facebook
Instagram
X
LinkedIn
Youtube
TikTok