You're Always At Home With Refind Realty.
Serving Your DFW Real Estate Needs Since 2005.
We Help You Buy and Sell in The Greater Dallas-Fort Worth Area.
Check Out Our Social Media Channels!
Buying in DFW
Buying your first or next home should be a rewarding and exciting time in your life, and one that you look back on with fond memories.
Thinking Of selling?
The market has changed a lot and I'd love to show you the exact strategy I use to get sellers in DFW top dollar for their property.
Get Pre-Approved
Let me walk you through the entire pre-approval process so you know exactly how much home you can afford.
Sign Up For my
Email List
My emails are a great way to stay up-to-date with local news and real estate market trends, even if you're not currently in the market. So, come on and join me to stay in the loop!
affordability Calculator
Get pre-approved to know exactly how much house you can afford. Use this calculator to get a quick estimate. Contact me for assistance!
DFW New Construction
Discover the latest new home constructions in DFW and take advantage of the builder incentives that are available now.
Let's Make Your real estate Dreams Come True.
Newest Listings
Call Me Today At (972) 846-9170
Refind Realty Blog:

Are Cedar Hill, TX Home Prices Dropping?
Last updated: October 23, 2026
Are Cedar Hill, TX Home Prices Dropping?
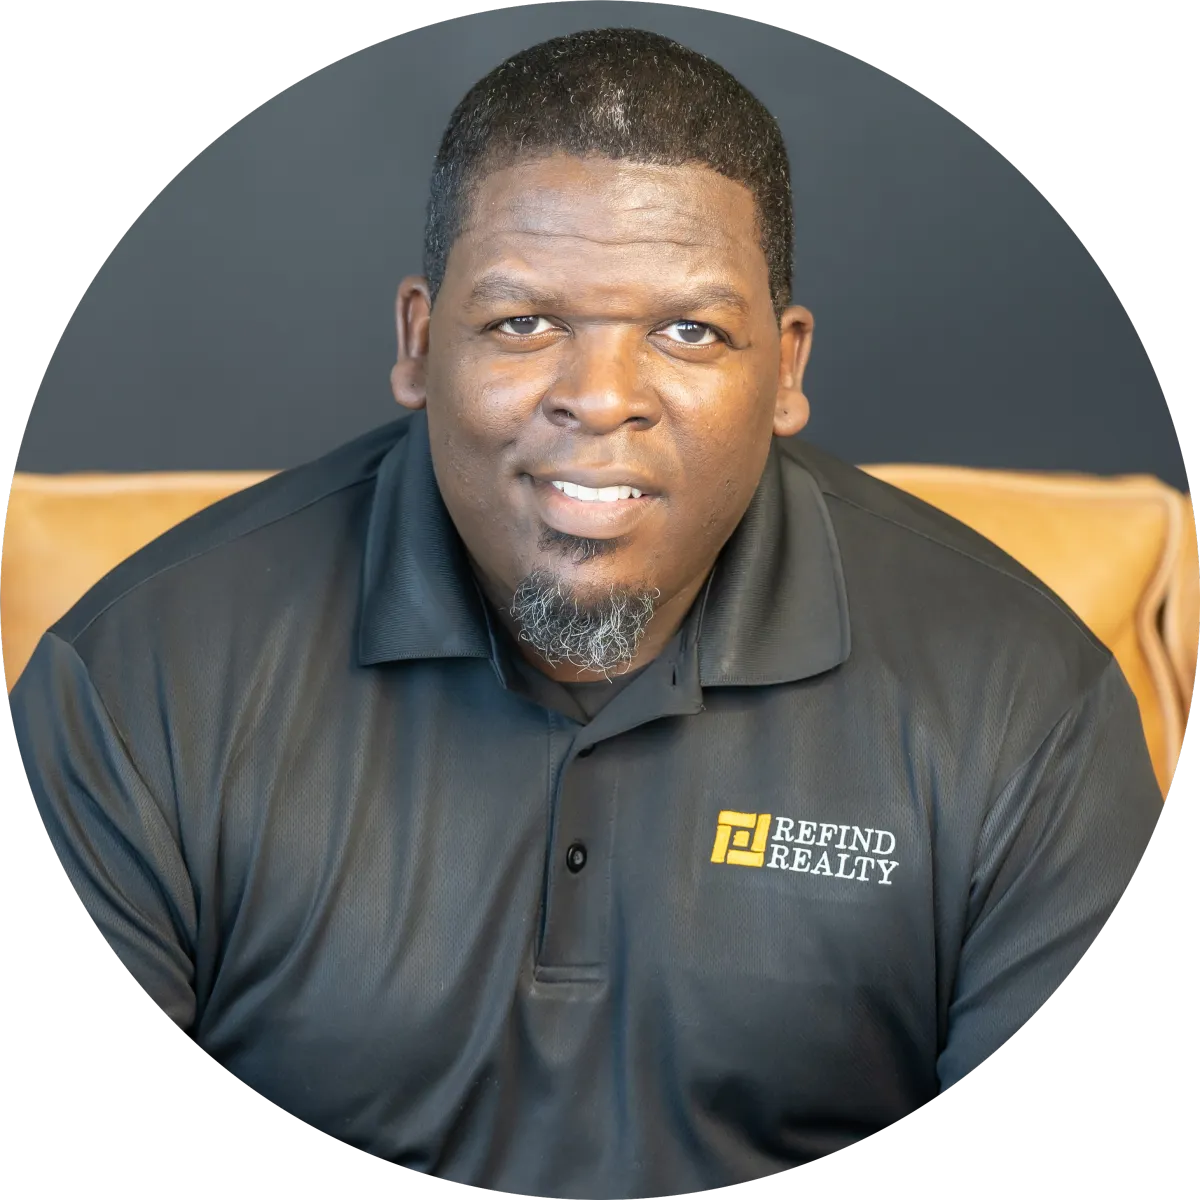
By Steven J. Thomas, Broker, Refind Realty DFW · Loan Officer, Envision Home Lending LLC, NMLS #689220. Baylor financial planning degree, 20+ years in financial services.
Yes. Cedar Hill's median sold price fell 9.3%, from $350,000 to $317,500, between September 2025 and September 2026 (NTREIS). The monthly payment did not fall with it. At today's rate, the lower-priced house costs about $32 more a month in principal and interest than last year's median did. Based on current conditions.
A 9.3% drop sounds like a discount. The loan tells a different story. Rates rose far enough in twelve months to erase the price cut, and then some. This post shows the payment math and where a Cedar Hill buyer still has room to negotiate.
How much did Cedar Hill home prices fall?
The median sold price for a Cedar Hill single-family home was $317,500 in September 2026, down $32,500 from $350,000 in September 2025 (NTREIS). City medians on 41 sales swing with the mix of homes that closed, so use the direction and not the decimal.
| Cedar Hill, single family | Sep 2026 | Sep 2025 |
|---|---|---|
| Median sold price | $317,500 | $350,000 |
| Active listings | 127 | 175 |
| Median days on market | 77 | 49 |
| Months of supply | 3.1 | 4.8 |
| Pending sales | 36 | 34 |
Source: NTREIS Monthly MLS Summary Report, September 2026.
What does a lower price do to the monthly payment?
Less than you would expect. With 20% down, last year's $350,000 median meant a $280,000 loan. At the 6.19% rate from a year ago, principal and interest was about $1,713 a month. Today's $317,500 median means a $254,000 loan. At the 7.32% Freddie Mac average on October 22, 2026, it is about $1,745.
| Loan, 30-year fixed, 20% down | Rate | P&I per month | APR |
|---|---|---|---|
| $280,000 (Sep 2025 median) | 6.19% | $1,713 | 6.27% |
| $254,000 (Sep 2026 median) | 7.32% | $1,745 | 7.41% |
| $254,000 at the old rate | 6.19% | $1,554 | 6.27% |
The rate adds about $191 a month to the same $254,000 loan. APR assumes $1,495 in lender fees, no points, 15 days of prepaid interest and no mortgage insurance. Principal and interest only, before taxes and insurance. Rate source: Freddie Mac Primary Mortgage Market Survey, October 22, 2026. Envision Home Lending LLC, NMLS #2619789.
Is Cedar Hill a buyer's market?
Cedar Hill had 3.1 months of supply in September 2026 (NTREIS), the seller-leaning edge of balanced. Active listings fell 27%, from 175 to 127. Even so, the median home took 77 days to sell, up from 49. Fewer homes are listed, and the ones that sit give buyers room to negotiate.
How much can a Cedar Hill buyer negotiate?
Cedar Hill homes closed at 95.3% of list price in September 2026 (NTREIS). A home listed at $333,200 that closes at that ratio brings $317,500, about $15,700 under ask. That is an illustration of the ratio, not a promise on any house. Homes that have sat past 60 days give you the most room, and a seller credit toward a rate buydown can lower your payment more than a small price cut.
I covered how Cedar Hill buyers turn a slow market into rate buydowns earlier this fall. If you are weighing a builder, read what new construction costs in Cedar Hill. For a neighboring town, Midlothian's price drop played out differently. The Cedar Hill, TX page shows how I work in this town.
Know your payment before you tour. Get pre-approved in minutes and see what a Cedar Hill home costs you per month at today's rate.
FAQ: buying in Cedar Hill
Should I wait for Cedar Hill prices to fall further?
Nobody can promise they will. The median fell $32,500 in a year and the payment still rose, because the rate moved 113 basis points. A further price drop would need to outrun any rate move.
Is now a good time to buy in Cedar Hill?
That depends on your budget, not the calendar. Prices are lower than last year, homes sit longer, and you can negotiate. The tradeoff is a higher rate, which you can lower with a seller credit or buydown.
How many homes are for sale in Cedar Hill?
There were 127 active single-family listings and 36 pending sales in September 2026 (NTREIS).
How long do Cedar Hill homes take to sell?
The median was 77 days on market in September 2026, up from 49 a year earlier (NTREIS). Slower sales mean more time to compare homes and make a reasoned offer.
Do Cedar Hill buyers pay less than the list price?
On average, yes. Homes closed at 95.3% of list in September 2026 (NTREIS). Individual homes vary, so a price comparison for the specific house is worth the hour.
Data sources: NTREIS Monthly MLS Summary Report, September 2026; Freddie Mac Primary Mortgage Market Survey, October 22, 2026.
Steven J. Thomas · Broker, Refind Realty DFW · TREC Broker License #0657467 · Loan Officer, Envision Home Lending LLC · NMLS #689220 · Company NMLS #2619789. Call or text 972-846-9170. Equal Housing Opportunity. Information About Brokerage Services and the Consumer Protection Notice are available at trec.texas.gov. Market data reflects current conditions and is not a guarantee of price or timeline.
Stay Informed With My Downloadable
Buyer and Seller guides

6 Smart Ways to Build Home Equity

7 Insider Secrets To Selling Your Home w/o a Lot of Time or Money

DFW Home Seller Negotiation Secrets

Home Appraisals Guide

Avoiding Pitfalls That Can Derail Your Home's Sale

Ultimate Guide To Buying a Home

A First Time Homebuyers Guide In DFW

Are You Ready To Buy?

25 Insider Secrets To Buying A Home

How to Improve Your Credit
Download All My Guides For Free
Steven J. Thomas
Steven J. Thomas has been in the financial services industry for the past 19 years and started my career as a Financial Planner for American Express Financial Advisors. I entered into banking with JP Morgan Chase as personal banker in 2003 and was promoted several times up to Small Business Specialist. I earned multiple Million Dollar Club awards and was ranked in the top 5 Small Business Specialist before I branched out in 2005 to start my own Financial Management Company. I ran a successful company before family circumstances lead me to Wachovia Bank in 2008 where I worked as a Senior Financial Specialist. As a Sr. Financial Specialist; I was responsible for the P & L and revenue growth of my banking center. The elimination of my role thru a bank merger lead me to BBVA Compass. I have held various leadership roles at BBVA Compass including Personal Relationship Manager, Branch Retail Executive, Workplace Solutions VP, and his current role as a Retail Manager. As the Regional Workplace Solutions VP, I was responsible for the strategic, tactical, and execution of Partnership Banking relationships, promotion and activity with corporate and non-profit companies in my footprint. I was responsible for the acquisition production for three districts, which includes 51 banking centers and over 300 employees. In May of 2014, I joined the team at Refind Realty and became one of the managing partners in mid-2015.
Wondering What Your DFW Home Could Be Worth in2026?
Get a Professional Home Valuation From A Local Market Expert
Unlock insights into potential selling prices.
Get a personalized analysis sent directly to your inbox.
Stay ahead with updates on property value fluctuations.
Benchmark your property against neighborhood listings.
Get a FREE Home Valuation And Potential Net Sheet:
I used this realtor and it was a great experience. He was patient and very helpful with our journey. He also helped us find a great lender with little hassle on the process, also got us approved for well above the market of our original home so we were able to get more house with a lower mortgage rate. So to anyone who is interested in buying a home take my advice give Steven a call. It’s worth it 😁
Bryant Loring

Steve was absolutely amazing! Everything was easy! Very professional in all aspects. Punctual, responsive, and diligent. He goes above and beyond to ensure you get to see as many homes as you’d like no matter the location. Not only was he knowledgeable about home buying, he also has a resourceful network for new home owner needs. I recommend Refind Realty to everyone!
Nicholas Bishop
I definitely recommend Steven to assist with your home buying needs. As a first time home buyer the process can be overwhelming, but as my realtor he was knowledgeable & patient while addressing my concerns and assisting me with my new home purchase. Thanks again Steven!! :-)
Gayle Mason
Ask Us Anything
Frequently Asked Questions
Why do you need a Realtor?
When buying or selling a home, there are so many options…which can also present a lot of obstacles. Laws change, forms change, and practices change all the time in the real estate industry. Because it’s our job to stay on top of those things, hiring a realtor reduces risk, and can also save you a lot of money in the long run.
When you work with me as your Realtor, you’re getting an expert who knows the area; knows how to skillfully guide your experience as a seller or buyer; can easily spot the difference between a good deal and a great deal. My job is to translate your dream into a real estate reality, and I work hard to earn and keep my business. This also means earning your trust: When you work with me, you’ll be working with a realtor who looks out for your best interests and is invested in your goals.
Which loan should you choose?
There are two different types of loans conventional loans and government-backed loans. The main difference is who insures these loans:
1 - Government-backed loans (FHA, VA and USDA):
(a) - Are, unsurprisingly, backed by the government.
(b) - Include FHA loans, VA loans, and USDA loans.
(c) - Make up less than 40 percent of the home loans generated in the U.S. each year.
2 - Conventional loans
(a) - Are not backed by the government.
(b) - Include conforming and non-conforming loans (such as jumbo loans).
(c) - Make up more than 60 percent of the loans generated in the U.S. each year.
What is the difference between FHA, VA and USDA loans?
1 - FHA LOANS:
FHA loans, which are insured by the Federal Housing Administration, are typically designed to meet the needs of first-time homebuyers with low or moderate incomes. FHA loans can be approved with a down payment of as little as 3.5 percent and a credit score as low as 580.
FHA loans are often called “helper loans,” because they give a leg up to potential borrowers who may not be able to secure one otherwise. For this reason, FHA loans have maximum lending limits, which are determined based on housing values for the county where the for-sale home is located.
Because the agency is taking on more risk by insuring FHA loans, the borrower is expected to pay mortgage insurance both at the time of closing and on a monthly basis, and the property must be owner-occupied.
2 - VA LOANS:
VA loans are backed by the Department of Veterans Affairs and they are guaranteed to qualified veterans and active-duty personnel and their spouses. VA loans can be approved with 100 percent financing, meaning VA borrowers are not required to make a down payment.
Unlike FHA loans, borrowers do not have to pay mortgage insurance on VA loans.
3 - USDA LOANS:
You may also hear about USDA loans, which are backed by the United States Department of Agriculture mortgage program. USDA loans are intended to support homeowners who purchase homes in rural and some suburban areas. USDA loans do not require a down payment and may offer lower interest rates; borrowers may have to pay a small mortgage insurance premium in order to offset the lender’s risk.
What’s a conventional loan? Understanding what it means to be conforming and non-conforming
Buyers who have a more established credit history and a larger down payment may prefer to apply for a conventional loan. These loans may offer a lower interest rate and only require the home buyer to purchase monthly mortgage insurance while the loan-to-value ratio is above a certain percentage, so a conventional loan borrower can typically save money in the long run.
Conventional loans are divided into two types: Conforming loans and non-conforming loans.
1 - CONFORMING LOANS:
Conforming loans are those that meet (or conform to) predetermined standards set by Fannie Mae and Freddie Mac — two government-sponsored institutions that buy and sell mortgages on the secondary market. By selling the loans to "Fannie and Freddie," lenders can free up their capital and return to issue more mortgages than if they had to personally back every loan that they approve.
The main standard for conforming loans is that the amount borrowed must be under a certain amount; in Alaska, a single-family home loan must be under $647,200 in order to be considered conforming.
Properties with more than one unit have higher limits.
2 - NON-CONFORMING (JUMBO) LOANS:
But what happens if a borrower wants to borrow more than the Freddie- and Fannie-approved loan amount? In this case, they would have to apply for a “jumbo loan,” which is the most common type of non-conforming loan.
Because the lender cannot resell the jumbo loan (or any non-conforming loan) to Freddie Mac or Fannie Mae, jumbo loans are considered to be riskier than a conforming loan. To protect against this risk, the bank will typically require a higher down payment; the interest rate on a jumbo loan may also be higher than if the same borrower applied for a conforming loan.
What kind of rate should you choose?
Rate types: Fixed-rate vs. adjustable-rate mortgages.
In addition to the loan type you choose, you’ll also have to determine if you want a fixed-rate mortgage or an adjustable-rate mortgage (ARM). A fixed-rate mortgage has an interest rate that does not change for the life of the loan, so it provides predictable monthly payments of principal and interest.
An adjustable-rate mortgage typically offers an initial introductory period with a low-interest rate. Once this period is over, the interest rate adjusts periodically, based on the market index. The initial interest rate on an ARM can sometimes be locked in for different periods, such as one, three, five, seven, or 10 years. Once the introductory period is over, the interest rate typically readjusts annually.
Locate Us
Site: www.stevenjthomas.com
Call :(972) 846-9170
Email: [email protected]
Office 128 S. Cockrell Hill Rd, DeSoto TX 75115
Owned and Operated by Thomas & Thomas Financial Group, LLC
© Copyright 2026 | All Rights Reserved
Steven J. Thomas, REALTOR® · TREC License #0657467
Privacy Policy | Terms of Service | Fair Housing Statement
Refind Realty DFW · 128 S. Cockrell Hill Rd, DeSoto, TX 75115 · (972) 846-9170
Facebook
Instagram
X
LinkedIn
Youtube
TikTok