You're Always At Home With Refind Realty.
Serving Your DFW Real Estate Needs Since 2005.
We Help You Buy and Sell in The Greater Dallas-Fort Worth Area.
Check Out Our Social Media Channels!
Buying in DFW
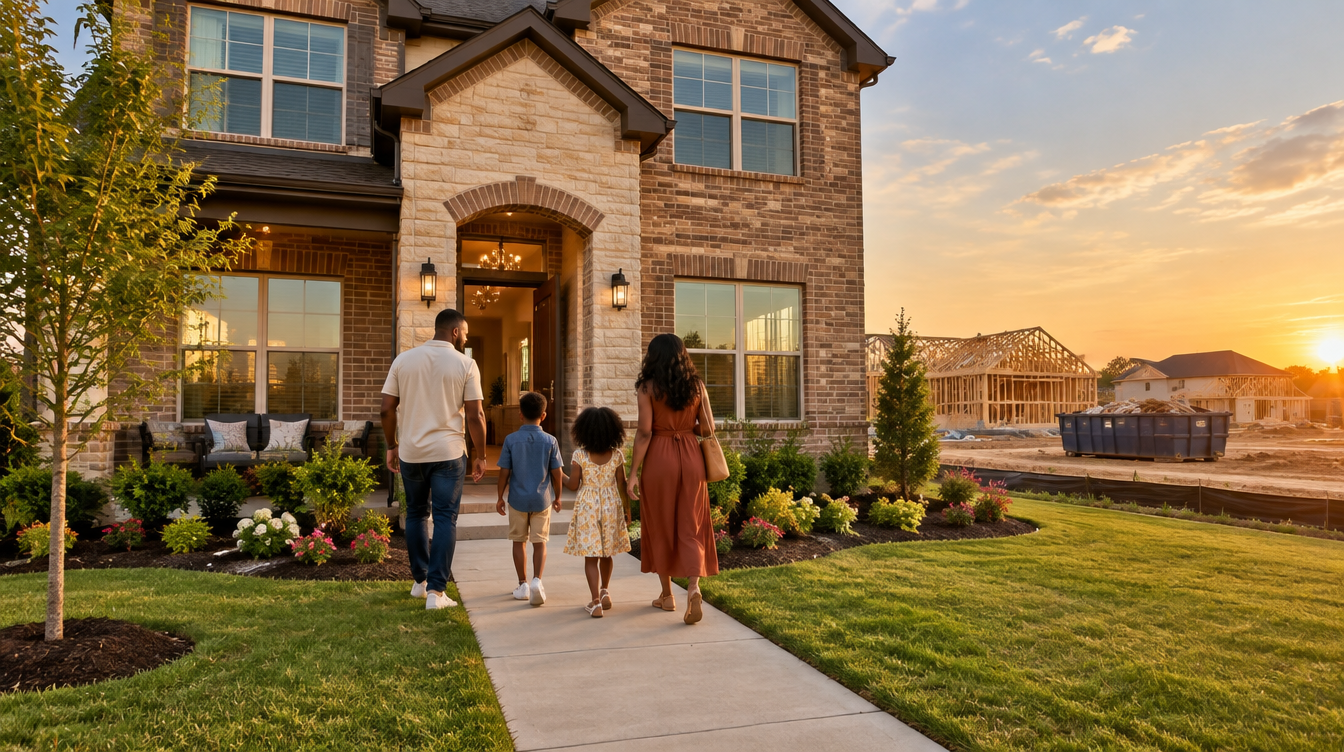
Buying your first or next home should be a rewarding and exciting time in your life, and one that you look back on with fond memories.
Thinking Of selling?
The market has changed a lot and I'd love to show you the exact strategy I use to get sellers in DFW top dollar for their property.
Get Pre-Approved
Let me walk you through the entire pre-approval process so you know exactly how much home you can afford.
Sign Up For my
Email List
My emails are a great way to stay up-to-date with local news and real estate market trends, even if you're not currently in the market. So, come on and join me to stay in the loop!
affordability Calculator
Get pre-approved to know exactly how much house you can afford. Use this calculator to get a quick estimate. Contact me for assistance!
DFW New Construction
Discover the latest new home constructions in DFW and take advantage of the builder incentives that are available now.
Let's Make Your real estate Dreams Come True.
Newest Listings
Call Me Today At (972) 846-9170
Refind Realty Blog:
Buying the Builder's Model Home in Glenn Heights: Leaseback, Upgrades, and What It Should Cost You (2026)
Buying the Builder's Model Home in Glenn Heights: Leaseback, Upgrades, and What It Should Cost You (2026)
By Steven J. Thomas
Every new construction community in Glenn Heights has one house that is not for sale until it is. The model. It has the upgraded kitchen, the designer paint, the finished backyard, and a few thousand pairs of shoes that have walked through it. As subdivisions off Bear Creek Road and Hampton Road move toward close-out this fall, some of those models are going to hit the market, and the builder rep will pitch it as the best deal in the neighborhood. Sometimes it is. But the rep works for the builder, and the way a model home sale is structured decides whether you got a discount or bought a house with 18 months of wear and a warranty that started before you ever saw it.
Direct Answer
A builder's model home in Glenn Heights can be a good buy if you measure the price against a comparable finished home with the same upgrades, not the community's base price, and if the contract states when the warranty starts, what furniture and fixtures convey, and who pays for wear repairs. If the builder wants a leaseback, treat it as a landlord decision with its own financing rules. Map the whole purchase with the HomeSwap New Construction Plan before you sign.
Neighborhood Spotlights: Where Glenn Heights Models Sit in 2026
Hampton Park
Bloomfield Homes' Hampton Park is the community most Glenn Heights buyers ask me about, with plans listed from roughly $379,990 and larger inventory homes into the $500,000s as of September 2026 listing data. Bloomfield models are heavy on upgraded stone, cabinetry, and built-ins, which is exactly the kind of package that makes a model look expensive against the base price and cheap against a comparable spec. Before you get excited about any model here, pull the community's recent closed prices through the neighborhood reports so the comparison is real.
Stewart Farms
Starlight Homes' Stewart Farms is the entry point for Glenn Heights new construction, with homes listed from about $307,990 and 1,536 to 2,717 square feet per September 2026 listings. Entry-level models carry fewer dollar upgrades, so the price gap between the model and a regular spec is smaller. The bigger issue here is traffic wear, because a high-volume community runs a lot of people through one house. Look at the DFW new construction hub for what similar Starlight specs are closing at nearby.
Hampton Park Estates and the Ovilla Line
Kindred Homes' Hampton Park Estates and First Texas Homes' Broadmoor Estates just across the Ovilla line run from the high $500,000s to over $700,000. Models in this price band can carry $100,000 or more in options, outdoor living, and landscaping. That is where a model purchase can make the most sense, if the leaseback terms and warranty are handled right. Pro tip: before you commit to any new build in this range, get the Home Selling Score on the house you are leaving, because the sale of that home funds this one.
Local Market Trends (Fall 2026)
- Glenn Heights active builders and average list prices: Bloomfield about $468,240, First Texas about $465,125, D.R. Horton about $387,990, Starlight about $357,990 (Homes.com new-home listings, September 2026).
- Dallas-Fort Worth median list price: $425,000 in August 2026, down 1.2% year over year, 58 days on market (Realtor.com, September 2026).
- DFW new-construction inventory: about 4.5 months of supply in August 2026, with resale inventory nearly 19% below last August (NTREIS-based reporting, September 2026).
- 30-year fixed rate: 6.76% national average for the week of September 10, 2026 (Freddie Mac PMMS).
The number that matters for a model-home buyer is the 4.5 months of new-build supply. Builders sitting on finished inventory are motivated to clear it, and the model is the last piece of inventory in a community. That motivation is real, but it does not mean the model is priced below its comparable. It means the builder is willing to talk. Sources: Homes.com Glenn Heights new homes, Realtor.com Dallas August 2026, Freddie Mac PMMS.
Cost Breakdown for a Glenn Heights Model Home Buyer
Here is a composite example, not a specific listing. A Glenn Heights builder lists its 2,900-square-foot model at $489,900. The same plan as a bare spec would be $415,000, and the options in the model (upgraded cabinets and counters, wood floors, a covered patio with an outdoor kitchen, full landscaping and irrigation, window treatments, and smart-home wiring) would price out around $105,000 on a new order. Against the base price, the model looks $75,000 expensive. Against the finished comparable at $520,000, it is about 6% under.
Now the carry. With 10% down, the loan is $440,910. At an illustrative 6.75% rate (estimated APR 6.95%), principal and interest run about $2,860 a month. Add roughly $940 a month in property taxes at a combined rate near 2.3% (verify by parcel, and note you cannot file a homestead exemption until you occupy the home on January 1), about $300 for insurance, and $60 in HOA dues. Call it $4,160 a month.
- Model price: $489,900 (about 6% under a comparable finished home at $520,000)
- Included options: about $105,000 at builder option pricing
- Estimated monthly payment at 10% down: about $4,160
- Builder leaseback rent at a 6% annualized yield: about $2,450 a month
- Your net carry during the leaseback: about $1,710 a month
- Post-vacancy repair reserve to negotiate: $5,000 to $10,000
The leaseback math is where people fool themselves. The builder's rent covers a little more than half of your payment in this example. You are still paying $1,700 a month to own a house you cannot live in yet, and you are also paying for wherever you live now. Over a 12-month leaseback that is more than $20,000 out of pocket, which is most of the discount. The return on a model home comes from the upgrades and the finished yard, not from the rent check.
Builder and Community Insights: Know the Competition
D.R. Horton, Pulte, and Beazer close a fiscal reporting period on September 30, and DFW builders have been running rate buydowns and flex-cash promotions to clear inventory before then. A model home is often excluded from those promotions because it is sold "as is, as shown." Ask anyway. If the builder will not apply the incentive to the model, that is a negotiating point on price or on the repair reserve. And remember that whoever represents you on a new build in Glenn Heights, the builder pays that agent, so bring your own. The New Construction Rebate Program returns up to 1% at closing when you use my team, and that applies to a model purchase the same as any other new build.
The Six Things That Have to Be in Writing
Every one of these has cost a model-home buyer money somewhere in DFW. None of them are in the builder's standard contract unless you put them there.
- Warranty start date. The builder's 1-2-10 warranty may run from the certificate of occupancy, which could be 18 months before your closing. Ask for the clock to reset at closing or for a written statement of what remains.
- Furniture and fixtures inventory. Model furniture is usually excluded. Mirrors, drapes, light fixtures, and the outdoor kitchen appliances are the gray area. List every item by room.
- Leaseback terms. Rent amount, term, deposit, who pays taxes, insurance, utilities, lawn care, a hard move-out date, and a penalty if the builder leaves early or stays late.
- Post-vacancy inspection. An independent inspection after the furniture is out and before you take possession, with a repair escrow or punch-list obligation for what it finds.
- Sales-office conversion. The garage of many models is finished as an office. The contract should require the builder to convert it back to a working garage with a door and opener, or price the home as if it will not.
- Occupancy classification. If there is a leaseback, your lender has to approve it. A long leaseback can push the loan from primary residence to investment terms, which changes the rate and the down payment.
Financing and Incentives That Attract Buyers
A model home with a leaseback is the one new construction purchase where the lender needs to be in the room early. Owner-occupied financing requires you to intend to occupy within a set window, usually 60 days after closing. A six-month leaseback can be workable with the right lender and documentation. A 24-month leaseback usually cannot be, and the honest answer is that the loan becomes an investment loan with a higher rate and a bigger down payment. Do not let anyone talk you into calling it a primary residence when the lease says otherwise.
Without a leaseback, a close-out model is financed like any other completed spec home, and it appraises on the same basis. That is the cleaner path for most Glenn Heights buyers, and it is the one I steer people toward unless the leaseback rent and the discount together clearly beat a comparable spec. Since I am the loan officer as well as the broker, the pre-approval and the contract terms get written to match each other from day one. Get pre-approved before you tour the model, so the rep knows you are a real buyer and you know your real payment.
Conclusion
A Glenn Heights model home is worth a serious look this fall, especially in a community that is closing out and in a price band where the upgrades are real money. Judge it against the finished comparable, not the base price. Put the warranty date, the inventory, the leaseback terms, the post-vacancy inspection, and the garage conversion in writing. And if the builder wants a leaseback, run the carry cost against the discount before you decide the rent check makes it a deal. I look at the whole picture, the house you are selling, the loan, and the timing, before I tell you a model is the right move.
Map your sell-and-build plan and we will price the model against the alternatives.
Book a 15-minute call if you already have a model in mind.
Download the Lone Star Living app to track Glenn Heights new construction closings as communities sell out.
You're Always Home with Steven J. Thomas.
Key Takeaways
- Compare a model home to a comparable finished home with the same options, not to the community's base price.
- Builder leaseback rent typically covers only part of your payment; in a $489,900 example the net carry runs about $1,700 a month.
- The 1-2-10 warranty may have started at the certificate of occupancy, long before your closing. Get the date in writing.
- A long leaseback can turn your loan into an investment loan. Bring the lender in before you sign.
- Glenn Heights new construction runs from about $307,990 at Stewart Farms to over $700,000 at Hampton Park Estates, per September 2026 listings.
FAQ: Buying a Builder Model Home in Glenn Heights
When do builders sell their model homes in Glenn Heights?
Usually at community close-out, when only a handful of lots remain, or earlier through a sale-leaseback where the builder keeps using it as a sales office. Ask the sales manager for the remaining lot count and the expected model sale date in writing.
How much cheaper is a model home than a regular new build?
There is no standard discount. Close-out models often land 5% to 15% under a comparable finished home; leaseback models often carry a smaller discount because the upgrades and landscaping are already priced in. Measure against the finished comparable.
What is the biggest risk in buying a model home?
Wear and an unclear warranty. Thousands of visitors walked through it, and the builder's warranty clock may have started at completion. An independent post-vacancy inspection and a written warranty start date are the two protections that matter most.
Which builders have model homes in Glenn Heights right now?
Bloomfield Homes (Hampton Park, Maplewood), Starlight Homes (Stewart Farms), Kindred Homes (Hampton Park Estates), and D.R. Horton are active in Glenn Heights per September 2026 listings. Whether a specific model is for sale changes month to month, so confirm with the builder.
How long does a model home leaseback usually last?
Commonly 3 to 12 months, sometimes 18 to 24 in a slower community. The longer the term, the more likely your lender treats the purchase as an investment property.
Where can I see new construction homes and models for sale in Glenn Heights?
Builder inventory changes weekly. Download the Lone Star Living app for live Glenn Heights new construction listings and sold prices.
Steven J. Thomas · Broker, Refind Realty DFW · TREC Broker License #0657467 · Loan Officer, Envision Home Lenders · NMLS #689220 · 972-846-9170 · Equal Housing Opportunity. Payment example is illustrative, based on current conditions, and not a loan offer or commitment to lend. Rates, taxes, and builder pricing change; verify all figures before contracting.
Stay Informed With My Downloadable
Buyer and Seller guides

6 Smart Ways to Build Home Equity

7 Insider Secrets To Selling Your Home w/o a Lot of Time or Money

DFW Home Seller Negotiation Secrets

Home Appraisals Guide

Avoiding Pitfalls That Can Derail Your Home's Sale

Ultimate Guide To Buying a Home

A First Time Homebuyers Guide In DFW

Are You Ready To Buy?

25 Insider Secrets To Buying A Home

How to Improve Your Credit
Download All My Guides For Free
Steven J. Thomas
Steven J. Thomas has been in the financial services industry for the past 19 years and started my career as a Financial Planner for American Express Financial Advisors. I entered into banking with JP Morgan Chase as personal banker in 2003 and was promoted several times up to Small Business Specialist. I earned multiple Million Dollar Club awards and was ranked in the top 5 Small Business Specialist before I branched out in 2005 to start my own Financial Management Company. I ran a successful company before family circumstances lead me to Wachovia Bank in 2008 where I worked as a Senior Financial Specialist. As a Sr. Financial Specialist; I was responsible for the P & L and revenue growth of my banking center. The elimination of my role thru a bank merger lead me to BBVA Compass. I have held various leadership roles at BBVA Compass including Personal Relationship Manager, Branch Retail Executive, Workplace Solutions VP, and his current role as a Retail Manager. As the Regional Workplace Solutions VP, I was responsible for the strategic, tactical, and execution of Partnership Banking relationships, promotion and activity with corporate and non-profit companies in my footprint. I was responsible for the acquisition production for three districts, which includes 51 banking centers and over 300 employees. In May of 2014, I joined the team at Refind Realty and became one of the managing partners in mid-2015.
Wondering What Your DFW Home Could Be Worth in2026?
Get a Professional Home Valuation From A Local Market Expert
Unlock insights into potential selling prices.
Get a personalized analysis sent directly to your inbox.
Stay ahead with updates on property value fluctuations.
Benchmark your property against neighborhood listings.
Get a FREE Home Valuation And Potential Net Sheet:
I used this realtor and it was a great experience. He was patient and very helpful with our journey. He also helped us find a great lender with little hassle on the process, also got us approved for well above the market of our original home so we were able to get more house with a lower mortgage rate. So to anyone who is interested in buying a home take my advice give Steven a call. It’s worth it 😁
Bryant Loring

Steve was absolutely amazing! Everything was easy! Very professional in all aspects. Punctual, responsive, and diligent. He goes above and beyond to ensure you get to see as many homes as you’d like no matter the location. Not only was he knowledgeable about home buying, he also has a resourceful network for new home owner needs. I recommend Refind Realty to everyone!
Nicholas Bishop
I definitely recommend Steven to assist with your home buying needs. As a first time home buyer the process can be overwhelming, but as my realtor he was knowledgeable & patient while addressing my concerns and assisting me with my new home purchase. Thanks again Steven!! :-)
Gayle Mason
Ask Us Anything
Frequently Asked Questions
Why do you need a Realtor?
When buying or selling a home, there are so many options…which can also present a lot of obstacles. Laws change, forms change, and practices change all the time in the real estate industry. Because it’s our job to stay on top of those things, hiring a realtor reduces risk, and can also save you a lot of money in the long run.
When you work with me as your Realtor, you’re getting an expert who knows the area; knows how to skillfully guide your experience as a seller or buyer; can easily spot the difference between a good deal and a great deal. My job is to translate your dream into a real estate reality, and I work hard to earn and keep my business. This also means earning your trust: When you work with me, you’ll be working with a realtor who looks out for your best interests and is invested in your goals.
Which loan should you choose?
There are two different types of loans conventional loans and government-backed loans. The main difference is who insures these loans:
1 - Government-backed loans (FHA, VA and USDA):
(a) - Are, unsurprisingly, backed by the government.
(b) - Include FHA loans, VA loans, and USDA loans.
(c) - Make up less than 40 percent of the home loans generated in the U.S. each year.
2 - Conventional loans
(a) - Are not backed by the government.
(b) - Include conforming and non-conforming loans (such as jumbo loans).
(c) - Make up more than 60 percent of the loans generated in the U.S. each year.
What is the difference between FHA, VA and USDA loans?
1 - FHA LOANS:
FHA loans, which are insured by the Federal Housing Administration, are typically designed to meet the needs of first-time homebuyers with low or moderate incomes. FHA loans can be approved with a down payment of as little as 3.5 percent and a credit score as low as 580.
FHA loans are often called “helper loans,” because they give a leg up to potential borrowers who may not be able to secure one otherwise. For this reason, FHA loans have maximum lending limits, which are determined based on housing values for the county where the for-sale home is located.
Because the agency is taking on more risk by insuring FHA loans, the borrower is expected to pay mortgage insurance both at the time of closing and on a monthly basis, and the property must be owner-occupied.
2 - VA LOANS:
VA loans are backed by the Department of Veterans Affairs and they are guaranteed to qualified veterans and active-duty personnel and their spouses. VA loans can be approved with 100 percent financing, meaning VA borrowers are not required to make a down payment.
Unlike FHA loans, borrowers do not have to pay mortgage insurance on VA loans.
3 - USDA LOANS:
You may also hear about USDA loans, which are backed by the United States Department of Agriculture mortgage program. USDA loans are intended to support homeowners who purchase homes in rural and some suburban areas. USDA loans do not require a down payment and may offer lower interest rates; borrowers may have to pay a small mortgage insurance premium in order to offset the lender’s risk.
What’s a conventional loan? Understanding what it means to be conforming and non-conforming
Buyers who have a more established credit history and a larger down payment may prefer to apply for a conventional loan. These loans may offer a lower interest rate and only require the home buyer to purchase monthly mortgage insurance while the loan-to-value ratio is above a certain percentage, so a conventional loan borrower can typically save money in the long run.
Conventional loans are divided into two types: Conforming loans and non-conforming loans.
1 - CONFORMING LOANS:
Conforming loans are those that meet (or conform to) predetermined standards set by Fannie Mae and Freddie Mac — two government-sponsored institutions that buy and sell mortgages on the secondary market. By selling the loans to "Fannie and Freddie," lenders can free up their capital and return to issue more mortgages than if they had to personally back every loan that they approve.
The main standard for conforming loans is that the amount borrowed must be under a certain amount; in Alaska, a single-family home loan must be under $647,200 in order to be considered conforming.
Properties with more than one unit have higher limits.
2 - NON-CONFORMING (JUMBO) LOANS:
But what happens if a borrower wants to borrow more than the Freddie- and Fannie-approved loan amount? In this case, they would have to apply for a “jumbo loan,” which is the most common type of non-conforming loan.
Because the lender cannot resell the jumbo loan (or any non-conforming loan) to Freddie Mac or Fannie Mae, jumbo loans are considered to be riskier than a conforming loan. To protect against this risk, the bank will typically require a higher down payment; the interest rate on a jumbo loan may also be higher than if the same borrower applied for a conforming loan.
What kind of rate should you choose?
Rate types: Fixed-rate vs. adjustable-rate mortgages.
In addition to the loan type you choose, you’ll also have to determine if you want a fixed-rate mortgage or an adjustable-rate mortgage (ARM). A fixed-rate mortgage has an interest rate that does not change for the life of the loan, so it provides predictable monthly payments of principal and interest.
An adjustable-rate mortgage typically offers an initial introductory period with a low-interest rate. Once this period is over, the interest rate adjusts periodically, based on the market index. The initial interest rate on an ARM can sometimes be locked in for different periods, such as one, three, five, seven, or 10 years. Once the introductory period is over, the interest rate typically readjusts annually.
Locate Us
Site: www.stevenjthomas.com
Call :(972) 846-9170
Email: [email protected]
Office 128 S. Cockrell Hill Rd, DeSoto TX 75115
Owned and Operated by Thomas & Thomas Financial Group, LLC
© Copyright 2026 | All Rights Reserved
Steven J. Thomas, REALTOR® · TREC License #0657467
Privacy Policy | Terms of Service | Fair Housing Statement
Refind Realty DFW · 128 S. Cockrell Hill Rd, DeSoto, TX 75115 · (972) 846-9170
Facebook
Instagram
X
LinkedIn
Youtube
TikTok