You're Always At Home With Refind Realty.
Serving Your DFW Real Estate Needs Since 2005.
We Help You Buy and Sell in The Greater Dallas-Fort Worth Area.
Check Out Our Social Media Channels!
Buying in DFW
Buying your first or next home should be a rewarding and exciting time in your life, and one that you look back on with fond memories.
Thinking Of selling?
The market has changed a lot and I'd love to show you the exact strategy I use to get sellers in DFW top dollar for their property.
Get Pre-Approved
Let me walk you through the entire pre-approval process so you know exactly how much home you can afford.
Sign Up For my
Email List
My emails are a great way to stay up-to-date with local news and real estate market trends, even if you're not currently in the market. So, come on and join me to stay in the loop!
affordability Calculator
Get pre-approved to know exactly how much house you can afford. Use this calculator to get a quick estimate. Contact me for assistance!
DFW New Construction
Discover the latest new home constructions in DFW and take advantage of the builder incentives that are available now.
Let's Make Your real estate Dreams Come True.
Newest Listings
Call Me Today At (972) 846-9170
Refind Realty Blog:
Marry the House, Date the Rate: The Honest Refinance Math for Red Oak, TX Buyers
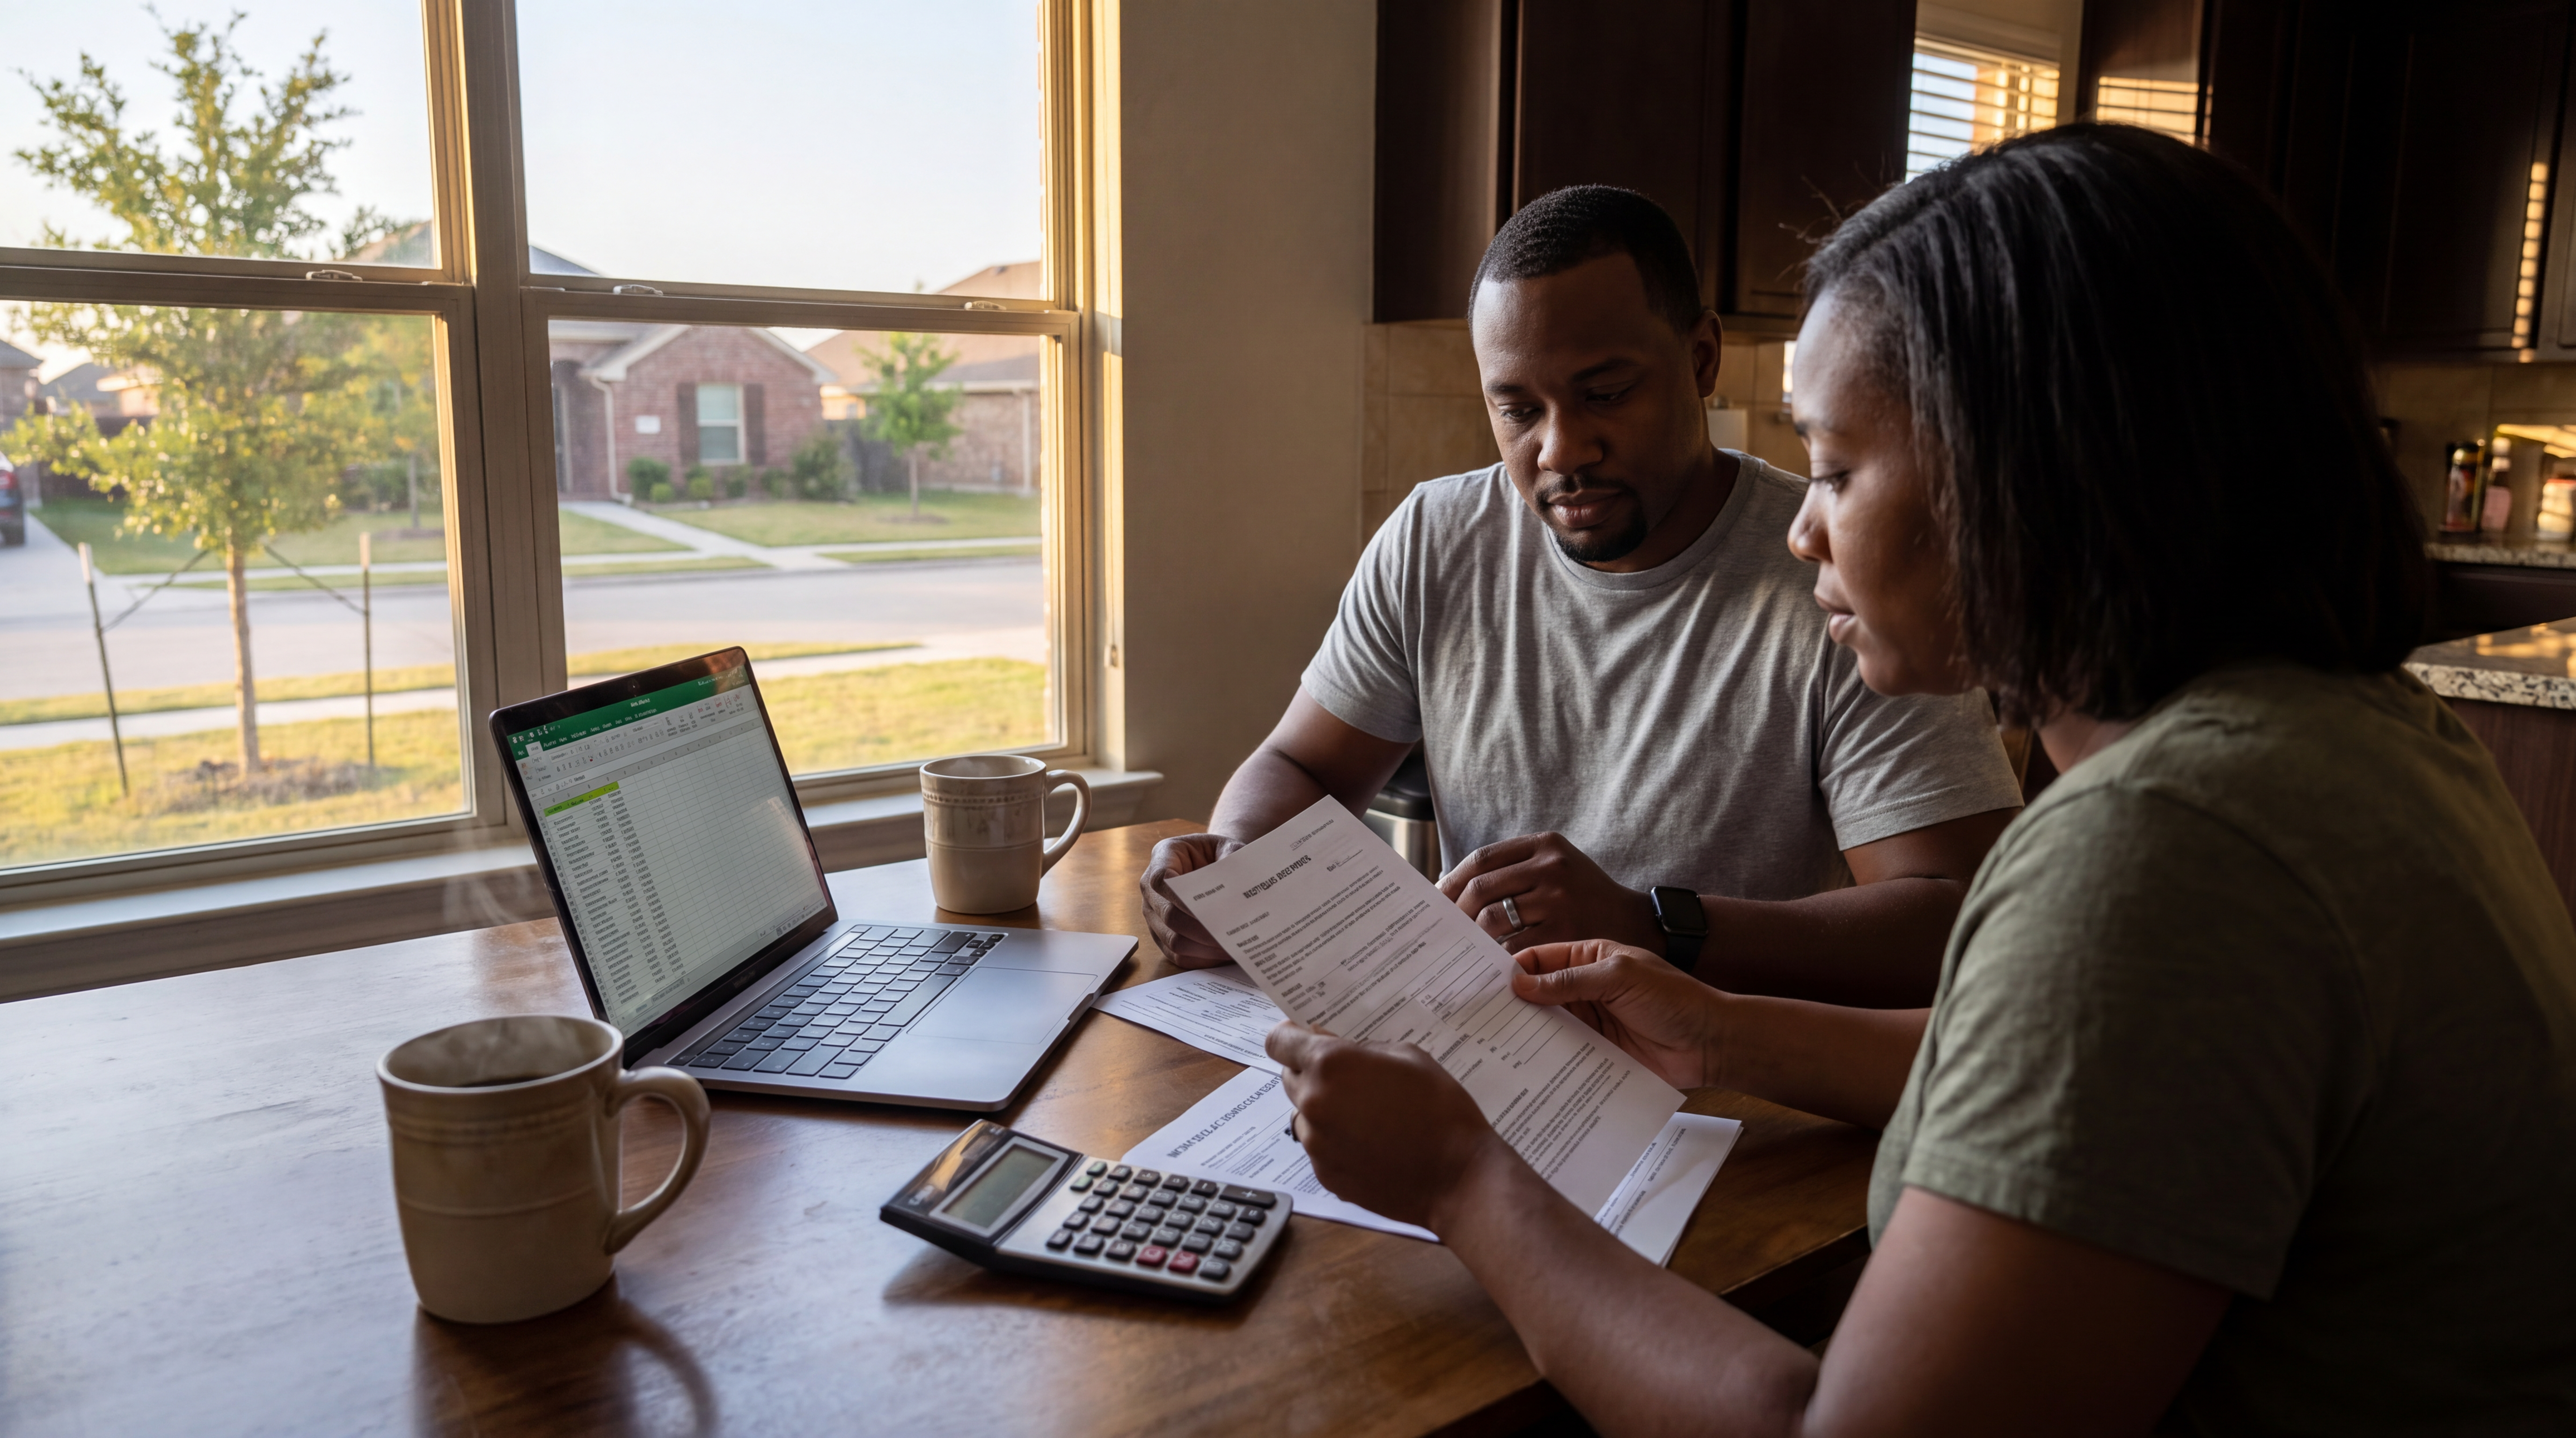
You have heard the line. Marry the house, date the rate. Buy now at 7 percent, refinance later when rates come down, and everything works out. It gets repeated at open houses all over Red Oak and the rest of southwest DFW, and almost nobody who says it does the arithmetic out loud. So let's do it. I am licensed on both sides of this deal, real estate and mortgage, so I am going to walk you through what a Texas refinance actually costs, how to find the month it starts paying you back, and what it means that the Fed just moved the wrong direction.
The short answer
A refinance pays off when your closing costs divided by your monthly payment savings lands inside the time you plan to keep the loan. On a typical Red Oak loan near $336,000, roughly $6,500 in Texas refinance costs and a drop from 7 percent to 6 percent produce about $263 a month in savings and a break-even around month 25. Smaller rate drops push that break-even past three years.
Where rates actually stand as of September 2026
Two things happened in the same week, and they point in opposite directions from what most buyers expected.
- The Federal Open Market Committee raised the federal funds target by 25 basis points to 3.75 percent to 4.00 percent at its September 16 to 17, 2026 meeting. The vote was 12 to 0, and it is the first increase since 2023. (Source: CNBC, September 16, 2026 — Fed rate decision coverage)
- The 30-year fixed-rate mortgage averaged 6.95 percent for the week ending September 17, 2026, up from 6.76 percent the prior week and 6.26 percent a year earlier. (Source: Freddie Mac Primary Mortgage Market Survey, September 17, 2026)
The Fed funds rate and your mortgage rate are not the same thing. The Fed sets an overnight bank rate. Your 30-year fixed rate follows the mortgage bond market, which trades on inflation expectations. They move in loose company, not lockstep. But a hike after three-plus years of cuts and holds tells you something real about the direction of the conversation, and the survey rate moving 19 basis points in a single week tells you the bond market heard it.
Here is the part that matters for the advice you keep hearing. "Date the rate" is a plan that depends on a future you cannot see. Nobody at any brokerage or any lender, including me, can tell you when the 30-year fixed will fall, how far it will fall, or whether it will fall at all. Anyone who gives you a date is guessing. What you can do is price the plan honestly and then decide whether you still want it.
What a refinance actually costs in Texas
A refinance is a whole new loan. You are not adjusting a number on an existing note. You are originating, underwriting, appraising, insuring, and recording a mortgage from scratch, and you pay for every one of those steps again.
Here is the typical range on a Texas rate-and-term refinance in the $300,000 to $400,000 loan size, based on current published cost ranges and what I see on real closing disclosures:
- Lender fees (origination, underwriting, processing): $1,000 to $2,500
- Appraisal: $500 to $800, sometimes waived by automated underwriting on a clean file
- Title insurance and title services: $1,500 to $2,500 on a Texas refinance policy, plus endorsements
- Survey: $0 to $600, depending on whether your existing survey can be reused with a T-47 affidavit
- Recording and county fees: $100 to $200
- Credit, flood cert, tax service, courier: $150 to $400
That lands most Texas refinances between roughly 2 and 4 percent of the loan amount. Published national ranges put refinance closing costs at 2 to 5 percent of the loan. (Sources: The Mortgage Reports and Rocket Mortgage closing-cost guides, accessed September 21, 2026.) For this article I am going to use $6,500 as the working number on a loan near $330,000, which is a realistic middle.
The escrow line nobody warns you about
Your new lender sets up a fresh escrow account and requires you to fund it at closing. In Ellis County, with Red Oak ISD taxes and Texas homeowners insurance premiums, that initial escrow deposit can run several thousand dollars on its own. Your old lender then refunds your existing escrow balance, usually within 20 to 30 days after payoff.
So it nets out. Eventually. But it is real cash you have to produce at the closing table and then wait to get back, and it does not belong in your break-even math because it is not a cost, it is a timing problem. Keep it in a separate column and keep it in your savings account. I have watched buyers get blindsided by that line item more than once.
How to compute your break-even month
The formula is one line:
Break-even month = total closing costs ÷ monthly payment savings
Spend $6,500 to save $200 a month and you break even at month 33. Stay past month 33 and the refinance made you money. Sell, move, or refinance again before month 33 and it cost you money.
Two adjustments make that number honest.
First, if you refinance into a fresh 30-year term after two years of payments, part of your "savings" is just a longer payoff. You reset the clock and push principal further out. A same-term refinance, where you take the remaining 28 years instead of a new 30, shows you a smaller monthly savings and a longer break-even, and it is the more conservative way to look at it. I will show you both.
Second, use your real horizon, not a theoretical one. The median Red Oak home sold in about 45 days on market recently, but that is listing speed, not how long people stay. If you know this house is a five-year house, a 31-month break-even is fine. If you think you might be in Waxahachie or Midlothian in three years, it is not.
A Red Oak example, start to finish
Red Oak's median sale price ran about $420,000 over the trailing 30 days, up roughly 6.4 percent year over year, with a median of 45 days on market. (Source: Orchard Red Oak market report, September 2026.) Asking prices run higher than sold prices here, with Zillow showing a July 2026 median list price near $499,000 for the 75154 zip code, so do not anchor to list prices when you budget.
Assumptions
- Purchase price: $420,000, Red Oak, TX 75154
- Down payment: 20 percent, or $84,000
- Loan amount: $336,000, conventional 30-year fixed
- Note rate: 7.000 percent
- Illustrative APR: 7.219 percent, assuming approximately $7,300 in prepaid finance charges
- Principal and interest payment: $2,235.42 per month
- Taxes, insurance, and any HOA dues are not included in that figure
The rate, APR, and payment above are illustrative only, calculated from the stated assumptions for the purpose of showing the math. They are not a quote and not an offer of credit.
Year one on that loan: about $3,413 goes to principal and about $23,412 goes to interest. That is normal for an early amortization schedule and it is exactly why the interest rate carries so much weight in the first few years.
Now run the refinance two years later
After 24 payments, the balance is about $328,927. Assume $6,500 in refinance closing costs. Here is what different rate drops produce on a new 30-year term:
| New rate | Rate drop | New P&I | Illustrative APR | Monthly savings | Break-even |
|---|---|---|---|---|---|
| 6.50% | 0.50% | $2,079.04 | 6.603% | $156.38 | ~42 months |
| 6.25% | 0.75% | $2,025.26 | 6.352% | $210.16 | ~31 months |
| 6.00% | 1.00% | $1,972.08 | 6.100% | $263.34 | ~25 months |
| 5.75% | 1.25% | $1,919.53 | 5.849% | $315.89 | ~21 months |
Every row above assumes a conventional 30-year fixed refinance of a $328,927 balance, with approximately $3,500 of the $6,500 in costs treated as prepaid finance charges for the APR calculation. The note rates, APRs, and payments are illustrative examples calculated from those stated assumptions. They are not a quote, not an offer of credit, and not a commitment to lend. Your actual rate, APR, and payment depend on credit, income, property, loan program, and market conditions at the time of application, and all loans are subject to credit approval and underwriting.
Read the top row carefully. A half-point drop, which sounds like a real win, takes three and a half years just to repay the cost of getting it. And that row is generous, because it assumes a fresh 30-year term. Hold the term constant at the 28 years you have left and a 6.00 percent refinance, illustrative APR 6.105 percent on the same assumptions, saves $212.11 a month instead of $263.34, moving break-even from about 25 months to about 31.
All payment figures are principal and interest only, calculated from the stated assumptions. They are illustrative and not an offer of credit.
The rule of thumb, and why it is roughly right
The old guidance was that you need a full point before a refinance is worth doing. On these numbers, that holds up reasonably well. A full point puts break-even near two years, which most buyers will clear. Three-quarters of a point is a judgment call. A half point only works if your costs are unusually low or your loan is unusually large.
Bigger loans shift the answer, because closing costs do not scale as fast as the savings do. A $600,000 loan at the same half-point drop breaks even much faster than a $336,000 loan does. That is worth knowing if you are looking at the upper end of the Red Oak or Midlothian new construction market.
What a "no-cost refinance" really is
You will be offered one. It is not free. There are two versions and you should know which one you are being handed.
Version one: the costs get rolled into the balance. You bring nothing to closing and your loan grows by the amount of the costs. You are financing the fees at the new rate for up to 30 years. That is not a no-cost refinance, it is a borrowed-cost refinance.
Version two: the lender pays the costs and charges you a higher rate. This is the real one. The lender takes a rebate from the secondary market by pricing your loan above par and applies that credit to your fees. Typical spread is a quarter point to a half point above the best available rate.
Here is version two on our Red Oak numbers. Same $328,927 balance after two years. Suppose the market offers 6.25 percent with $6,500 in costs, or 6.75 percent with zero costs.
- Pay the costs at 6.25 percent, illustrative APR 6.352 percent: payment $2,025.26, saves $210.16 a month, $6,500 out of pocket, break-even month 31
- No-cost at 6.75 percent, illustrative APR 6.750 percent: payment $2,133.41, saves $102.01 a month, $0 out of pocket, break-even immediately
Both scenarios above are illustrative examples on a 30-year fixed refinance of the same $328,927 balance, calculated from the stated assumptions. They are not a quote and not an offer of credit.
The no-cost version wins from day one and keeps winning for 31 months. After that, the paid version pulls ahead and never looks back, by more than $100 a month for the rest of the loan. So the honest answer is that a no-cost refinance is the right call when your horizon is short or you think you will refinance again soon. If you are settled in Red Oak for the long haul, paying the costs wins.
There is a third option people forget: a partial credit. You can usually pick any point on the curve, taking a smaller lender credit at a rate between the two. I run that scale for clients rather than forcing an either-or.
Nobody can promise you a refinance
This is the part that gets skipped, and it is the part that matters most.
"Date the rate" assumes three things will all be true at some future date. Rates will be meaningfully lower. You will still qualify. And the numbers will still work for your situation. None of those three is guaranteed, and the first one is completely outside anyone's control.
Look at the record. The 30-year fixed averaged 6.26 percent a year ago and 6.95 percent on September 17, 2026, per Freddie Mac. Rates went up over that year, not down. The Fed just hiked for the first time since 2023. Markets are currently pricing in the possibility of more hikes into 2027, though market pricing is a snapshot, not a forecast, and it changes weekly.
The qualifying piece is just as real. A refinance is a full application. Your credit, income, debts, and appraised value all get re-examined at that future date. A job change, a new car note, a business income swing, or a soft appraisal can all block a refinance that looked automatic on paper two years earlier.
So the responsible way to use the phrase is this. Buy the house only if the payment works at today's rate, on today's budget, with no refinance in the plan. Treat a future refinance as upside you would enjoy, not as a rescue you are counting on. If the payment only works assuming a refinance, the payment does not work.
The other side of the ledger: what waiting can cost
Now the counterweight, stated as honestly as the rest of it. Waiting is not free either.
Red Oak's median sale price was up about 6.4 percent year over year as of September 2026, per Orchard. Across DFW, inventory in August 2026 sat around 5.85 months of supply on resale and 4.52 months on new construction, with a metro median around $410,000 to $415,000. (Sources: Homes.com Dallas-Fort Worth housing market report and Scribner DFW August 2026 data.) Statewide, the Texas Real Estate Research Center reported a 5.4-month supply and homes averaging 62 days on market in its August 2026 Texas Housing Insight, with Dallas-Fort Worth prices moving toward stabilization after an extended soft stretch.
Roughly five months of supply is a balanced market. It is not a market where buyers get handed everything, and it is not one where you lose ten offers in a row.
Here is the arithmetic on waiting twelve months, using our same Red Oak buyer at 20 percent down. These are scenarios built on stated assumptions, not predictions about what prices will do.
| If prices move | Price in 12 months | Down payment needed | P&I at 6.25% | vs. buying today at 7% |
|---|---|---|---|---|
| +2% | $428,400 | $85,680 | $2,110.19 | $125.23 less |
| +3% | $432,600 | $86,520 | $2,130.87 | $104.55 less |
| +5% | $441,000 | $88,200 | $2,172.25 | $63.17 less |
| +6.4% | $446,880 | $89,376 | $2,201.21 | $34.21 less |
Each row assumes a conventional 30-year fixed purchase loan at 80 percent loan-to-value with a 6.25 percent note rate and approximately 2.17 percent of the loan amount in prepaid finance charges, producing an illustrative APR of 6.459 percent. The 7 percent comparison is the same purchase loan at an illustrative APR of 7.219 percent. All figures are principal and interest only, calculated from the stated assumptions. They are illustrative examples, not a quote, not an offer of credit, and not a prediction of future prices or rates.
That bottom row uses Red Oak's actual trailing twelve-month price change. If that pace repeated and rates simultaneously dropped three-quarters of a point, the buyer who waited a full year would save about $34 a month and would need $5,376 more in cash to close. That is not a win. And the buyer who bought at 7 percent spent that year paying down about $3,413 in principal while owning the appreciation.
Flip the assumptions and waiting looks smart. Flat prices plus a one-point rate drop is a clear win for the patient buyer. Both outcomes are possible. That is the whole point. You are making a decision under uncertainty in both directions, and anyone selling you certainty on either side is selling.
How to actually decide
Four questions, in order.
Does the payment work today? Not with a refinance assumed. Today, at today's rate, with your real property taxes and your real insurance quote. Ellis County tax rates and Red Oak ISD assessments belong in that number, not a generic estimate.
How long is this house? Three years and five years produce genuinely different answers on every table above.
What is your break-even tolerance? If you would not accept a 42-month payback on any other spending decision, do not accept it on a refinance.
What else could move the payment? A permanent buydown bought at purchase, a builder-paid temporary buydown on a new construction contract, a 15-year term, or a larger down payment all change the math without depending on the bond market cooperating later. Those levers are available now.
That last question is where being licensed on both sides changes what I can tell you. A real estate agent sees the house and the contract. A loan officer sees the note. When you are comparing a seller concession against a rate buydown against a price reduction, those are the same dollars showing up in three different places, and the right answer depends on how long you keep the loan. Running the house side and the loan side together is the only way to see which of those three places your dollars should land.
Key takeaways
- Break-even is closing costs divided by monthly savings. On a $336,000 Red Oak loan with $6,500 in costs, a one-point rate drop breaks even around month 25 and a half-point drop takes about 42 months.
- The 30-year fixed averaged 6.95 percent on September 17, 2026, up from 6.26 percent a year earlier, and the Fed hiked 25 basis points on September 16 to 17, 2026. Rates moved up over the past year, not down.
- A no-cost refinance is a higher rate, usually a quarter to a half point. It wins on short horizons and loses on long ones.
- Budget separately for the new escrow account you have to fund at closing before your old lender refunds the balance, typically within 20 to 30 days.
- Red Oak's median sale price was about $420,000 and up roughly 6.4 percent year over year as of September 2026, so waiting carries its own price tag alongside its potential benefit.
FAQ: refinancing after buying in Red Oak, TX
How soon after closing can I refinance a Red Oak home?
Most conventional rate-and-term refinances have no mandatory waiting period, though many lenders require six months of seasoning. Texas cash-out refinances on a homestead carry their own state rules, including a 12-day cooling-off requirement.
How much does a refinance cost in Texas?
Plan on roughly 2 to 4 percent of the loan amount, which is about $6,500 to $13,000 on a $330,000 loan. Title insurance, lender fees, and the appraisal are the largest line items.
What if rates never drop enough to refinance?
Then you keep the loan you bought with, which is why the payment has to work at today's rate before you sign. A refinance is upside, not a plan.
Is Red Oak a buyer's market or a seller's market right now?
Based on current conditions, DFW inventory in August 2026 ran about 5.85 months on resale and 4.52 months on new construction, which is close to balanced. Red Oak homes were taking a median of about 45 days to sell.
How long does a refinance take to close?
Typically 30 to 45 days from application, depending on appraisal scheduling and how quickly income and asset documentation comes back.
Should I use a temporary buydown instead of waiting to refinance?
Sometimes. A 2-1 buydown lowers your payment for the first two years using seller or builder funds, and it does not depend on future rates. It also expires, so run it against the same break-even discipline.
Run your numbers before you commit to anything
The math above is built on stated assumptions. Yours will be different, because your credit, your down payment, your Ellis County tax assessment, and your insurance quote are yours. The way to know whether "marry the house, date the rate" works for your situation is to price it, both the purchase and the hypothetical refinance, on paper, with real numbers.
Start with a pre-approval so you are working from a real rate and a real payment instead of an estimate. Get pre-approved here, or call me directly at 972-846-9170.
Steven J. Thomas · Broker, Refind Realty DFW · TREC Broker License #0657467 · Loan Officer, Envision Home Lenders · NMLS #689220 · 128 S. Cockrell Hill Rd, DeSoto, TX 75115 · 972-846-9170
All rates, APRs, payments, and scenarios in this article are illustrative examples calculated from the stated assumptions and are for educational purposes only. They are not a quote, not an offer, and not a commitment to lend. Rates and terms are subject to change without notice. Actual rates, payments, APRs, and costs depend on credit, income, property, loan program, and market conditions at the time of application, and all loans are subject to credit approval and underwriting. Market data is cited as of the dates shown and reflects current conditions only; no future price, rate, or market outcome is predicted or guaranteed. Equal Housing Lender. Equal Housing Opportunity.
Stay Informed With My Downloadable
Buyer and Seller guides

6 Smart Ways to Build Home Equity

7 Insider Secrets To Selling Your Home w/o a Lot of Time or Money

DFW Home Seller Negotiation Secrets

Home Appraisals Guide

Avoiding Pitfalls That Can Derail Your Home's Sale

Ultimate Guide To Buying a Home

A First Time Homebuyers Guide In DFW

Are You Ready To Buy?

25 Insider Secrets To Buying A Home

How to Improve Your Credit
Download All My Guides For Free
Steven J. Thomas
Steven J. Thomas has been in the financial services industry for the past 19 years and started my career as a Financial Planner for American Express Financial Advisors. I entered into banking with JP Morgan Chase as personal banker in 2003 and was promoted several times up to Small Business Specialist. I earned multiple Million Dollar Club awards and was ranked in the top 5 Small Business Specialist before I branched out in 2005 to start my own Financial Management Company. I ran a successful company before family circumstances lead me to Wachovia Bank in 2008 where I worked as a Senior Financial Specialist. As a Sr. Financial Specialist; I was responsible for the P & L and revenue growth of my banking center. The elimination of my role thru a bank merger lead me to BBVA Compass. I have held various leadership roles at BBVA Compass including Personal Relationship Manager, Branch Retail Executive, Workplace Solutions VP, and his current role as a Retail Manager. As the Regional Workplace Solutions VP, I was responsible for the strategic, tactical, and execution of Partnership Banking relationships, promotion and activity with corporate and non-profit companies in my footprint. I was responsible for the acquisition production for three districts, which includes 51 banking centers and over 300 employees. In May of 2014, I joined the team at Refind Realty and became one of the managing partners in mid-2015.
Wondering What Your DFW Home Could Be Worth in2026?
Get a Professional Home Valuation From A Local Market Expert
Unlock insights into potential selling prices.
Get a personalized analysis sent directly to your inbox.
Stay ahead with updates on property value fluctuations.
Benchmark your property against neighborhood listings.
Get a FREE Home Valuation And Potential Net Sheet:
I used this realtor and it was a great experience. He was patient and very helpful with our journey. He also helped us find a great lender with little hassle on the process, also got us approved for well above the market of our original home so we were able to get more house with a lower mortgage rate. So to anyone who is interested in buying a home take my advice give Steven a call. It’s worth it 😁
Bryant Loring

Steve was absolutely amazing! Everything was easy! Very professional in all aspects. Punctual, responsive, and diligent. He goes above and beyond to ensure you get to see as many homes as you’d like no matter the location. Not only was he knowledgeable about home buying, he also has a resourceful network for new home owner needs. I recommend Refind Realty to everyone!
Nicholas Bishop
I definitely recommend Steven to assist with your home buying needs. As a first time home buyer the process can be overwhelming, but as my realtor he was knowledgeable & patient while addressing my concerns and assisting me with my new home purchase. Thanks again Steven!! :-)
Gayle Mason
Ask Us Anything
Frequently Asked Questions
Why do you need a Realtor?
When buying or selling a home, there are so many options…which can also present a lot of obstacles. Laws change, forms change, and practices change all the time in the real estate industry. Because it’s our job to stay on top of those things, hiring a realtor reduces risk, and can also save you a lot of money in the long run.
When you work with me as your Realtor, you’re getting an expert who knows the area; knows how to skillfully guide your experience as a seller or buyer; can easily spot the difference between a good deal and a great deal. My job is to translate your dream into a real estate reality, and I work hard to earn and keep my business. This also means earning your trust: When you work with me, you’ll be working with a realtor who looks out for your best interests and is invested in your goals.
Which loan should you choose?
There are two different types of loans conventional loans and government-backed loans. The main difference is who insures these loans:
1 - Government-backed loans (FHA, VA and USDA):
(a) - Are, unsurprisingly, backed by the government.
(b) - Include FHA loans, VA loans, and USDA loans.
(c) - Make up less than 40 percent of the home loans generated in the U.S. each year.
2 - Conventional loans
(a) - Are not backed by the government.
(b) - Include conforming and non-conforming loans (such as jumbo loans).
(c) - Make up more than 60 percent of the loans generated in the U.S. each year.
What is the difference between FHA, VA and USDA loans?
1 - FHA LOANS:
FHA loans, which are insured by the Federal Housing Administration, are typically designed to meet the needs of first-time homebuyers with low or moderate incomes. FHA loans can be approved with a down payment of as little as 3.5 percent and a credit score as low as 580.
FHA loans are often called “helper loans,” because they give a leg up to potential borrowers who may not be able to secure one otherwise. For this reason, FHA loans have maximum lending limits, which are determined based on housing values for the county where the for-sale home is located.
Because the agency is taking on more risk by insuring FHA loans, the borrower is expected to pay mortgage insurance both at the time of closing and on a monthly basis, and the property must be owner-occupied.
2 - VA LOANS:
VA loans are backed by the Department of Veterans Affairs and they are guaranteed to qualified veterans and active-duty personnel and their spouses. VA loans can be approved with 100 percent financing, meaning VA borrowers are not required to make a down payment.
Unlike FHA loans, borrowers do not have to pay mortgage insurance on VA loans.
3 - USDA LOANS:
You may also hear about USDA loans, which are backed by the United States Department of Agriculture mortgage program. USDA loans are intended to support homeowners who purchase homes in rural and some suburban areas. USDA loans do not require a down payment and may offer lower interest rates; borrowers may have to pay a small mortgage insurance premium in order to offset the lender’s risk.
What’s a conventional loan? Understanding what it means to be conforming and non-conforming
Buyers who have a more established credit history and a larger down payment may prefer to apply for a conventional loan. These loans may offer a lower interest rate and only require the home buyer to purchase monthly mortgage insurance while the loan-to-value ratio is above a certain percentage, so a conventional loan borrower can typically save money in the long run.
Conventional loans are divided into two types: Conforming loans and non-conforming loans.
1 - CONFORMING LOANS:
Conforming loans are those that meet (or conform to) predetermined standards set by Fannie Mae and Freddie Mac — two government-sponsored institutions that buy and sell mortgages on the secondary market. By selling the loans to "Fannie and Freddie," lenders can free up their capital and return to issue more mortgages than if they had to personally back every loan that they approve.
The main standard for conforming loans is that the amount borrowed must be under a certain amount; in Alaska, a single-family home loan must be under $647,200 in order to be considered conforming.
Properties with more than one unit have higher limits.
2 - NON-CONFORMING (JUMBO) LOANS:
But what happens if a borrower wants to borrow more than the Freddie- and Fannie-approved loan amount? In this case, they would have to apply for a “jumbo loan,” which is the most common type of non-conforming loan.
Because the lender cannot resell the jumbo loan (or any non-conforming loan) to Freddie Mac or Fannie Mae, jumbo loans are considered to be riskier than a conforming loan. To protect against this risk, the bank will typically require a higher down payment; the interest rate on a jumbo loan may also be higher than if the same borrower applied for a conforming loan.
What kind of rate should you choose?
Rate types: Fixed-rate vs. adjustable-rate mortgages.
In addition to the loan type you choose, you’ll also have to determine if you want a fixed-rate mortgage or an adjustable-rate mortgage (ARM). A fixed-rate mortgage has an interest rate that does not change for the life of the loan, so it provides predictable monthly payments of principal and interest.
An adjustable-rate mortgage typically offers an initial introductory period with a low-interest rate. Once this period is over, the interest rate adjusts periodically, based on the market index. The initial interest rate on an ARM can sometimes be locked in for different periods, such as one, three, five, seven, or 10 years. Once the introductory period is over, the interest rate typically readjusts annually.
Locate Us
Site: www.stevenjthomas.com
Call :(972) 846-9170
Email: [email protected]
Office 128 S. Cockrell Hill Rd, DeSoto TX 75115
Owned and Operated by Thomas & Thomas Financial Group, LLC
© Copyright 2026 | All Rights Reserved
Steven J. Thomas, REALTOR® · TREC License #0657467
Privacy Policy | Terms of Service | Fair Housing Statement
Refind Realty DFW · 128 S. Cockrell Hill Rd, DeSoto, TX 75115 · (972) 846-9170
Facebook
Instagram
X
LinkedIn
Youtube
TikTok