Refind Realty Blog
Glenn Heights, TX sellers: check these Third Party Financing Addendum lines before you accept an offer (2026)
Glenn Heights, TX sellers: check these Third Party Financing Addendum lines before you accept an offer
By Steven J. Thomas
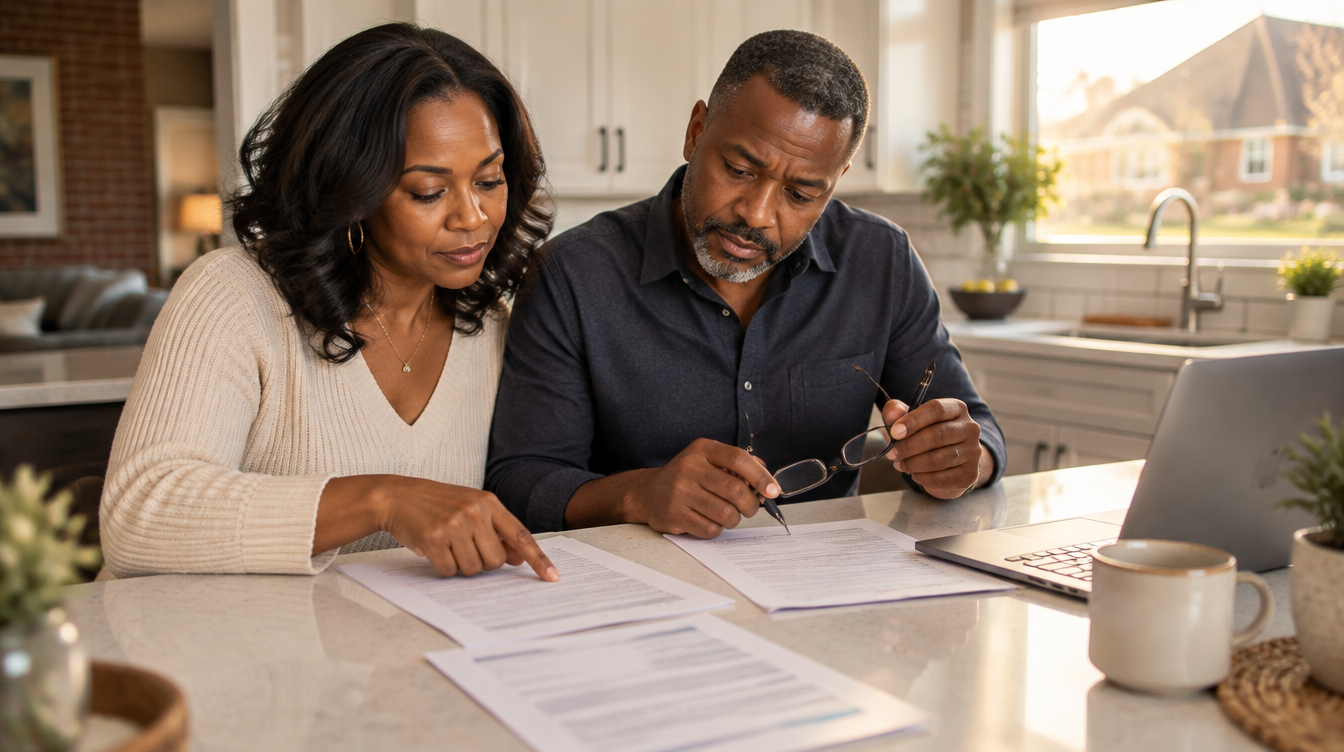
Caption: A Glenn Heights homeowner reads the financing pages of an offer before signing anything.
Mortgage rates hit about 7.11% this week, and the Federal Reserve raised its target rate on September 16. If you're selling a home in Glenn Heights, TX, that changes how you should read the financed offer sitting in your inbox. The price on page one gets all the attention. The Third Party Financing Addendum decides whether that price ever turns into a closing.
Here's my take, and I'll come back to it at the end. Most agents sell houses. I build plans. I'm licensed as a real estate broker and as a loan officer, so when an offer comes in on your home, I read the buyer's financing the way the underwriter is going to read it, before you sign.
Direct answer
Before a Glenn Heights seller accepts a financed offer, check four lines on TREC form 40-11: the number of days the buyer has for Buyer Approval, the interest rate cap written into Paragraph 1, whether the lender letter reflects a fully underwritten pre-approval, and whether the buyer has cash to cover an appraisal gap. Those lines predict a closing better than the price does. A Home Selling Score walk-through helps you spot appraisal risk before offers show up.
What the Third Party Financing Addendum controls for a Glenn Heights seller
Any time a buyer is borrowing from a bank or mortgage company, a TREC Third Party Financing Addendum gets attached to the contract. The current version is TREC form 40-11, effective January 3, 2025, and it's still the version listed on the Texas Real Estate Commission contracts page as of September 2026. It attaches to the resale contract, which moved to form 20-19 on July 1, 2026.
The addendum splits financing approval into two separate tests. Buyer Approval is about the buyer: income, assets, and credit. Property Approval is about your house: the appraisal, insurability, and any repairs the lender requires. Each one gives the buyer a different exit with a different deadline. Quick note before we go further. This is general information about how the form works, not legal advice. Your actual contract language controls, and a Texas real estate attorney is the right call for a legal question.
The Buyer Approval deadline
Paragraph 2A has a blank where the parties write in a number of days. That number is the financing contingency period people talk about. If the buyer can't get Buyer Approval, they can terminate by giving you written notice within that many days after the effective date, along with a written statement from their lender explaining why. When they do that, their earnest money goes back to them.
Now here's the part sellers miss. If the buyer does not terminate by that date, the form says the contract is no longer subject to Buyer Approval. Their clean financing exit closes. If they walk later because of their own credit or income, their earnest money is generally at risk under the contract.
So think of that blank as a free option you're handing the buyer on your house. A 21-day window means three weeks where your home is off the market and the buyer can leave with their deposit. A buyer whose file is already fully underwritten doesn't need that much time. A buyer who asks for a long window is often telling you their file isn't done.
The rate cap in Paragraph 1
This is the line I see skipped the most, and it matters a lot this month. Paragraph 1 describes the loan the buyer is applying for, including an interest rate the loan is not to exceed. Paragraph 2A says Buyer Approval is only obtained when the terms of the loan described in the addendum are available.
Picture a buyer who wrote their offer with a 6.5% rate cap in August. Rates are sitting around 7.1% now. If that buyer isn't locked, the loan described on their addendum may no longer exist in the market, and that can hand them a clean reason to terminate inside the Buyer Approval window. When an offer arrives, compare the rate cap to today's rates. A cap set below the market is a soft spot in the deal.
Property Approval and the appraisal
Paragraph 2B covers Property Approval. If the lender decides your home doesn't meet its underwriting requirements, whether that's a low appraisal, an insurance problem, or a required repair, the buyer can terminate and get their earnest money back. The deadline for that notice is set by the form itself: on or before the third day before the closing date. You don't negotiate it, and it runs almost to the end of the deal.
FHA and VA loans add Paragraph 4, which lets the buyer out if the appraisal comes in under a dollar amount written on the form. In a flat market, appraisers have very little price growth to lean on. That makes the appraisal the biggest Property Approval risk on most Glenn Heights deals right now.
Pre-qualification vs a fully underwritten pre-approval
Every financed offer comes with a lender letter. They don't all mean the same thing, and the words on the letter matter.
A pre-qualification is usually a conversation. The loan officer took the buyer's word on income and debts, maybe looked at a credit score, and estimated a price range. Nobody has verified anything yet.
A pre-approval means credit was pulled and the buyer sent in pay stubs, W-2s or tax returns, and bank statements. Often the file has been run through Fannie Mae or Freddie Mac automated underwriting. That's a real step up.
A fully underwritten pre-approval means an actual underwriter reviewed the buyer's income, assets, and credit and signed off, with the property still to come. Some lenders call this a credit approval or a TBD underwrite. That's the strongest letter a financed buyer can bring you, because Buyer Approval under Paragraph 2A is the exact question that underwriter already answered.
Why a rate spike mid-contract can break a thin DTI
DTI is debt-to-income: the buyer's monthly debts, including the new house payment, divided by gross monthly income. Lenders have limits. When rates move after the buyer applied and before they lock, the house payment grows and so does the DTI.
Here's real math on a $425,000 Glenn Heights offer. That's above the city's median sale price, so think of a larger or newer home. The buyer puts 10% down and borrows $382,500 on a 30-year fixed loan.
- Principal and interest at 6.5%: $2,417.66 a month
- Principal and interest at 7.1%: $2,570.52 a month
- Difference: $152.86 a month, about $1,834 a year
For this illustration, add $900 a month for property taxes, insurance, and mortgage insurance, plus $700 a month in car and card payments. Those two numbers are placeholders for the example, not a quote. A buyer who sits at exactly 44% DTI at 6.5% earns about $9,131 a month, roughly $109,600 a year. Run the same buyer at 7.1% and the DTI climbs to about 45.7%. To stay at 44%, they'd need about $9,478 a month in income.
That 1.7-point jump can be the whole deal. Some files clear it through automated underwriting with strong credit and cash reserves, and some get a counteroffer from the lender or a flat no. Another way to see it: to keep the same principal and interest payment at 7.1%, that buyer's loan would need to drop to about $359,750, which works out to a price near $399,700 at 10% down. Your house didn't change. The buyer's budget did.
This is why rate lock status matters so much. A buyer who is locked is protected until the lock expires. A buyer who is floating is carrying the rate risk, and so are you.
What a Glenn Heights seller can reasonably ask for before accepting
You're allowed to ask questions before you sign. A strong buyer usually answers them quickly. Here's what I ask for on my sellers' behalf.
- An updated lender letter dated within the last few days, stating that credit was pulled and income and asset documents were reviewed.
- Whether an underwriter has reviewed the file, or only automated underwriting.
- A Buyer Approval period that fits how far along the file is. A fully underwritten buyer can often live with a shorter window.
- A rate cap in Paragraph 1 that matches today's market instead of last month's.
- Rate lock status, the locked rate, and the lock expiration date compared to the closing date.
- Proof of funds for the down payment, closing costs, and any appraisal gap the buyer is offering to cover.
- A direct conversation with the loan officer. Paragraph 5 of the addendum authorizes the lender to give status updates to the parties and their representatives.
Think of this list as screening. A buyer can decline any of it, and you get to decide how much that answer tells you. For more on what trips up sellers in the middle of a contract, grab the Dallas home sale pitfalls guide.
How I read a lender letter as a broker and loan officer
I start with the letter itself. Who signed it, when it's dated, which loan program it names, and whether that program matches the box checked on the addendum. A letter that says FHA attached to an addendum that says conventional tells me the buyer's side hasn't compared notes.
Then I call the loan officer. I ask whether an underwriter has seen the file, what DTI they approved the buyer at, what rate they used to get there, and whether the rate is locked. If they qualified the buyer at 6.5% and the buyer isn't locked, I already know what the 7.1% math looks like, because I just ran it.
Red flags I watch for:
- The word "pre-qualified" anywhere on the letter
- A letter more than a couple of weeks old with no update
- A loan officer who won't return a call before you respond to the offer
- No mention of credit being pulled or documents being reviewed
- A DTI already in the mid-40s with no rate lock
"A lender letter is a claim. Before you take your house off the market, I want to see what's backing it up." — Steven J. Thomas, Broker at Refind Realty DFW and Loan Officer at Envision Home Lenders
Glenn Heights spotlights: how financing risk shows up by price range
Homes under the Glenn Heights median
Below the city's median sale price of about $367,000, a lot of your buyers will be using FHA, VA, or low-down-payment conventional loans. That brings Paragraph 4 into play on FHA and VA offers, where the appraised value has to meet the number written on the form. Smaller down payments also mean less room in the budget when rates move, so a floating rate carries more weight here. With homes taking longer to sell this year, you may be tempted to take the first financed offer. Screen it the same way you'd screen a bigger one. If you're still deciding how to sell, compare your home selling options before you list.
Homes in the $400,000s
This is where the $425,000 example lives. Buyers here often stretch to reach a bigger floor plan or a newer build, and stretched buyers tend to have higher DTIs. A move from 6.5% to 7.1% adds about $153 a month to the payment on a 10% down loan in this range, which is enough to push a borderline file over. Ask about the rate lock first on offers at this price. Also look closely at appraisal gap language, since the fewer recent sales you have at your price point, the harder the appraiser's job gets. A clean pre-listing prep plan helps your home support its price, and the Dallas home seller checklist walks through it.
Newer homes competing with new construction
If your home is only a few years old, your buyer is probably also touring new builds along the I-35E corridor. Those buyers often come in with an approval from a builder's preferred lender and then switch to shop for your house. Ask whether the lender letter was issued for your address and price or for a different property. Compare pricing with the DFW market statistics page so your number holds up next to theirs.
Pro Tip: Get your Home Selling Score before you list. I walk your home in person for about 30 minutes and give you a readiness score, and the same things that drag the score down tend to show up again at the appraisal and on the lender's repair list.
Local market trends (fall 2026)
These numbers are based on current conditions and the latest data available at the time of writing.
- Glenn Heights median sale price: $367,257 (up 0.3% year over year, Source: Redfin, August 2026)
- Glenn Heights average days on market: 79 days (up from 62 a year earlier, Source: Redfin, August 2026)
- 30-year fixed mortgage rate: about 7.11% (Source: Forbes Advisor, September 24, 2026)
- Federal funds target range: raised to 3.75% to 4.00% (Source: Federal Reserve, September 16, 2026)
- DFW active inventory: down 4.3% year over year, with 4.6 months of supply and prices down 0.2% year over year (Source: Texas Real Estate Research Center, September 2026 report on July data)
Put those together and you get a slow, flat market. Glenn Heights homes are taking weeks longer to sell than a year ago, prices are basically unchanged, and borrowing just got more expensive. When a financed offer falls apart in a market like this, you lose the buyer and every week you spent under contract with them.
"In a flat market, the appraisal and the buyer's DTI do most of the negotiating. I'd rather you know where both stand before you sign than find out on day 25." — Steven J. Thomas, Broker at Refind Realty DFW and Loan Officer at Envision Home Lenders
Cost breakdown for Glenn Heights sellers when a financed deal goes sideways
Here's what's actually at stake when a financed offer fails. The numbers below use the $425,000 example.
- Carrying costs: your own monthly mortgage, taxes, insurance, and utilities, multiplied by every week you're under contract with a buyer who can still walk
- Appraisal gap: a 3% low appraisal on $425,000 is $12,750 that someone has to cover, renegotiate, or walk away from
- Seller credit to rescue a buyer's numbers: 1% of the price is $4,250, and 2% is $8,500
- Lender-required repairs from Property Approval: varies by home, and these usually show up late in the contract
- Relisting time: with Glenn Heights averaging 79 days on market as of August 2026, starting over can add months
Screening an offer for an hour up front costs you nothing. Accepting a weak one can cost you a season. The difference shows up in your net at closing.
New construction and other competition: know who's courting your buyer
Glenn Heights sits between DeSoto and Red Oak on I-35E, and a financed buyer shopping your price range is often touring new construction too. Builders often offer rate incentives through their preferred lenders when rates climb.
That affects you two ways. First, a buyer whose approval was built around a builder's incentive rate may not qualify at the same price on your resale home at 7.1%. Second, your listing price and condition have to hold up against a brand-new house with a warranty. Ask which lender issued the letter and what rate the approval assumed. If the answer is a builder's incentive rate, the math in the DTI section above is the math you need to run.
Financing and incentives that help your buyer close
If you like an offer but the buyer's DTI is tight, you have options besides walking away. A seller-paid permanent rate buydown lowers the buyer's note rate, and the lender qualifies the buyer at that lower rate. That can pull a 45.7% DTI back under the line. A temporary buydown, like a 2-1, lowers the first years' payments, but lenders usually qualify the buyer at the full note rate, so it rarely fixes a DTI problem.
A straight price reduction also helps, but dollar for dollar it often does less for the monthly payment than a buydown. The right answer depends on the buyer's file, their loan program's concession limits, and your net. This is the part where being licensed on both sides pays off for you. I can run your net sheet and the buyer's qualifying math at the same time. Loan terms, rates, and payment examples in this post are illustrations only, not a loan offer or commitment. Rates change daily and every borrower's approval depends on their own credit, income, and assets.
Conclusion
With rates at 7.1% and a fresh Fed hike, read the Third Party Financing Addendum on any financed Glenn Heights offer before you sign. Check the Buyer Approval days, the rate cap, the type of lender letter, the lock status, and the buyer's cash for an appraisal gap. Ask for the updates you're entitled to request, and talk to the loan officer before you respond. Remember what I said at the top. Most agents sell houses. I build plans, and your plan starts with knowing whether the buyer in front of you can actually close.
- Start with your Home Selling Score, a 30-minute in-person walk-through that shows how ready your home is for the appraisal and the market.
- Download the Lone Star Living App to watch what's listing and selling around you in Glenn Heights.
- Book an appointment today at stevenjthomas.com/book or call 972-846-9170.
You're Always Home with Steven J. Thomas.
Key takeaways
- The number of days written into Paragraph 2A of TREC form 40-11 is how long the buyer can leave with their earnest money for credit or income reasons. Shorter is better for you when the buyer's file supports it.
- Compare the rate cap in Paragraph 1 to today's rate of about 7.11%. A cap set below the market can give a buyer who hasn't locked a clean exit.
- On a $425,000 Glenn Heights offer with 10% down, a move from 6.5% to 7.1% adds about $153 a month and can push a 44% DTI buyer to roughly 45.7%.
- Property Approval, including the appraisal, can end the deal until three days before closing. With Glenn Heights prices up only 0.3% year over year (Redfin, August 2026), ask about appraisal gap cash.
- Get your Home Selling Score before you list so appraisal and repair issues get handled before a buyer's lender finds them.
FAQ: TREC Third Party Financing Addendum for Glenn Heights sellers
What happens if the buyer doesn't terminate by the Buyer Approval deadline?
Under TREC form 40-11, the contract is no longer subject to Buyer Approval once that deadline passes without a termination notice. After that, a buyer who backs out over their own credit or income generally puts their earnest money at risk, though Property Approval rights still apply.
How much does a rate increase from 6.5% to 7.1% change a buyer's payment?
On a $382,500 loan, which is a $425,000 price with 10% down, principal and interest rises from about $2,417.66 to $2,570.52 a month. That's about $153 more each month, enough to push a borderline DTI over a lender's limit.
Can a low appraisal cancel a financed contract in Texas?
Yes. If the lender decides the property doesn't meet its requirements, including appraised value, the buyer can terminate under Property Approval on or before the third day before closing and get the earnest money back. FHA and VA loans add a separate appraisal provision in Paragraph 4.
Are financed offers riskier in Glenn Heights right now?
The risk is higher than it was earlier this year because rates rose and homes are selling slower. Redfin reported Glenn Heights homes averaging 79 days on market in August 2026, up from 62 a year earlier, so a failed contract costs more time.
How long does a buyer have to get financing approval on a Texas resale contract?
Whatever number of days the parties write into Paragraph 2A of the addendum, counted from the effective date. Property Approval runs separately, until the third day before the closing date.
Where can I see what homes are listing and selling in Glenn Heights?
Download the Lone Star Living App at lonestarliving.hsidx.com/@sthomas to follow Glenn Heights listings, recent sales, and price changes near your home.
This article is general information based on current market conditions as of September 24, 2026. It is not legal advice and does not guarantee any sale price, timeline, or loan approval. Consult a Texas real estate attorney about your specific contract.
Steven J. Thomas · Broker, Refind Realty DFW · TREC Broker License #0657467 · Loan Officer, Envision Home Lenders · NMLS #689220 · Equal Housing Opportunity
Texas Real Estate Commission Information About Brokerage Services · TREC Consumer Protection Notice
BLOG NAVIGATION
Contact Me By Filling Out
The Form Below
We Can Help You Reach Your Real Estate Goals!
Locate Us
Site: www.stevenjthomas.com
Call :(972) 846-9170
Email: [email protected]
Office 128 S. Cockrell Hill Rd, DeSoto TX 75115
Owned and Operated by Thomas & Thomas Financial Group, LLC
© Copyright 2026 | All Rights Reserved
Steven J. Thomas, REALTOR® · TREC License #0657467
Privacy Policy | Terms of Service | Fair Housing Statement
Refind Realty DFW · 128 S. Cockrell Hill Rd, DeSoto, TX 75115 · (972) 846-9170
Facebook
Instagram
X
LinkedIn
Youtube
TikTok