Refind Realty Blog
Check the Flood Map Before You Offer on That Waxahachie House (2026)
Check the Flood Map Before You Offer on That Waxahachie House (2026)
By Steven J. Thomas
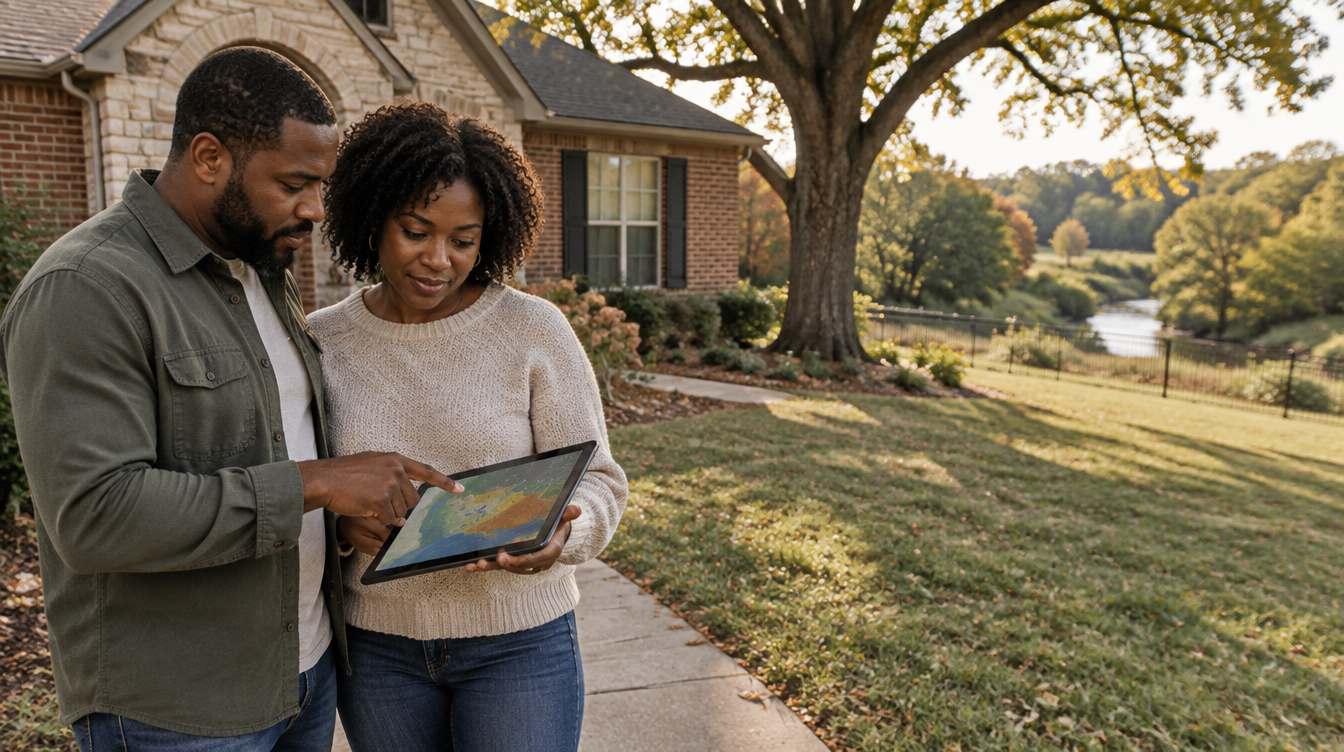
[Caption: Two buyers checking a FEMA flood map on a tablet before writing an offer on a Waxahachie, TX home near a tree-lined creek.]
You found the house in Waxahachie. The price works, the kitchen works, and you're ready to write an offer tonight. Before you do, look up one thing most buyers skip: the flood zone. If that address sits in a FEMA high-risk flood zone and you're using a federally backed mortgage, flood insurance isn't optional. It goes into your monthly payment and into your debt-to-income ratio, and most buyers don't find that out until underwriting. I'm licensed on both the real estate side and the mortgage side, so I run the payment with flood insurance included before you write the offer. Not three weeks into the contract.
Direct answer
Before you make an offer in Waxahachie, search the address on FEMA's Flood Map Service Center. If it's in a Special Flood Hazard Area (Zone A or AE) and your loan is federally backed, your lender will require flood insurance. Get a flood quote during your option period and have your lender rerun the payment and DTI with that premium included. A pre-approval that includes the flood premium tells you the real number up front.
Why Waxahachie buyers should check the flood map first
Waxahachie has real water running through it. Waxahachie Creek cuts through the city, Lake Waxahachie sits to the south, and Lake Bardwell is about 10 miles southeast of town. Bardwell was built by the U.S. Army Corps of Engineers in the 1960s on Waxahachie Creek, partly for flood control, and it provides flood protection to roughly 495,000 acres of floodplain along Waxahachie Creek, Chambers Creek, Richland Creek, and the Trinity River (Source: Texas State Historical Association Handbook of Texas and the USACE Fort Worth District).
That doesn't mean any particular Waxahachie neighborhood is in a flood zone. I'm not going to tell you which streets are and which aren't, because the answer is address by address and the maps change. The City of Waxahachie's own Flood Information page lists Zone AE, Zone A, and both shaded and unshaded Zone X inside city limits. The City of Midlothian has also applied to FEMA for a Letter of Map Revision along Waxahachie Creek that covers parts of Midlothian, Waxahachie, and Ellis County. So you check the specific house, every time.
How to look up a Waxahachie address on the FEMA flood map
This takes about five minutes. Do it before you tour, or at least before you write.
- Go to the FEMA Flood Map Service Center, type the full street address, and click "Interactive Map" where it's offered.
- Look at the zone on the lot and on the house itself. A lot can be partly in a flood zone while the structure sits outside it.
- Cross-check the City of Waxahachie's FEMA Floodplain 2023 map. Outside city limits, Ellis County handles floodplain rules.
What the flood zone letters mean
A Special Flood Hazard Area, or SFHA, is land FEMA maps as having a 1% annual chance of flooding. People call it the 100-year floodplain. That name misleads buyers. It doesn't mean one flood every hundred years. It means a 1% chance in any given year, and over a 30-year mortgage those odds add up.
- Zone AE: High-risk area where FEMA did a detailed study and set a Base Flood Elevation, the height floodwater is expected to reach in that 1% event.
- Zone A: High-risk area mapped with an approximate study. There may be no Base Flood Elevation published.
- Zone X (shaded): Moderate risk, the 500-year floodplain, a 0.2% annual chance.
- Zone X (unshaded): Outside the 500-year floodplain. Lower risk, still some risk.
Zone X doesn't mean zero risk. The City of Waxahachie's flood page says it directly about unshaded Zone X: there is still potential for flooding. Heavy rain and poor drainage flood homes that sit nowhere near a mapped floodplain. Lenders generally won't require flood insurance in Zone X, but you can still buy it, and it's often cheaper there.
What your lender requires in a high-risk zone
If the house is in an SFHA and your loan is federally backed, which covers conventional loans sold to Fannie Mae or Freddie Mac plus FHA, VA, and USDA, federal law requires flood insurance for the life of the loan (Source: Congressional Research Service, NFIP Risk Rating 2.0 FAQ). The lender also has to escrow it in most cases, so the premium shows up in your monthly payment right next to property taxes and homeowners insurance.
You have two ways to buy that coverage.
- NFIP: The National Flood Insurance Program, run by FEMA and sold through insurance agents. Details and a coverage overview are on FloodSmart.gov.
- Private flood insurance: Lenders can accept a private policy as long as it provides coverage at least as broad as the NFIP policy, per federal statute (Source: Congressional Research Service). Sometimes private is cheaper. Sometimes it isn't. Get both quotes.
One timing rule catches people. NFIP policies normally carry a 30-day waiting period before coverage starts. There's an exception when you buy the policy in connection with making, increasing, extending, or renewing a loan. In that case coverage can take effect at closing (Source: FEMA NFIP Bulletin W-10063). The premium has to reach the carrier on time for that exception to hold, so your title company and lender need to handle the payment correctly. Don't assume. Ask.
Flood premiums are priced by the house, not the zone
Since April 2022, the NFIP has priced policies under Risk Rating 2.0. FEMA no longer sets your premium mainly by flood zone. It looks at the specific building: distance to water, type and frequency of flooding, foundation type, the height of the lowest floor compared to the Base Flood Elevation, prior claims, and the cost to rebuild (Source: Congressional Research Service, and FEMA's Risk Rating 2.0 FAQ).
So two houses on the same street can get very different quotes. By statute, NFIP premiums for a primary residence can rise up to 18% per year until they reach the full-risk rate, so a low premium the seller has today may climb (Source: Congressional Research Service). Always get your own quote on your own policy.
Ask for the elevation certificate
An elevation certificate is a FEMA form completed by a licensed surveyor or engineer. It records how high the lowest floor sits compared to the Base Flood Elevation. Under Risk Rating 2.0 it isn't always required, but it can help an agent quote the policy more accurately, and in some cases it can lower the premium.
Ask the listing agent whether the seller has one, or check with the city's floodplain office. If neither exists, you can hire a surveyor during your option period. It costs money. So does a premium surprise that stays for 30 years.
What the seller has to tell you under Texas law
Texas Property Code Section 5.008 requires most resale sellers to give you a written Seller's Disclosure Notice. In 2019 the Legislature passed Senate Bill 339, which added a full set of flood questions starting September 1, 2019. The seller has to tell you what they know about:
- Whether the property is wholly or partly in a 100-year or 500-year floodplain
- Whether it's in a floodway, flood pool, or reservoir
- Whether the home has flooded, and whether flood damage has been repaired
- Whether they've filed a flood insurance claim or received federal flood assistance
- Whether they currently carry flood insurance
TREC publishes the Seller's Disclosure Notice that sellers use to meet this requirement, and TREC updates the form from time to time. Confirm the current version on TREC's site before you rely on it.
The disclosure only covers what the seller knows, and never-occupied new construction is exempt from Section 5.008. Check the FEMA map yourself either way.
This post is general information, not insurance or legal advice. Talk to a licensed insurance agent about coverage and an attorney about your contract rights.
Waxahachie market and rates (fall 2026)
Based on current conditions:
- Waxahachie median sale price: about $365,000 over the last three months, down 5.2% year over year, with homes selling in about 61 days (Source: Redfin, data as of July 2026)
- DFW months of supply: 4.6 months, with active inventory down 4.3% year over year. Texas statewide sits at 5.5 months (Source: Texas Real Estate Research Center, Texas Housing Insight, September 2026 report, July data)
- 30-year fixed mortgage rate: 6.95% as of September 17, 2026, up from 6.76% the week before and 6.71% on September 3 (Source: Freddie Mac PMMS, September 2026)
- Federal funds rate: raised 25 basis points to a 3.75% to 4% range on September 16, 2026 (Source: Federal Reserve FOMC statement)
Read those together. Waxahachie prices have eased and homes are sitting about two months, which gives you room to negotiate. But rates climbed through September, so every monthly dollar counts more. A flood premium you know about early is a negotiating point. One you find at underwriting can push your ratio over the line.
Buyers rarely lose a house over flood insurance at the showing. They lose it at underwriting, three weeks in, when the payment finally gets run with the real numbers. Run them before you sign.
What a flood premium does to your payment and DTI
Here's an illustrative example. It isn't a quote, an approval, or an offer of credit, and the flood premium below is a made-up round number. Your actual premium depends on the specific house.
- Purchase price: $365,000 (the recent Waxahachie median)
- Down payment: 10%, so a loan of $328,500
- Rate: 6.95% (7.02% APR), 30-year fixed (the September 17 Freddie Mac PMMS average, used only for illustration, not a quoted rate)
- Principal and interest: about $2,175 a month
- Assumed total housing payment with property taxes and homeowners insurance: $3,100 a month
- Assumed gross income: $9,500 a month, with $600 a month in other debts
Without flood insurance, the housing payment is 32.6% of gross income and total debt-to-income is 38.9%.
Now add an illustrative flood premium of $1,200 a year. That's $100 a month in escrow. Housing ratio goes to 33.7%. Total DTI goes to 40.0%.
A 1.1-point jump might still fit your program. It might not. Look at it the other way too. At 6.95%, $100 a month in payment is roughly the same as $15,100 of loan amount. So a flood premium you didn't plan for can quietly cost you about $15,000 of buying power, or push you into a smaller price range altogether.
Rates, guidelines, and premiums change. Nothing here is an approval or a guarantee of terms. Get pre-approved with your real numbers and I'll run it with the flood premium in the payment from the start.
Get the flood quote during your option period
In a standard Texas resale contract, the option period is your window to inspect, ask questions, and walk away for any reason, with only your option fee at risk. Use it for flood.
- Day one: pull the FEMA map, read the seller's disclosure flood section, and ask for any elevation certificate and the seller's current flood policy declarations page.
- Days one to three: get at least one NFIP quote and one private flood quote through a licensed insurance agent.
- As soon as you have a number: send it to your loan officer and have them rerun the payment and DTI.
- Before the option period ends: decide. Proceed, negotiate a price or closing-cost credit to offset the premium, or walk.
Conclusion
Waxahachie gives buyers room to negotiate right now, but rates are higher than they were a month ago and a flood premium goes straight into your payment. Check the FEMA map before you offer. Read the flood section of the seller's disclosure. Ask for the elevation certificate, and get real quotes while you can still walk away. Most buyers find out about flood insurance at underwriting. You don't have to. Because I'm licensed on both the real estate and mortgage side, I run the payment with flood insurance included before you write the offer, so the number you negotiate on is the number you'll actually pay. Start your pre-approval here, or call or text 972-846-9170.
Steven J. Thomas, Broker, Refind Realty DFW, TREC Broker License #0657467, Loan Officer, Envision Home Lenders, NMLS #689220. Equal Housing Opportunity. Envision Home Lenders NMLS #2619789. Example APR of 7.02% assumes a $328,500 loan, 10% down, 30-year fixed at 6.95%, $1,495 in lender fees, 0 points, 15 days prepaid interest, and no mortgage insurance. Rates shown are Freddie Mac PMMS weekly averages, not quoted rates. Illustrative example, not a loan offer, rate lock, or commitment to lend. Information is general and based on current conditions as of September 2026. Rates, premiums, and guidelines change, and nothing here is an offer of credit, a rate quote, insurance advice, or a guarantee of approval.
You're Always Home with Steven J. Thomas.
Takeaways
- Search every Waxahachie address on FEMA's Flood Map Service Center before you write an offer. Zones A and AE are high-risk Special Flood Hazard Areas.
- With a federally backed mortgage, flood insurance is required in an SFHA and is usually escrowed into your monthly payment.
- NFIP normally has a 30-day waiting period, but coverage bought in connection with a loan closing can start at closing if the premium is paid on time.
- Under Risk Rating 2.0, premiums are priced house by house. The seller's premium isn't your premium.
- In the illustrative example, a $100 monthly flood premium moved total DTI from 38.9% to 40.0% and equaled about $15,100 of loan amount at 6.95%.
FAQ: Flood zones and buying a home in Waxahachie, TX
When should I check the flood zone on a Waxahachie home?
Check it before you write the offer. It takes a few minutes on FEMA's Flood Map Service Center, and it tells you whether your lender will require flood insurance.
How much does flood insurance add to my mortgage payment?
It depends on the specific house, because NFIP premiums under Risk Rating 2.0 are priced by the building's features. The annual premium divided by 12 is added to your monthly escrow, and your lender counts it in your debt-to-income ratio.
What if I find out about the flood zone after I'm under contract?
If you're still in your option period, you can get quotes, renegotiate, or terminate. After it ends, your choices narrow and your earnest money may be at risk, so check early.
Does Zone X in Waxahachie mean no flood risk?
Zone X is lower risk, not no risk. The City of Waxahachie says unshaded Zone X still has potential for flooding, and you can buy flood insurance there even when the lender doesn't require it.
How long does it take for flood insurance to start?
NFIP policies usually have a 30-day waiting period. When the policy is bought in connection with a new loan, coverage can take effect at closing, as long as the premium reaches the insurer on time.
Where can I look up the flood map for a Waxahachie property?
Use FEMA's Flood Map Service Center at msc.fema.gov and the City of Waxahachie's Flood Information page. Then get pre-approved so your payment includes any flood premium before you offer.
BLOG NAVIGATION
Contact Me By Filling Out
The Form Below
We Can Help You Reach Your Real Estate Goals!
Locate Us
Site: www.stevenjthomas.com
Call :(972) 846-9170
Email: [email protected]
Office 128 S. Cockrell Hill Rd, DeSoto TX 75115
Owned and Operated by Thomas & Thomas Financial Group, LLC
© Copyright 2026 | All Rights Reserved
Steven J. Thomas, REALTOR® · TREC License #0657467
Privacy Policy | Terms of Service | Fair Housing Statement
Refind Realty DFW · 128 S. Cockrell Hill Rd, DeSoto, TX 75115 · (972) 846-9170
Facebook
Instagram
X
LinkedIn
Youtube
TikTok