Refind Realty Blog
Self-Employed and Buying New Construction in Midlothian? Your Tax Return Is Lying About What You Can Afford (2026)
Self-Employed and Buying New Construction in Midlothian? Your Tax Return Is Lying About What You Can Afford (2026)
By Steven J. Thomas
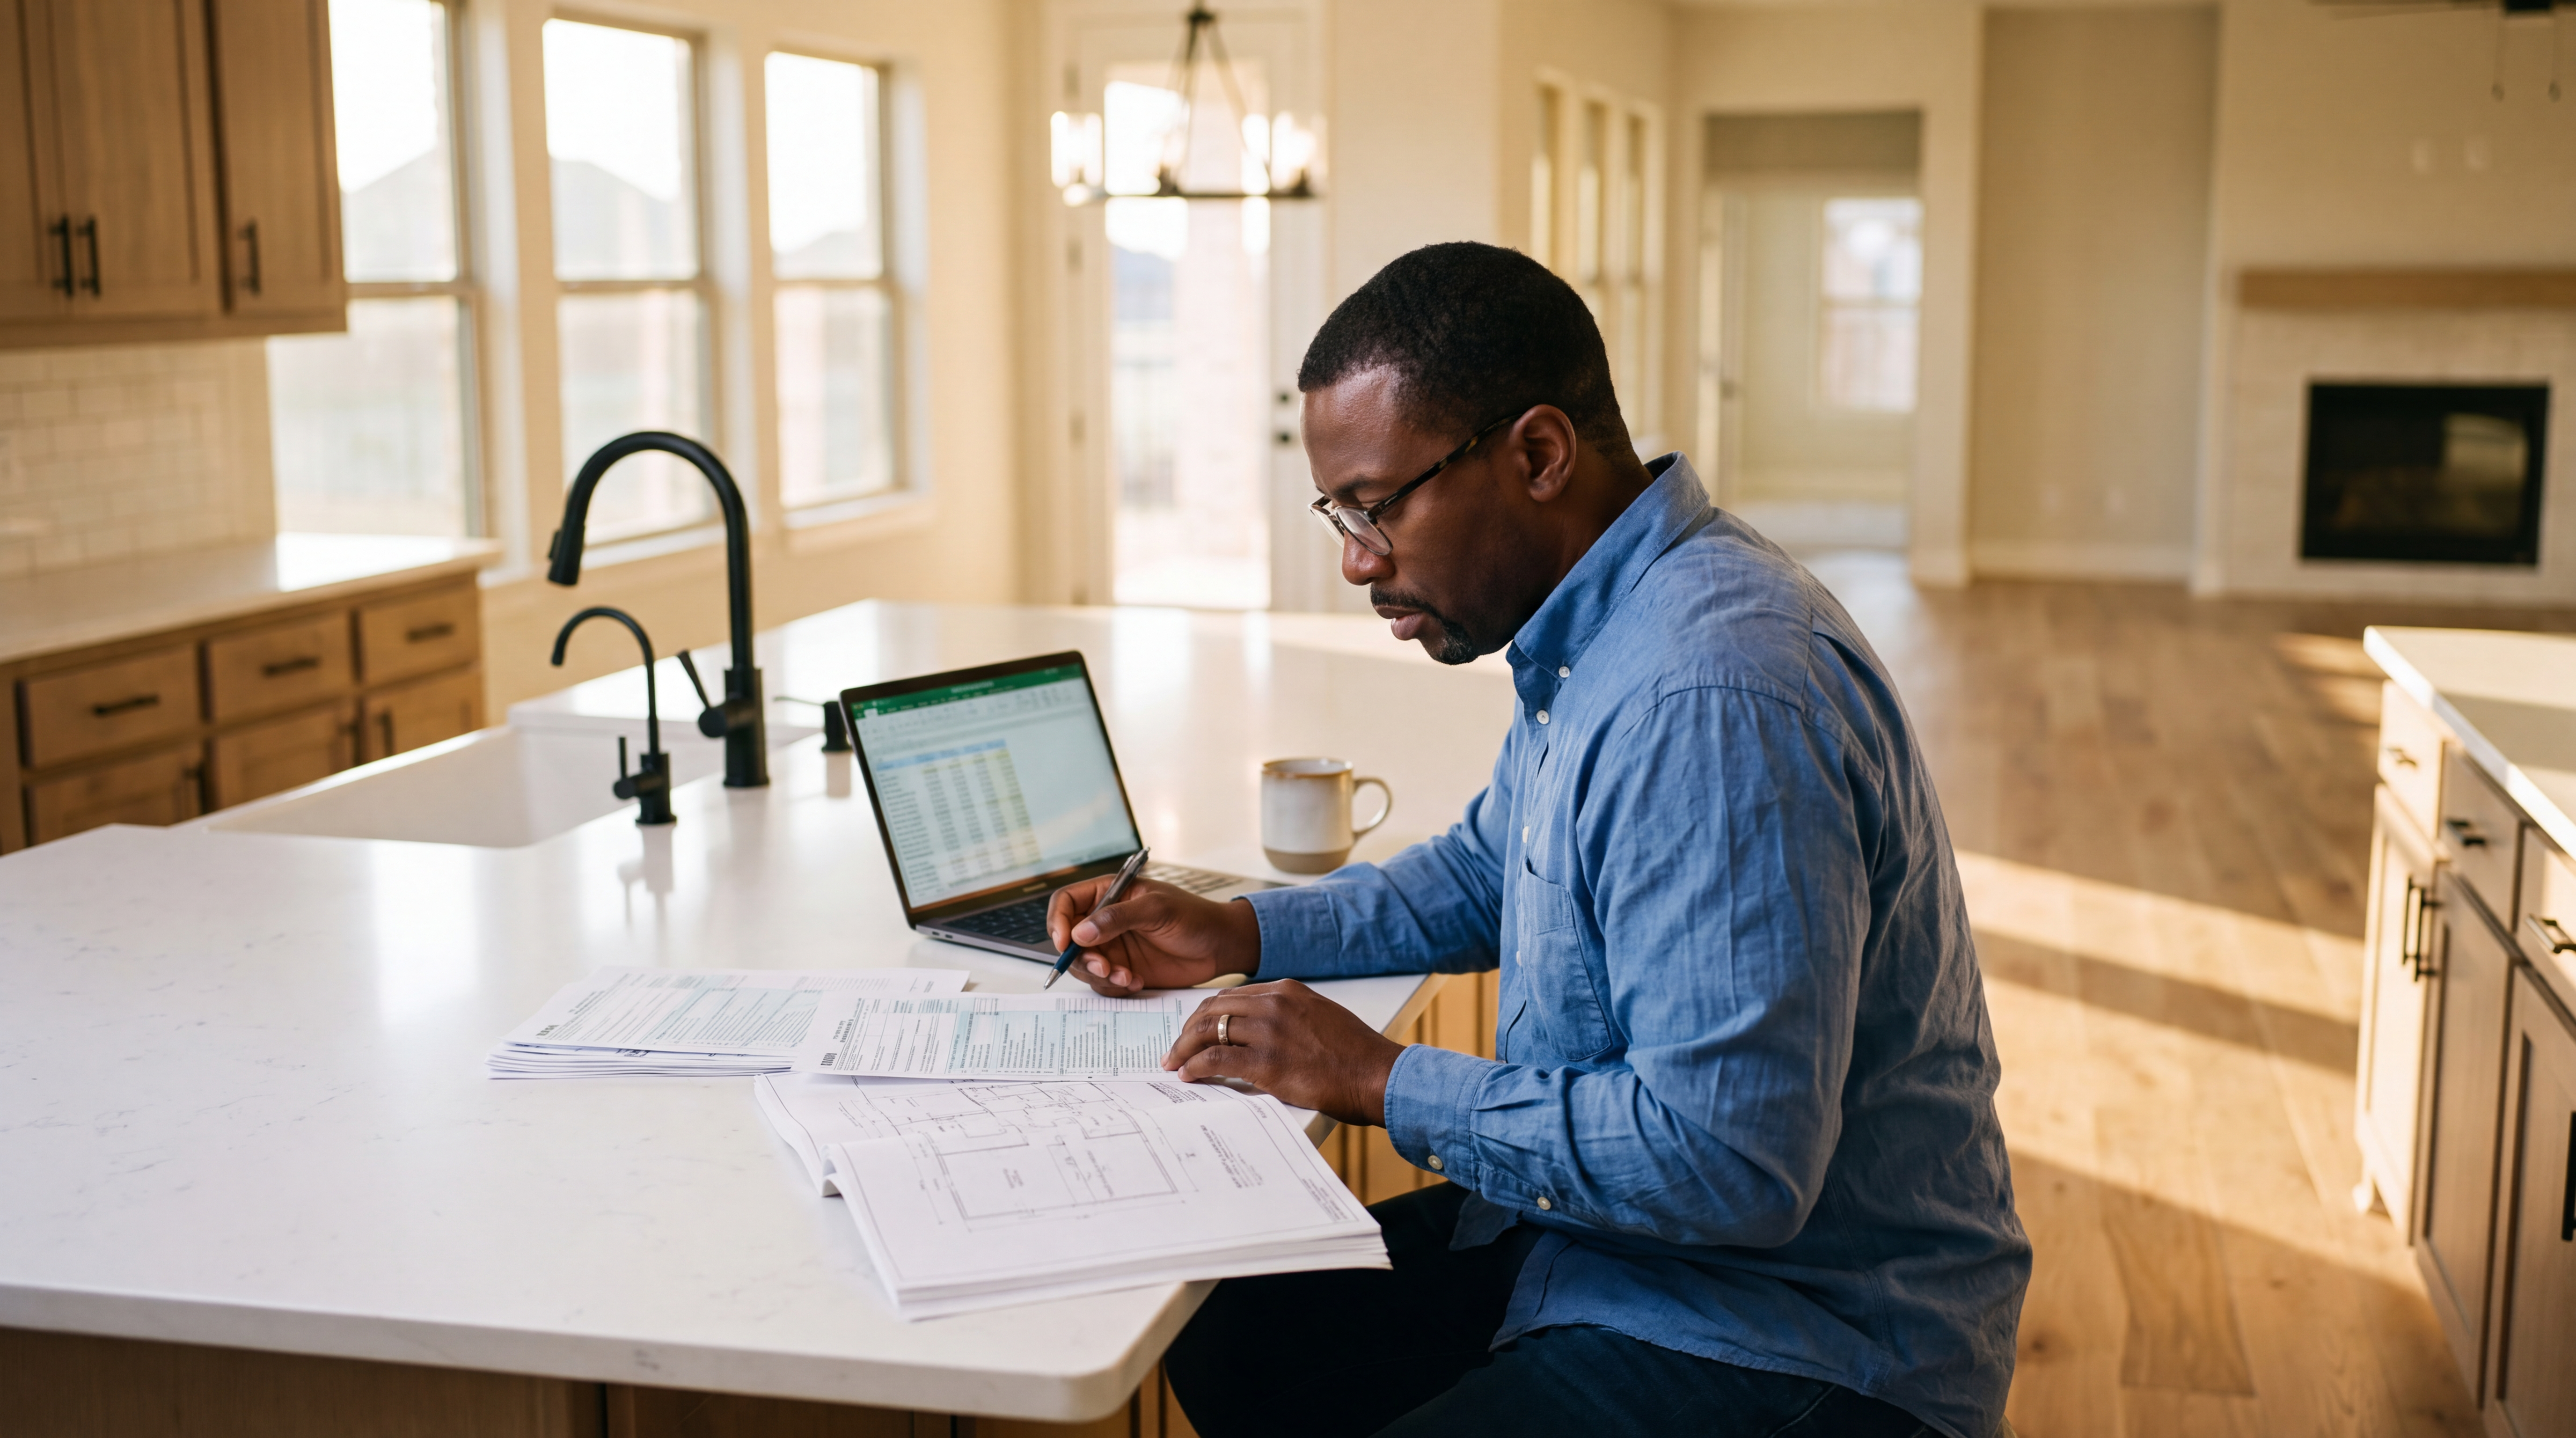
[Caption: A self-employed buyer reviewing two years of tax returns and a builder floor plan inside a Midlothian, TX new construction model home.]
You own a business or you get paid on a 1099. Your CPA spent years doing exactly what you hired them to do, which was drive your taxable income down. Then you walked into a model home off FM 663 in Midlothian, sat with the builder's preferred lender, and got handed a pre-approval number that looks nothing like your bank balance. That number is not a verdict on your finances. It is the output of one calculation, run one time, by someone whose paycheck comes from the builder.
Direct Answer
Lenders qualify self-employed buyers off net income, not gross revenue. Much of what your CPA deducted comes back through add-backs: depreciation, amortization, depletion, business use of home, and documented one-time expenses. In Midlothian, where new-construction pricing runs well above the citywide median, that gap often decides which floor plan you can sign for. Get a second read on your tax returns before you sign anything, and start with a real pre-approval review.
Community Spotlights: Where Self-Employed Buyers Are Building in Midlothian
The FM 663 and North Midlothian Corridor
This is the stretch most Dallas-based business owners find first. You are minutes from US-67, which puts downtown Dallas within a normal commute and Cedar Hill and DeSoto within fifteen minutes. Homes here feed Midlothian ISD, and attendance zone is one of the first things buyers check when they compare this corridor against continuing south. Bloomfield Homes and First Texas Homes both have active product here, with floor plans that run from entry-level to five-bedroom. For a self-employed buyer, the appeal is inventory depth. When twenty-plus builders compete in one city, you get negotiating room that a resale seller will not give you. Read the New Construction Buyer Guide before you tour.
GoodLand and the PID Communities
Several of Midlothian's newest master-planned communities, GoodLand among them, are built inside a Public Improvement District. A PID is a special assessment layered onto your property tax bill to pay for roads, sewer, and amenities. It is not a scam and it is not hidden. It is also not always disclosed early in a model home conversation, and it lands directly in your debt-to-income calculation. If you are self-employed and your qualifying income is already tighter than your lifestyle suggests, a PID assessment can be the line item that moves you down a floor plan. Ask for the assessment amount in writing before you write an earnest money check. Compare communities on the DFW new construction hub.
Downtown Midlothian and the Older Resale Pockets
Not every self-employed buyer should be in a new build. The older pockets around downtown Midlothian sit on bigger lots, carry no PID, and price below the new-construction median. If your qualifying income comes in lower than you hoped after the underwriter runs your returns, this is where you go instead of walking away from Midlothian entirely. The tradeoff is condition and age, and you pay for those in maintenance rather than in assessments. Track what is actually active in both pockets on the Lone Star Living App.
Pro Tip: If you buy new construction in Midlothian with my team representing you, ask about the New Construction Rebate Program before you register at a single model home. Registration order matters more than most buyers realize.
Local Market Trends (Fall 2026)
Based on current conditions:
- Midlothian citywide median sale price: about $475,000, up roughly 5.6% year over year (Source: Zillow and Redfin, May 2026)
- Midlothian new-construction median sale price: roughly $519,000 to $560,000, with one 2026 reading at $559,920 across 679 new homes (Source: NewHomeSource, 2026)
- Median days on market: about 116 days, among the slowest in South DFW (Source: Redfin, 2026)
- 30-year fixed mortgage rate: 6.95% as of September 17, 2026, up from 6.76% the prior week and 6.71% on September 3 (Source: Freddie Mac PMMS, September 2026)
- Active builders with projects in Midlothian: 27 (Source: NewHomeSource, 2026)
Read those two numbers together. A 116-day median means Midlothian sellers are waiting, and they are waiting because twenty-seven builders are competing against every resale listing in town with incentive money resale sellers cannot match. That works in your favor, and it is the reason a weak pre-approval hurts more here than it would in a faster market. You lose the negotiation before you ever lose the house.
"Most self-employed buyers I meet in Midlothian are not short on money. They are short on documentation. Those are two completely different problems, and only one of them takes six weeks to fix." — Steven J. Thomas, Broker at Refind Realty DFW and Loan Officer at Envision Home Lenders
How Lenders Actually Calculate Your Self-Employed Income
You are self-employed in the eyes of an underwriter if any of these is true: you own 25% or more of a business, you receive 1099 income, or you report income on Schedule C. That threshold comes straight from the Fannie Mae Selling Guide, section B3-3.2-01. A W-2 job on the side does not exempt you. If you cross that line, your file gets underwritten differently from your neighbor with one employer and one pay stub.
For conventional and FHA financing, the lender generally wants two years of signed personal federal tax returns with every schedule attached, plus two years of business returns if your entity files separately. Fannie Mae does allow a one-year exception when your most recent returns reflect a full twelve months of self-employment income and the file documents prior earnings at the same or greater level in the same field. That exception exists. It is not the default, and you should not plan around it without talking to your loan officer first.
Then the underwriter runs a cash flow analysis, usually on Fannie Mae Form 1084. That form walks your return line by line and lands on a monthly qualifying income figure. The starting point is net income, not the deposits in your operating account and not your gross receipts. Every write-off your CPA took reduced that starting point. Some of those write-offs come back. Some do not.
The Add-Backs You Get, and the Ones You Don't
Add-backs exist because certain deductions lowered your taxable income without lowering your cash. Form 1084 restores them. The standard list includes:
- Depreciation
- Amortization
- Depletion
- Casualty loss
- Business use of home, including the home office depreciation portion
- The depreciation portion of the standard mileage deduction
- Documented one-time, non-recurring expenses
What does not come back is ordinary operating expense. Your phone, your software, your subcontractors, your insurance, your fuel. Those were real dollars that left the account, and no underwriter is going to pretend otherwise.
Here is an illustrative example. It is not a quote, an approval, or an offer of credit. Say your Schedule C shows $96,000 of net profit. Your depreciation line is $18,000. Business use of home is $4,800. Both add back. You are now at $118,800, or $9,900 a month instead of $8,000. At the debt-to-income ratios most conventional programs allow, that difference can move your Midlothian budget by a full price tier. Your actual numbers will be different. Rates, guidelines, and program terms change, and nothing here is an approval.
This post is general information, not tax or legal advice. Confirm anything that touches your return with your CPA before you act on it.
Bank Statement Loans: What They Are, and What They Really Cost
If the tax return math still comes up short, the next stop is a bank statement loan. These are non-QM products, which means they sit outside the qualified mortgage rules and are not sold to Fannie Mae or Freddie Mac. Instead of your returns, the lender qualifies you off 12 to 24 months of business or personal bank deposits and applies an expense factor to estimate net income.
Typical requirements run a credit score in the 620 to 660 range or higher, 10% to 25% down depending on score and program, and two years of documented self-employment history. Bankrate's overview of bank statement loans covers the mechanics in more detail.
Now the part the ads skip. Bank statement loans price higher than conventional. The lender is taking on more risk and holding more of it, and you pay for that in the rate, the down payment, or both. The spread moves constantly and varies by lender, credit profile, and loan size, so anyone quoting you a fixed premium without pulling your file is guessing. What I will tell you plainly is this: run the conventional math first. If your add-backs get you there, take the conventional loan. A bank statement loan is the right answer when it is the only answer, and you can start that comparison here.
The Document Set to Have Ready Before You Walk Into a Midlothian Model Home
Gather this before you tour. Not after you fall for a floor plan.
- Two years of signed personal federal tax returns, all schedules, no pages missing
- Two years of business returns if your entity files separately, including K-1s
- Year-to-date profit and loss statement and balance sheet
- Two to three months of personal bank statements
- Twelve to twenty-four months of business bank statements if a bank statement loan is on the table
- Business license, or a CPA letter confirming the business exists and you own it
- Proof of the ownership percentage in the entity
- 1099s for the past two years
- Documentation for any large or irregular deposit in the last 60 days
- A written list of every one-time expense you want considered as an add-back, with support
That last one is the item almost nobody brings, and it is the one that moves the number. If you took a one-time write-off for equipment, a buildout, or a legal settlement, the underwriter will not assume it was non-recurring. You have to prove it. Bring the stack to an appointment and we will go through it line by line before a builder ever sees your file.
Cost Breakdown for Midlothian New-Construction Buyers
Based on current conditions, plan for these line items on top of the base price:
- Lot premium: $5,000 to $40,000 depending on greenbelt, corner, or cul-de-sac position
- Design center upgrades: commonly 5% to 10% of base price once flooring, cabinets, and fixtures are selected
- PID assessment, where applicable: an annual charge on your tax bill that varies by community and directly reduces your qualifying loan amount
- Earnest money: typically 1% to 2% of contract price with production builders, often non-refundable after the design phase
- Structural options: staged deadlines, usually locked before the slab pours
- Rate lock extension fees: relevant when a build slips past your original lock window
For a self-employed buyer, the design center is where budgets break. Your qualifying income was calculated on a specific loan amount. Every upgrade you add after contract either comes out of pocket at closing or pushes you back into underwriting for a larger loan on the same income. Decide the ceiling before you walk into that appointment.
Builder and Community Insights: Know Who the Preferred Lender Works For
Midlothian has 27 builders with active projects, including John Houston Homes, Bloomfield Homes, First Texas Homes, Perry Homes, and Highland Homes (Source: NewHomeSource, 2026). Incentives across the market have been running roughly $15,000 to $40,000, structured as rate buydowns, closing cost help, or upgrade packages (Source: NewHomeSource, 2026). Those offers change by community and by quarter.
Most of that incentive money is tied to using the builder's preferred lender. That arrangement is legal. Under RESPA a builder cannot require you to use a specific lender, but it can condition an incentive on that choice, and most of them do. What matters is understanding the relationship. The preferred lender's client is the builder. Their job is to get the builder's contract to close. When they run your Schedule C and hand back a number, they are not motivated to spend four extra hours hunting add-backs that would let you buy from a competitor down the road.
I am on both sides of this. I hold a Texas broker license and an active NMLS license, which means I read your tax returns myself and I represent you in the contract. I am not asking you to skip the builder's lender. Use their quote. Then let me run the same file and tell you what I get. If their number is better, take it and keep the incentive. Ask about the New Construction Rebate Program while you are at it, since at most communities using my team as your buyer's agent does not cost you the builder's incentive. Confirm the registration policy with each builder in writing before your first visit.
Financing and Incentives That Work for Self-Employed Buyers
Start with the rate environment. Freddie Mac put the 30-year fixed at 6.95% as of September 17, 2026, up from 6.71% on September 3 (Source: Freddie Mac PMMS, September 2026). In a market moving that fast, a builder rate buydown carries real value, and that is exactly why builders use it to steer you toward their lender. Price the buydown against the loan you would get elsewhere over the full time you expect to own the home, not over the teaser period.
Second, sequence matters. Get your income calculated before you shop, not after. A self-employed file that goes to underwriting cold takes longer, and in a Midlothian market where a build can take six to nine months, a surprise in month five is expensive. If your add-backs are documented up front, your loan officer can tell you the ceiling and you can shop inside it.
Third, know your fallback. If conventional does not reach and a bank statement loan prices too high, options include a larger down payment, paying down a business debt that is hitting your ratios, adding a co-borrower with W-2 income, or waiting one tax year and filing with a different deduction strategy. That last one is a conversation with your CPA and your loan officer together, and it should happen in the fall, not in March. See where you stand before the next tax year closes.
Conclusion
Your tax return was built to minimize taxes. It was never built to qualify you for a mortgage. Those two goals pull in opposite directions, and the gap between them is where most self-employed buyers in Midlothian get told no. Add-backs close part of that gap. Documentation closes more of it. A lender who reads your return instead of skimming the bottom line closes the rest. Midlothian has 27 builders competing for your contract and a 116-day median days on market, which means you have room to negotiate if you walk in with a pre-approval that reflects what you actually earn.
- Get your pre-approval reviewed by a licensed loan officer who reads the returns himself
- Explore buyer incentives and new construction rebates
- Download the Lone Star Living App to view Midlothian listings and track nearby activity
Book an appointment today. Call or text 972-846-9170.
Steven J. Thomas, Broker, Refind Realty DFW, TREC Broker License #0657467, Loan Officer, Envision Home Lenders, NMLS #689220. Equal Housing Opportunity. Information is general and based on current conditions as of September 2026. Rates and guidelines change and nothing here is an offer of credit, a rate quote, or a guarantee of approval.
You're Always Home with Steven J. Thomas.
Key Takeaways
- You are self-employed for mortgage purposes if you own 25% or more of a business, receive 1099 income, or file a Schedule C, per the Fannie Mae Selling Guide B3-3.2-01.
- Qualifying income starts at net income, then adds back depreciation, amortization, depletion, business use of home, and documented non-recurring expenses through Fannie Mae Form 1084.
- Midlothian's new-construction median has run roughly $519,000 to $560,000 in 2026 against a citywide median near $475,000, so the financing gap shows up faster here than in a resale-only market (Source: Zillow, Redfin, and NewHomeSource, 2026).
- A bank statement loan qualifies you off 12 to 24 months of deposits with typical requirements of a 620 to 660 credit score and 10% to 25% down, and it prices higher than conventional. Run the conventional math first.
- Bring two years of returns with all schedules, a year-to-date P&L, and a written list of one-time expenses to your first appointment. Track active Midlothian inventory on the Lone Star Living App while your file is being reviewed.
FAQ: Self-Employed Mortgages and New Construction in Midlothian, TX
When should a self-employed buyer get pre-approved before touring Midlothian model homes?
Get your income calculated before you tour, not after you pick a floor plan. A self-employed file takes longer to underwrite, and builders in Midlothian ask for a pre-approval letter at registration.
How do lenders calculate income for a self-employed buyer?
Lenders start with net income from your tax returns, then add back non-cash deductions like depreciation, amortization, depletion, and business use of home using Fannie Mae Form 1084. Ordinary operating expenses do not add back.
What happens if my tax returns do not support the loan I need?
Your options include a bank statement loan, a larger down payment, paying down business debt that is affecting your ratios, adding a co-borrower with W-2 income, or adjusting your deduction strategy for the next tax year with your CPA. None of these guarantees approval.
Should I use the builder's preferred lender in Midlothian?
Get their quote, because most builder incentives are tied to it, then have an independent loan officer run the same file. The preferred lender works for the builder, and a second calculation of your add-backs costs you nothing.
How long does a self-employed mortgage take to close on a Midlothian new build?
Plan on a longer underwriting window than a W-2 borrower, and remember a Midlothian build often runs six to nine months from contract. Timelines vary by lender, builder, and file, so confirm dates in writing.
Where can I see current Midlothian new construction and resale listings?
Midlothian has 27 builders with active projects plus resale inventory sitting at a roughly 116-day median days on market. Download the Lone Star Living App to see what is active right now.
BLOG NAVIGATION
Contact Me By Filling Out
The Form Below
We Can Help You Reach Your Real Estate Goals!
Locate Us
Site: www.stevenjthomas.com
Call :(972) 846-9170
Email: [email protected]
Office 128 S. Cockrell Hill Rd, DeSoto TX 75115
Owned and Operated by Thomas & Thomas Financial Group, LLC
© Copyright 2026 | All Rights Reserved
Steven J. Thomas, REALTOR® · TREC License #0657467
Privacy Policy | Terms of Service | Fair Housing Statement
Refind Realty DFW · 128 S. Cockrell Hill Rd, DeSoto, TX 75115 · (972) 846-9170
Facebook
Instagram
X
LinkedIn
Youtube
TikTok