You're Always At Home With Refind Realty.
Serving Your DFW Real Estate Needs Since 2005.
Refind Realty Inc is a Black-owned independent brokerage in DeSoto, in business since 2005. Steven J. Thomas is an owner and associate broker of Refind Realty Inc and leads its Refind Realty DFW division.
We Help You Buy and Sell in The Greater Dallas-Fort Worth Area.
Check Out Our Social Media Channels!
Buying in DFW
Buying your first or next home should be a rewarding and exciting time in your life, and one that you look back on with fond memories.
Thinking Of selling?
The market has changed a lot and I'd love to show you the exact strategy I use to get sellers in DFW top dollar for their property.
Get Pre-Approved
Let me walk you through the entire pre-approval process so you know exactly how much home you can afford.
Sign Up For my
Email List
My emails are a great way to stay up-to-date with local news and real estate market trends, even if you're not currently in the market. So, come on and join me to stay in the loop!
affordability Calculator
Get pre-approved to know exactly how much house you can afford. Use this calculator to get a quick estimate. Contact me for assistance!
DFW New Construction
Discover the latest new home constructions in DFW and take advantage of the builder incentives that are available now.
Let's Make Your real estate Dreams Come True.
Newest Listings
Call Me Today At (972) 846-9170
Refind Realty Blog:

Why Do Home Sales Fall Through in Dallas-Fort Worth?
Last updated November 19, 2026
Why do home sales fall through in Dallas-Fort Worth?
About one in six Dallas-area home sales under contract falls through. In July 2026, 16.3% of pending sales in the Dallas metro and 18.1% in Fort Worth fell out of contract, against 14% nationwide (Redfin, August 2026). The usual causes are inspection problems, financing trouble and a low appraisal. A Texas buyer can protect against all three before signing.
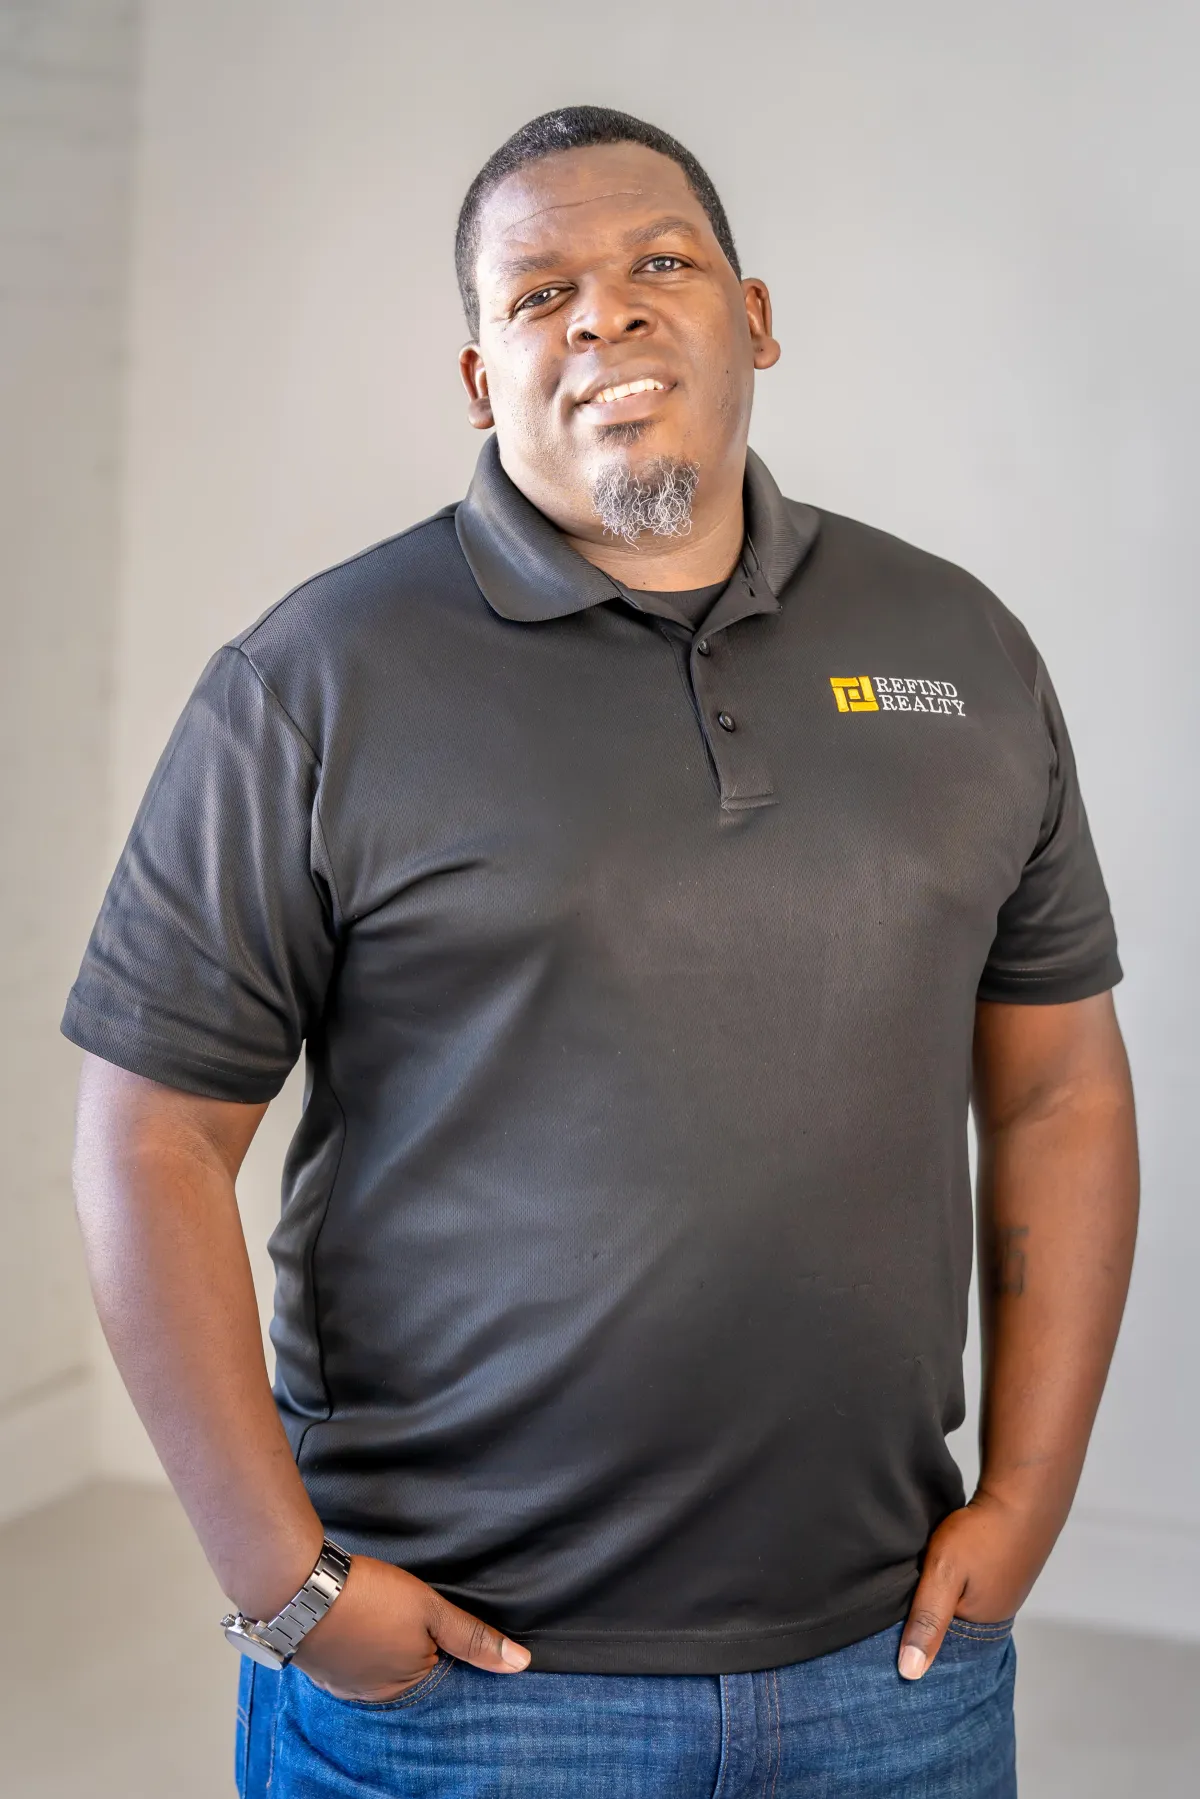
Steven J. Thomas, Broker, Refind Realty DFW · Loan Officer, Envision Home Lenders, NMLS #689220. Baylor financial planning degree, 20+ years in financial services.
How often do home sales fall through in Dallas?
More often than most of the country. Redfin counted 16.3% of Dallas-metro pending sales falling out of contract in July 2026 and 18.1% in Fort Worth. The national share was 14%, the highest in nearly three years. Redfin measures pending sales that fall out of contract as a share of all pending sales, using MLS data.
| Market | Pending sales that fell out of contract, July 2026 | Change from a year earlier |
|---|---|---|
| Fort Worth metro | 18.1% | +1.3 pts |
| Dallas metro | 16.3% | +0.6 pts |
| United States | 14.0% | Highest in nearly three years |
Source: Redfin, "With Buyers Firmly in the Driver's Seat, Home-Purchase Cancellations Hit Highest Level in Nearly 3 Years," published August 21, 2026. Seasonally adjusted MLS pending-sales data.
What are the most common reasons a home sale falls through?
Redfin lists inspection issues, financial challenges and major life changes as the reasons buyers back out. In practice, most failed DFW deals trace back to one of four things: an inspection finding, a loan that doesn't close, an appraisal below the price, or a buyer who never ran the full payment before signing.
- Inspection findings. A foundation, roof or HVAC problem shows up, and the buyer and seller can't agree on a repair or credit.
- Financing. The lender can't approve the loan because income, debt or credit changed, or was never fully checked.
- Appraisal. The appraisal comes in below the contract price, and nobody covers the gap.
- Payment shock. The buyer sees taxes and insurance added to principal and interest and backs out.
Why are more DFW buyers backing out now?
Buyers have more homes to choose from and less pressure to stay in a deal. DFW single-family pending sales fell 23% in October 2026, while homes for sale held at 31,752 (NTREIS, October 2026). DFW homes closed at 93.7% of list after a median 66 days. When another house is easy to find, a buyer who hits a problem in the option period walks instead of negotiating.
Rates add pressure. The 30-year fixed averaged 7.11% on November 12, 2026, against 6.24% a year earlier (Freddie Mac PMMS). A buyer who signs without a locked rate or a full approval can see the payment change before closing.
How do I keep my home purchase from falling through?
Do the financing work before you write the offer, and use the protections already in the Texas contract. Here is the order I walk buyers through:
- Get fully approved, not just pre-qualified. A lender who has reviewed your income, assets and credit before you shop catches the problem that would kill the loan at day 25.
- Run the full payment. Principal, interest, property taxes, insurance and HOA, on the actual address. Texas taxes and insurance are a large share of the real payment.
- Use the option period. The TREC resale contract lets you pay an option fee for an unrestricted right to terminate during a set number of days. Schedule the inspection on day one.
- Read the financing addendum. The Third Party Financing Addendum lets a buyer end the contract if the loan isn't approved within the days you write in. Pick a number your lender can meet.
- Decide on appraisal protection up front. TREC's Addendum Concerning Right to Terminate Due to Lender's Appraisal gives a buyer an exit if the appraisal comes in low. Leaving it out can make an offer stronger, but only if you have cash to cover a gap.
- Don't change your credit until closing. No new car, no new card, no job change without calling your lender first.
You can read the TREC One to Four Family Residential Contract (Resale) on the Texas Real Estate Commission site before you ever make an offer.
Start with step one. Get pre-approved in minutes so you know your number before you fall for a house.
More reading before you shop: how DFW buyers use the Texas option period, what a late builder closing does to your rate lock, whether to buy a house during the holidays in DFW, and why Cedar Hill asking prices run far above sold prices.
FAQ: when a DFW home purchase falls apart
Do I lose my earnest money if the sale falls through?
It depends on why and when. If you terminate within the option period, or under a contingency like the financing addendum and you follow its deadlines, the contract provides for your earnest money to come back. If you back out without a contract right, you can lose it. Read the contract with your agent before you sign.
Do I get my option fee back?
Usually not. The option fee buys you the right to terminate, and the seller keeps it. In the TREC resale contract, the option fee is credited to you at closing if the sale goes through.
Can the seller back out of a home sale in Texas?
A seller has far fewer exits than a buyer under the TREC resale contract. The option period and the financing addendum are buyer protections. A seller who refuses to close without a contract right can face a breach claim. Talk to a real estate attorney if that happens.
Is a pre-qualification enough to make an offer?
It gets you in the door, but it is the weak spot in many failed deals. A pre-qualification is often based on what you told the lender. A full approval checks documents. Ask your lender which one you have before you write an offer.
Where does this data come from?
Cancellation rates come from Redfin's analysis of seasonally adjusted MLS pending sales, published August 21, 2026, covering July 2026. DFW pending sales, inventory, days on market and sold-to-list come from the NTREIS Monthly MLS Summary Report for October 2026. Rates come from Freddie Mac's Primary Mortgage Market Survey of November 12, 2026.
About the author
Steven J. Thomas holds a financial planning degree from Baylor University and has more than 20 years in financial services. He is the Broker at Refind Realty DFW (TREC Broker License #0657467) and a Loan Officer at Envision Home Lenders (NMLS #689220), based in DeSoto, TX. Call or text 972-846-9170.
Information is general and based on current conditions. It is not legal advice, a loan commitment, or a guarantee of approval, rates or outcomes. The Texas Real Estate Commission's Information About Brokerage Services and Consumer Protection Notice are available on request. Refind Realty DFW is an equal housing opportunity business. Steven J. Thomas, NMLS #689220, Envision Home Lenders. Equal Housing Lender.
Stay Informed With My Downloadable
Buyer and Seller guides

6 Smart Ways to Build Home Equity

7 Insider Secrets To Selling Your Home w/o a Lot of Time or Money

DFW Home Seller Negotiation Secrets

Home Appraisals Guide

Avoiding Pitfalls That Can Derail Your Home's Sale

Ultimate Guide To Buying a Home

A First Time Homebuyers Guide In DFW

Are You Ready To Buy?

25 Insider Secrets To Buying A Home

How to Improve Your Credit
Download All My Guides For Free
Steven J. Thomas
Steven J. Thomas has been in the financial services industry for the past 19 years and started my career as a Financial Planner for American Express Financial Advisors. I entered into banking with JP Morgan Chase as personal banker in 2003 and was promoted several times up to Small Business Specialist. I earned multiple Million Dollar Club awards and was ranked in the top 5 Small Business Specialist before I branched out in 2005 to start my own Financial Management Company. I ran a successful company before family circumstances lead me to Wachovia Bank in 2008 where I worked as a Senior Financial Specialist. As a Sr. Financial Specialist; I was responsible for the P & L and revenue growth of my banking center. The elimination of my role thru a bank merger lead me to BBVA Compass. I have held various leadership roles at BBVA Compass including Personal Relationship Manager, Branch Retail Executive, Workplace Solutions VP, and his current role as a Retail Manager. As the Regional Workplace Solutions VP, I was responsible for the strategic, tactical, and execution of Partnership Banking relationships, promotion and activity with corporate and non-profit companies in my footprint. I was responsible for the acquisition production for three districts, which includes 51 banking centers and over 300 employees. In May of 2014, I joined the team at Refind Realty and became one of the managing partners in mid-2015.
Wondering What Your DFW Home Could Be Worth in2026?
Get a Professional Home Valuation From A Local Market Expert
Unlock insights into potential selling prices.
Get a personalized analysis sent directly to your inbox.
Stay ahead with updates on property value fluctuations.
Benchmark your property against neighborhood listings.
Get a FREE Home Valuation And Potential Net Sheet:
I used this realtor and it was a great experience. He was patient and very helpful with our journey. He also helped us find a great lender with little hassle on the process, also got us approved for well above the market of our original home so we were able to get more house with a lower mortgage rate. So to anyone who is interested in buying a home take my advice give Steven a call. It’s worth it 😁
Bryant Loring

Steve was absolutely amazing! Everything was easy! Very professional in all aspects. Punctual, responsive, and diligent. He goes above and beyond to ensure you get to see as many homes as you’d like no matter the location. Not only was he knowledgeable about home buying, he also has a resourceful network for new home owner needs. I recommend Refind Realty to everyone!
Nicholas Bishop
I definitely recommend Steven to assist with your home buying needs. As a first time home buyer the process can be overwhelming, but as my realtor he was knowledgeable & patient while addressing my concerns and assisting me with my new home purchase. Thanks again Steven!! :-)
Gayle Mason
Ask Us Anything
Frequently Asked Questions
Why do you need a Realtor?
When buying or selling a home, there are so many options…which can also present a lot of obstacles. Laws change, forms change, and practices change all the time in the real estate industry. Because it’s our job to stay on top of those things, hiring a realtor reduces risk, and can also save you a lot of money in the long run.
When you work with me as your Realtor, you’re getting an expert who knows the area; knows how to skillfully guide your experience as a seller or buyer; can easily spot the difference between a good deal and a great deal. My job is to translate your dream into a real estate reality, and I work hard to earn and keep my business. This also means earning your trust: When you work with me, you’ll be working with a realtor who looks out for your best interests and is invested in your goals.
Which loan should you choose?
There are two different types of loans conventional loans and government-backed loans. The main difference is who insures these loans:
1 - Government-backed loans (FHA, VA and USDA):
(a) - Are, unsurprisingly, backed by the government.
(b) - Include FHA loans, VA loans, and USDA loans.
(c) - Make up less than 40 percent of the home loans generated in the U.S. each year.
2 - Conventional loans
(a) - Are not backed by the government.
(b) - Include conforming and non-conforming loans (such as jumbo loans).
(c) - Make up more than 60 percent of the loans generated in the U.S. each year.
What is the difference between FHA, VA and USDA loans?
1 - FHA LOANS:
FHA loans, which are insured by the Federal Housing Administration, are typically designed to meet the needs of first-time homebuyers with low or moderate incomes. FHA loans can be approved with a down payment of as little as 3.5 percent and a credit score as low as 580.
FHA loans are often called “helper loans,” because they give a leg up to potential borrowers who may not be able to secure one otherwise. For this reason, FHA loans have maximum lending limits, which are determined based on housing values for the county where the for-sale home is located.
Because the agency is taking on more risk by insuring FHA loans, the borrower is expected to pay mortgage insurance both at the time of closing and on a monthly basis, and the property must be owner-occupied.
2 - VA LOANS:
VA loans are backed by the Department of Veterans Affairs and they are guaranteed to qualified veterans and active-duty personnel and their spouses. VA loans can be approved with 100 percent financing, meaning VA borrowers are not required to make a down payment.
Unlike FHA loans, borrowers do not have to pay mortgage insurance on VA loans.
3 - USDA LOANS:
You may also hear about USDA loans, which are backed by the United States Department of Agriculture mortgage program. USDA loans are intended to support homeowners who purchase homes in rural and some suburban areas. USDA loans do not require a down payment and may offer lower interest rates; borrowers may have to pay a small mortgage insurance premium in order to offset the lender’s risk.
What’s a conventional loan? Understanding what it means to be conforming and non-conforming
Buyers who have a more established credit history and a larger down payment may prefer to apply for a conventional loan. These loans may offer a lower interest rate and only require the home buyer to purchase monthly mortgage insurance while the loan-to-value ratio is above a certain percentage, so a conventional loan borrower can typically save money in the long run.
Conventional loans are divided into two types: Conforming loans and non-conforming loans.
1 - CONFORMING LOANS:
Conforming loans are those that meet (or conform to) predetermined standards set by Fannie Mae and Freddie Mac — two government-sponsored institutions that buy and sell mortgages on the secondary market. By selling the loans to "Fannie and Freddie," lenders can free up their capital and return to issue more mortgages than if they had to personally back every loan that they approve.
The main standard for conforming loans is that the amount borrowed must be under a certain amount; in Alaska, a single-family home loan must be under $647,200 in order to be considered conforming.
Properties with more than one unit have higher limits.
2 - NON-CONFORMING (JUMBO) LOANS:
But what happens if a borrower wants to borrow more than the Freddie- and Fannie-approved loan amount? In this case, they would have to apply for a “jumbo loan,” which is the most common type of non-conforming loan.
Because the lender cannot resell the jumbo loan (or any non-conforming loan) to Freddie Mac or Fannie Mae, jumbo loans are considered to be riskier than a conforming loan. To protect against this risk, the bank will typically require a higher down payment; the interest rate on a jumbo loan may also be higher than if the same borrower applied for a conforming loan.
What kind of rate should you choose?
Rate types: Fixed-rate vs. adjustable-rate mortgages.
In addition to the loan type you choose, you’ll also have to determine if you want a fixed-rate mortgage or an adjustable-rate mortgage (ARM). A fixed-rate mortgage has an interest rate that does not change for the life of the loan, so it provides predictable monthly payments of principal and interest.
An adjustable-rate mortgage typically offers an initial introductory period with a low-interest rate. Once this period is over, the interest rate adjusts periodically, based on the market index. The initial interest rate on an ARM can sometimes be locked in for different periods, such as one, three, five, seven, or 10 years. Once the introductory period is over, the interest rate typically readjusts annually.
Locate Us
Site: stevenjthomas.com
Call :(972) 846-9170
Email: [email protected]
Office 128 S Cockrell Hill Rd, DeSoto, TX 75115
Refind Realty Inc · Broker of record: Natasha Martini Martinez
© Copyright 2026 | All Rights Reserved
Steven J. Thomas, Owner and Associate Broker · TREC #0657467 · NMLS #689220 · Equal Housing Opportunity
Privacy Policy | Terms of Service | Fair Housing Statement | Texas Real Estate Commission Information About Brokerage Services | Texas Real Estate Commission Consumer Protection Notice
Refind Realty Inc · 128 S Cockrell Hill Rd, DeSoto, TX 75115 · (972) 846-9170
Facebook
Instagram
X
LinkedIn
Youtube
TikTok