You're Always At Home With Refind Realty.
Serving Your DFW Real Estate Needs Since 2005.
We Help You Buy and Sell in The Greater Dallas-Fort Worth Area.
Check Out Our Social Media Channels!
Buying in DFW
Buying your first or next home should be a rewarding and exciting time in your life, and one that you look back on with fond memories.
Thinking Of selling?
The market has changed a lot and I'd love to show you the exact strategy I use to get sellers in DFW top dollar for their property.
Get Pre-Approved
Let me walk you through the entire pre-approval process so you know exactly how much home you can afford.
Sign Up For my
Email List
My emails are a great way to stay up-to-date with local news and real estate market trends, even if you're not currently in the market. So, come on and join me to stay in the loop!
affordability Calculator
Get pre-approved to know exactly how much house you can afford. Use this calculator to get a quick estimate. Contact me for assistance!
DFW New Construction
Discover the latest new home constructions in DFW and take advantage of the builder incentives that are available now.
Let's Make Your real estate Dreams Come True.
Newest Listings
Call Me Today At (972) 846-9170
Refind Realty Blog:
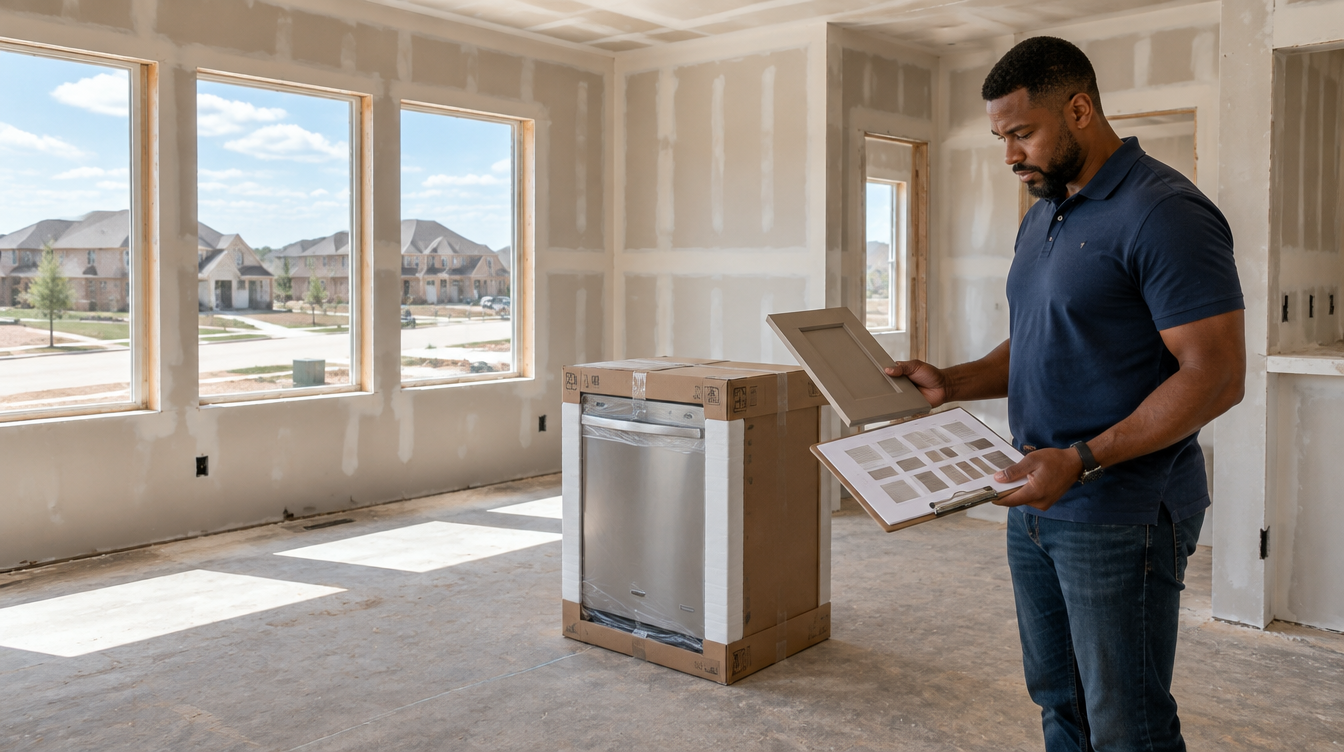
The Substitution Clause: What a DeSoto Builder Can Change After You Sign Your New Construction Contract (2026)
The Substitution Clause: What a DeSoto Builder Can Change After You Sign Your New Construction Contract (2026)
By Steven J. Thomas
You walk through the model home off Castle Street in DeSoto, you love the kitchen, and a few weeks later you are signing a stack of paper at the sales desk. Buried in that stack is a short paragraph that lets the builder swap out some of what you just fell in love with. It is called the substitution clause, and it is the paragraph most buyers in DeSoto 75115 never read.
Direct answer: what can a builder change after you sign?
A substitution clause lets your builder replace materials, equipment, and appliances specified in your contract with items the builder considers comparable. In a DeSoto TX new construction contract, that power is usually broad, and the builder decides what comparable means. You will not get the clause deleted on a production build, but you can narrow it by getting every selection written into the contract documents by brand, model, and color.
Steven's take: the rep in the model home works for the builder
That contract was written by the builder's attorneys to protect the builder. Not a scandal, just the job. But the friendly person walking you through the floor plan is paid by the seller, and the paperwork reflects whose side of the table it came from.
Here is the number that frames it. In August 2026, new construction in DFW averaged 79 days on market with roughly a $90,000 average gap between list price and sold price, according to the North Texas Market Insider report published September 12, 2026, citing NTREIS. Tens of thousands of dollars move on a new build between the model home visit and the closing table. Bring your own agent, because the builder already prices the co-op into the deal, and get every selection in writing with brand, model, and color.
What the substitution clause actually says
Start with the promulgated form. The Texas Real Estate Commission's New Home Contract (Incomplete Construction) includes this line in Paragraph 7:
"Seller may substitute materials, equipment and appliances of comparable quality for those specified in the Construction Documents."
That same form defines Construction Documents as the plans and specifications, finish out schedules, change orders, and allowances. It requires all change orders to be in writing, and it says buyer selections must conform to the seller's normal standards. So even the state's own form grants substitution rights, with the Construction Documents as the boundary.
Large production builders generally use their own purchase agreement instead, and those are typically broader. One builder purchase agreement filed publicly with the SEC in 2023 permits substitution without notice to the buyer, of items of comparable quality, utility or color as the seller might deem appropriate, and limits the buyer's remedy for a missing option to the builder's cost of that item. If an option never gets installed, what you get back can be tied to what it cost the builder, not what you paid.
Why builders include it
The clause is not there to annoy you. A house takes months and the supply chain does not hold still that long.
- Manufacturers discontinue product lines mid-build, and the tile in the model stops existing
- Appliance and window lead times stretch, and waiting pushes your closing out
- Codes and energy requirements change between permit and framing
- The builder switches vendors when a supplier cannot deliver
The problem is not the clause. It is how much room the word comparable leaves.
What comparable means in practice
Nobody defines it, which is the point. The Fine Print Homes explainer on material substitution clauses notes these provisions let the builder swap materials, fixtures, appliances, and finishes for alternatives the builder considers equivalent, that they are generally enforceable when the builder acts in good faith, and that courts may treat substantial deviations reducing value as a breach.
The Texas New Construction Guide from Move to Texas, July 2026, makes a related point about builder contract language: comparable, substantially similar, and equal or greater value all leave room for disagreement. They sound precise. They are not.
What gets swapped most often in DFW builds:
- Flooring, especially LVP and tile series that get discontinued
- Plumbing fixtures, faucets, and shower trim
- Appliance brands and model numbers inside a package
- Exterior brick and stone blends, and siding profiles
- Cabinet lines and stain or paint colors
- Window brands and glass packages
- Small plan details like a bench, a drop zone, or a niche
Substitution versus change order
These get confused constantly, and the difference decides who has to agree. A substitution is the builder using a right you already granted when you signed. It usually does not require your signature, and in some contracts it does not require notice. A change order is a documented modification both parties sign.
Move to Texas, July 2026, lays out what belongs on every change order: the exact change, the price, the payment deadline, whether it is refundable, the effect on schedule, and the effect on warranty, signed before work is performed. So push as much as you can into the change order and selection sheet world, where your signature is required.
Example: the $18,000 design center problem
This is a composite example, not a client file, and the numbers are illustrative.
A buyer spends $18,000 at the design center. Upgraded flooring, a cabinet upgrade, the kitchen package. The model showed a specific appliance brand and the buyer assumed that is what was coming. The contract line item reads stainless appliance package.
At the walkthrough, the appliances are stainless, they are a different brand, and the range has fewer features. What does the contract give you? Probably not much. The specification was satisfied, the builder's position is that it is comparable, and because the brand and model were never written into the Construction Documents, there is no specified item to compare against.
Run the same scenario with a selection sheet listing brand, model number, and finish, incorporated into the contract by reference. The builder still has substitution rights, but now comparable has something concrete to measure against.
DeSoto new construction communities where this comes up
Summit Parks
First Texas Homes is building at Summit Parks, 505 Castle Street, DeSoto 75115, with plans from roughly 2,775 to 4,427 square feet and pricing from $526,950, per NewHomeSource as of August 31, 2026. Quick move-ins were listed from $526,950 to $803,955 at the time of writing. Quick move-ins carry the most substitution exposure, because the builder made the selections before you showed up. Ask for the spec sheet on the home as built, not the plan brochure, and check it against the active DeSoto new construction listings.
Homestead at Daniel Farms
Bloomfield Homes is building at Homestead at Daniel Farms, 941 Palmer Lane, DeSoto 75115. Homes under construction were listed around $549,000 with November 2026 availability and $632,742 with January 2027 availability, per Zillow builder listings in September 2026. Prices and dates were listed at the time of writing and change. On a home already framed, materials may have been ordered before your contract existed, so get the as-built selection list.
Kentsdale Farms
Kentsdale Farms in DeSoto offers quarter-acre lots, ready-to-build plans from $459,000, and available homes listed from $496,925 to $564,395, listed by HomesUSA.com in August 2026. Ready-to-build gives you the most control, because nothing has been ordered yet. It is also where the selection sheet matters most, since everything you pick today is a line item somebody could substitute eight months from now.
Pro Tip: Before you sign anything at a sales office, read the New Construction Buyer Guide. It walks the contract sections that cost buyers money, including this one.
DeSoto and DFW market context, fall 2026
- DFW new construction: 79 average days on market, roughly a $90,000 average gap between list and sold price (Source: North Texas Market Insider, August 2026 report published September 12, 2026, citing NTREIS)
- DFW resale: 5.85 months of inventory, closing at 94.5% of original list after 58 days (Source: North Texas Market Insider, August 2026)
- DeSoto resale: 243 closings over six months, $348,000 median closing price, 31 median days from list to contract (Source: Resideline, August 2026)
- Mortgage rates: 30-year fixed at 6.76%, up from 6.71% the prior week and 6.35% a year earlier, 15-year fixed at 6.09% (Source: Freddie Mac PMMS, September 10, 2026)
Based on current conditions, DeSoto resale is moving faster than new construction, and that pace gap is why builders lean on incentives and design center upgrades. The more you spend at the design center, the more line items a substitution can touch.
"The contract is not the part buyers get excited about, and that is exactly why builders win there. Slow down on the paperwork and you protect the part you actually care about." Steven J. Thomas, Broker at Refind Realty DFW and Loan Officer at Envision Home Lenders
What to price out beyond the base price
Ask for the written dollar figure on each of these before you sign. Do not accept a verbal range.
- Lot premium, stated as its own line item
- Design center upgrades, itemized by brand, model, and color
- Allowances, and what happens to any unused balance
- MUD or PID assessments, and how long they run
- Earnest money and design center deposits, and which portions are refundable
- Change order pricing and any per-order administrative fee
Every one of these is a number you can request in writing today. The ones you do not pin down are the ones that shift later.
Six ways to protect the selections you paid for
- Photograph the model. Every room, every fixture, every label, date-stamped. The model is a sales tool, not a spec, so your photos are the record of what you were shown.
- Specify brand, model, and color. Get the selection sheet written that way and incorporated into the contract by reference, so those items become part of the Construction Documents.
- Negotiate notice and approval rights. Ask for advance written notice of any substitution, plus approval rights above a dollar threshold you name. Builders do not always agree. Ask anyway, in writing.
- Keep a change order file. One folder, every signed change order, every email, every selection revision, signed before work is performed.
- Verify at pre-drywall and at the final walkthrough. Pre-drywall catches windows, framing, and rough plumbing. The final walkthrough catches fixtures, appliances, and finishes. Bring your photos to both.
- Document before closing and object in writing. If something was swapped without your consent, photograph it and put the objection in writing before you fund. Your position weakens sharply once you sign at the title company.
Builder and community notes for DeSoto buyers
Incentives vary by builder and change monthly, so anything you hear about a rate buydown or a design center credit needs to be confirmed in writing for your specific home and closing month. Current offers are tracked on the DFW builder incentives page.
Ask every builder three questions before you get attached to a floor plan. Does your contract require written notice before a substitution? What is the change order deadline for each construction phase? What happens to my earnest money if the appraisal or my financing does not come together?
One more piece of math. When Steven's team is your agent on a new build, the New Construction Rebate Program returns up to 1% back at closing, up to $10,000. That comes out of the co-op the builder already budgeted.
Financing, rates, and the part people forget
Substitutions can touch your loan. If an appraiser values the home on specified finishes and the delivered finishes are materially different, that shows up in the appraisal conversation. If a change order adds cost late in the build, that moves your loan amount and your cash to close.
With the 30-year fixed at 6.76% as of Freddie Mac's PMMS on September 10, 2026, up from 6.35% a year earlier, payment math is tighter than it was, and a preferred lender buydown can look very attractive on the flyer. Read the buydown terms the way you read the substitution clause. Compare against an outside quote, and see where you pre-qualify first. Rates change weekly, and nothing here is a quote or a promise of terms.
Why your own agent matters on a new build
Two things are true at once. The builder rep is often genuinely helpful, and the builder rep represents the seller. Texas law generally requires a written buyer representation agreement before a license holder shows you a home, per the Move to Texas guide, July 2026. That agreement is what makes representation real rather than assumed.
The co-op is already built into the builder's budget in most DFW communities. Walking in alone does not usually earn you a discount, it just removes the person whose job is to read Paragraph 7 and ask what happens if the appliance package changes. Come back to that number: roughly a $90,000 average gap between list and sold price on DFW new construction in August 2026. Real money moving on a document the builder's lawyers wrote. Have your own reader.
Bringing it together
Substitution clauses are standard, they exist for real supply chain reasons, and you will not get one struck from a production builder's contract. What you can do is make the word comparable mean something by naming every selection with a brand, a model, and a color inside the Construction Documents. Photograph the model, keep the change order file, and verify at pre-drywall and again at the final walkthrough. Handle it before you sign, because afterward you are working from a much weaker position.
- Read the New Construction Buyer Guide before your next model home visit
- Download the Lone Star Living App to view DeSoto listings and track nearby activity
- Book an appointment today or call 972-846-9170
Key takeaways
- Even the TREC New Home Contract (Incomplete Construction) lets the seller substitute materials, equipment, and appliances of comparable quality. Production builder contracts are typically broader.
- The Construction Documents are the boundary. Anything not named there by brand, model, and color is hard to enforce later.
- A substitution is a right you already granted. A change order requires your signature.
- DFW new construction averaged 79 days on market with roughly a $90,000 average gap between list and sold price in August 2026, per North Texas Market Insider citing NTREIS.
- Bring your own agent before your first model home visit. The co-op is already budgeted, and the team rebate returns up to 1% at closing, up to $10,000.
FAQ: DeSoto TX new construction contracts
What is a substitution clause in a new construction contract?
It is the contract paragraph that lets your builder replace specified materials, equipment, and appliances with items of comparable quality. The TREC New Home Contract (Incomplete Construction) includes one in Paragraph 7, and most production builders use a broader version in their own purchase agreement.
Do I get money back if the builder substitutes a cheaper item?
It depends on your contract language. Some production builder agreements limit your remedy for a missing option to the builder's cost of that item, not what you paid, and a genuinely comparable substitution may carry no credit at all.
Can I refuse a builder substitution in Texas?
Not automatically. If your contract grants substitution rights without notice or approval, the builder can act without your signature. Negotiate written notice and approval rights above a dollar threshold before you sign.
Do builders in DeSoto use the TREC new home contract?
Some do, but large production builders in DeSoto 75115 typically use their own purchase agreement drafted by their attorneys. Ask which contract you are signing at the first meeting and request a copy before you commit.
When should I check for substitutions during construction?
At two points minimum. Pre-drywall, while windows, framing, and rough plumbing are visible, and at the final walkthrough for fixtures, appliances, and finishes. Bring your dated model photos and signed selection sheet to both.
Where can I see new construction homes for sale in DeSoto TX?
Active DeSoto new construction includes Summit Parks, Homestead at Daniel Farms, and Kentsdale Farms. Download the Lone Star Living App to browse DeSoto 75115 listings, save searches, and get alerts when new inventory posts.
About the author
Steven J. Thomas is a dual-licensed Texas real estate broker and loan officer based in DeSoto, TX. Office: 128 S. Cockrell Hill Rd, DeSoto, TX 75115. Phone: 972-846-9170.
This article is educational content about new construction contract language. It is not legal advice. Have a Texas attorney review your builder contract before you sign. Market data reflects the sources and dates listed and is based on current conditions, which change. Listed prices were accurate at the time of writing and are subject to change. No price, rate, timeline, or outcome is guaranteed.
Steven J. Thomas · Broker, Refind Realty DFW · TREC Broker License #0657467 · Loan Officer, Envision Home Lenders · NMLS #689220
Equal Housing Opportunity.
Stay Informed With My Downloadable
Buyer and Seller guides

6 Smart Ways to Build Home Equity

7 Insider Secrets To Selling Your Home w/o a Lot of Time or Money

DFW Home Seller Negotiation Secrets

Home Appraisals Guide

Avoiding Pitfalls That Can Derail Your Home's Sale

Ultimate Guide To Buying a Home

A First Time Homebuyers Guide In DFW

Are You Ready To Buy?

25 Insider Secrets To Buying A Home

How to Improve Your Credit
Download All My Guides For Free
Steven J. Thomas
Steven J. Thomas has been in the financial services industry for the past 19 years and started my career as a Financial Planner for American Express Financial Advisors. I entered into banking with JP Morgan Chase as personal banker in 2003 and was promoted several times up to Small Business Specialist. I earned multiple Million Dollar Club awards and was ranked in the top 5 Small Business Specialist before I branched out in 2005 to start my own Financial Management Company. I ran a successful company before family circumstances lead me to Wachovia Bank in 2008 where I worked as a Senior Financial Specialist. As a Sr. Financial Specialist; I was responsible for the P & L and revenue growth of my banking center. The elimination of my role thru a bank merger lead me to BBVA Compass. I have held various leadership roles at BBVA Compass including Personal Relationship Manager, Branch Retail Executive, Workplace Solutions VP, and his current role as a Retail Manager. As the Regional Workplace Solutions VP, I was responsible for the strategic, tactical, and execution of Partnership Banking relationships, promotion and activity with corporate and non-profit companies in my footprint. I was responsible for the acquisition production for three districts, which includes 51 banking centers and over 300 employees. In May of 2014, I joined the team at Refind Realty and became one of the managing partners in mid-2015.
Wondering What Your DFW Home Could Be Worth in2026?
Get a Professional Home Valuation From A Local Market Expert
Unlock insights into potential selling prices.
Get a personalized analysis sent directly to your inbox.
Stay ahead with updates on property value fluctuations.
Benchmark your property against neighborhood listings.
Get a FREE Home Valuation And Potential Net Sheet:
I used this realtor and it was a great experience. He was patient and very helpful with our journey. He also helped us find a great lender with little hassle on the process, also got us approved for well above the market of our original home so we were able to get more house with a lower mortgage rate. So to anyone who is interested in buying a home take my advice give Steven a call. It’s worth it 😁
Bryant Loring

Steve was absolutely amazing! Everything was easy! Very professional in all aspects. Punctual, responsive, and diligent. He goes above and beyond to ensure you get to see as many homes as you’d like no matter the location. Not only was he knowledgeable about home buying, he also has a resourceful network for new home owner needs. I recommend Refind Realty to everyone!
Nicholas Bishop
I definitely recommend Steven to assist with your home buying needs. As a first time home buyer the process can be overwhelming, but as my realtor he was knowledgeable & patient while addressing my concerns and assisting me with my new home purchase. Thanks again Steven!! :-)
Gayle Mason
Ask Us Anything
Frequently Asked Questions
Why do you need a Realtor?
When buying or selling a home, there are so many options…which can also present a lot of obstacles. Laws change, forms change, and practices change all the time in the real estate industry. Because it’s our job to stay on top of those things, hiring a realtor reduces risk, and can also save you a lot of money in the long run.
When you work with me as your Realtor, you’re getting an expert who knows the area; knows how to skillfully guide your experience as a seller or buyer; can easily spot the difference between a good deal and a great deal. My job is to translate your dream into a real estate reality, and I work hard to earn and keep my business. This also means earning your trust: When you work with me, you’ll be working with a realtor who looks out for your best interests and is invested in your goals.
Which loan should you choose?
There are two different types of loans conventional loans and government-backed loans. The main difference is who insures these loans:
1 - Government-backed loans (FHA, VA and USDA):
(a) - Are, unsurprisingly, backed by the government.
(b) - Include FHA loans, VA loans, and USDA loans.
(c) - Make up less than 40 percent of the home loans generated in the U.S. each year.
2 - Conventional loans
(a) - Are not backed by the government.
(b) - Include conforming and non-conforming loans (such as jumbo loans).
(c) - Make up more than 60 percent of the loans generated in the U.S. each year.
What is the difference between FHA, VA and USDA loans?
1 - FHA LOANS:
FHA loans, which are insured by the Federal Housing Administration, are typically designed to meet the needs of first-time homebuyers with low or moderate incomes. FHA loans can be approved with a down payment of as little as 3.5 percent and a credit score as low as 580.
FHA loans are often called “helper loans,” because they give a leg up to potential borrowers who may not be able to secure one otherwise. For this reason, FHA loans have maximum lending limits, which are determined based on housing values for the county where the for-sale home is located.
Because the agency is taking on more risk by insuring FHA loans, the borrower is expected to pay mortgage insurance both at the time of closing and on a monthly basis, and the property must be owner-occupied.
2 - VA LOANS:
VA loans are backed by the Department of Veterans Affairs and they are guaranteed to qualified veterans and active-duty personnel and their spouses. VA loans can be approved with 100 percent financing, meaning VA borrowers are not required to make a down payment.
Unlike FHA loans, borrowers do not have to pay mortgage insurance on VA loans.
3 - USDA LOANS:
You may also hear about USDA loans, which are backed by the United States Department of Agriculture mortgage program. USDA loans are intended to support homeowners who purchase homes in rural and some suburban areas. USDA loans do not require a down payment and may offer lower interest rates; borrowers may have to pay a small mortgage insurance premium in order to offset the lender’s risk.
What’s a conventional loan? Understanding what it means to be conforming and non-conforming
Buyers who have a more established credit history and a larger down payment may prefer to apply for a conventional loan. These loans may offer a lower interest rate and only require the home buyer to purchase monthly mortgage insurance while the loan-to-value ratio is above a certain percentage, so a conventional loan borrower can typically save money in the long run.
Conventional loans are divided into two types: Conforming loans and non-conforming loans.
1 - CONFORMING LOANS:
Conforming loans are those that meet (or conform to) predetermined standards set by Fannie Mae and Freddie Mac — two government-sponsored institutions that buy and sell mortgages on the secondary market. By selling the loans to "Fannie and Freddie," lenders can free up their capital and return to issue more mortgages than if they had to personally back every loan that they approve.
The main standard for conforming loans is that the amount borrowed must be under a certain amount; in Alaska, a single-family home loan must be under $647,200 in order to be considered conforming.
Properties with more than one unit have higher limits.
2 - NON-CONFORMING (JUMBO) LOANS:
But what happens if a borrower wants to borrow more than the Freddie- and Fannie-approved loan amount? In this case, they would have to apply for a “jumbo loan,” which is the most common type of non-conforming loan.
Because the lender cannot resell the jumbo loan (or any non-conforming loan) to Freddie Mac or Fannie Mae, jumbo loans are considered to be riskier than a conforming loan. To protect against this risk, the bank will typically require a higher down payment; the interest rate on a jumbo loan may also be higher than if the same borrower applied for a conforming loan.
What kind of rate should you choose?
Rate types: Fixed-rate vs. adjustable-rate mortgages.
In addition to the loan type you choose, you’ll also have to determine if you want a fixed-rate mortgage or an adjustable-rate mortgage (ARM). A fixed-rate mortgage has an interest rate that does not change for the life of the loan, so it provides predictable monthly payments of principal and interest.
An adjustable-rate mortgage typically offers an initial introductory period with a low-interest rate. Once this period is over, the interest rate adjusts periodically, based on the market index. The initial interest rate on an ARM can sometimes be locked in for different periods, such as one, three, five, seven, or 10 years. Once the introductory period is over, the interest rate typically readjusts annually.
Locate Us
Site: www.stevenjthomas.com
Call :(972) 846-9170
Email: [email protected]
Office 128 S. Cockrell Hill Rd, DeSoto TX 75115
Owned and Operated by Thomas & Thomas Financial Group, LLC
© Copyright 2026 | All Rights Reserved
Steven J. Thomas, REALTOR® · TREC License #0657467
Privacy Policy | Terms of Service | Fair Housing Statement
Refind Realty DFW · 128 S. Cockrell Hill Rd, DeSoto, TX 75115 · (972) 846-9170
Facebook
Instagram
X
LinkedIn
Youtube
TikTok